
Protecting Your Agricultural Business in a Changing World
Agribusiness insurance is specialized coverage designed to protect farming operations, processors, distributors, and other agricultural businesses from unique risks that standard business policies don’t adequately address.
Here’s what you need to know about agribusiness insurance:
- Coverage types: Property, liability, auto, workers’ compensation, crop, livestock, equipment breakdown, business interruption
- Who needs it: Family farms, commercial growers, food processors, grain elevators, vineyards, feed mills, farm supply stores
- Key benefits: Protection against weather events, liability claims, equipment failures, and business disruptions
- Specialized options: Pollution liability, product recall, agritourism coverage, cyber protection
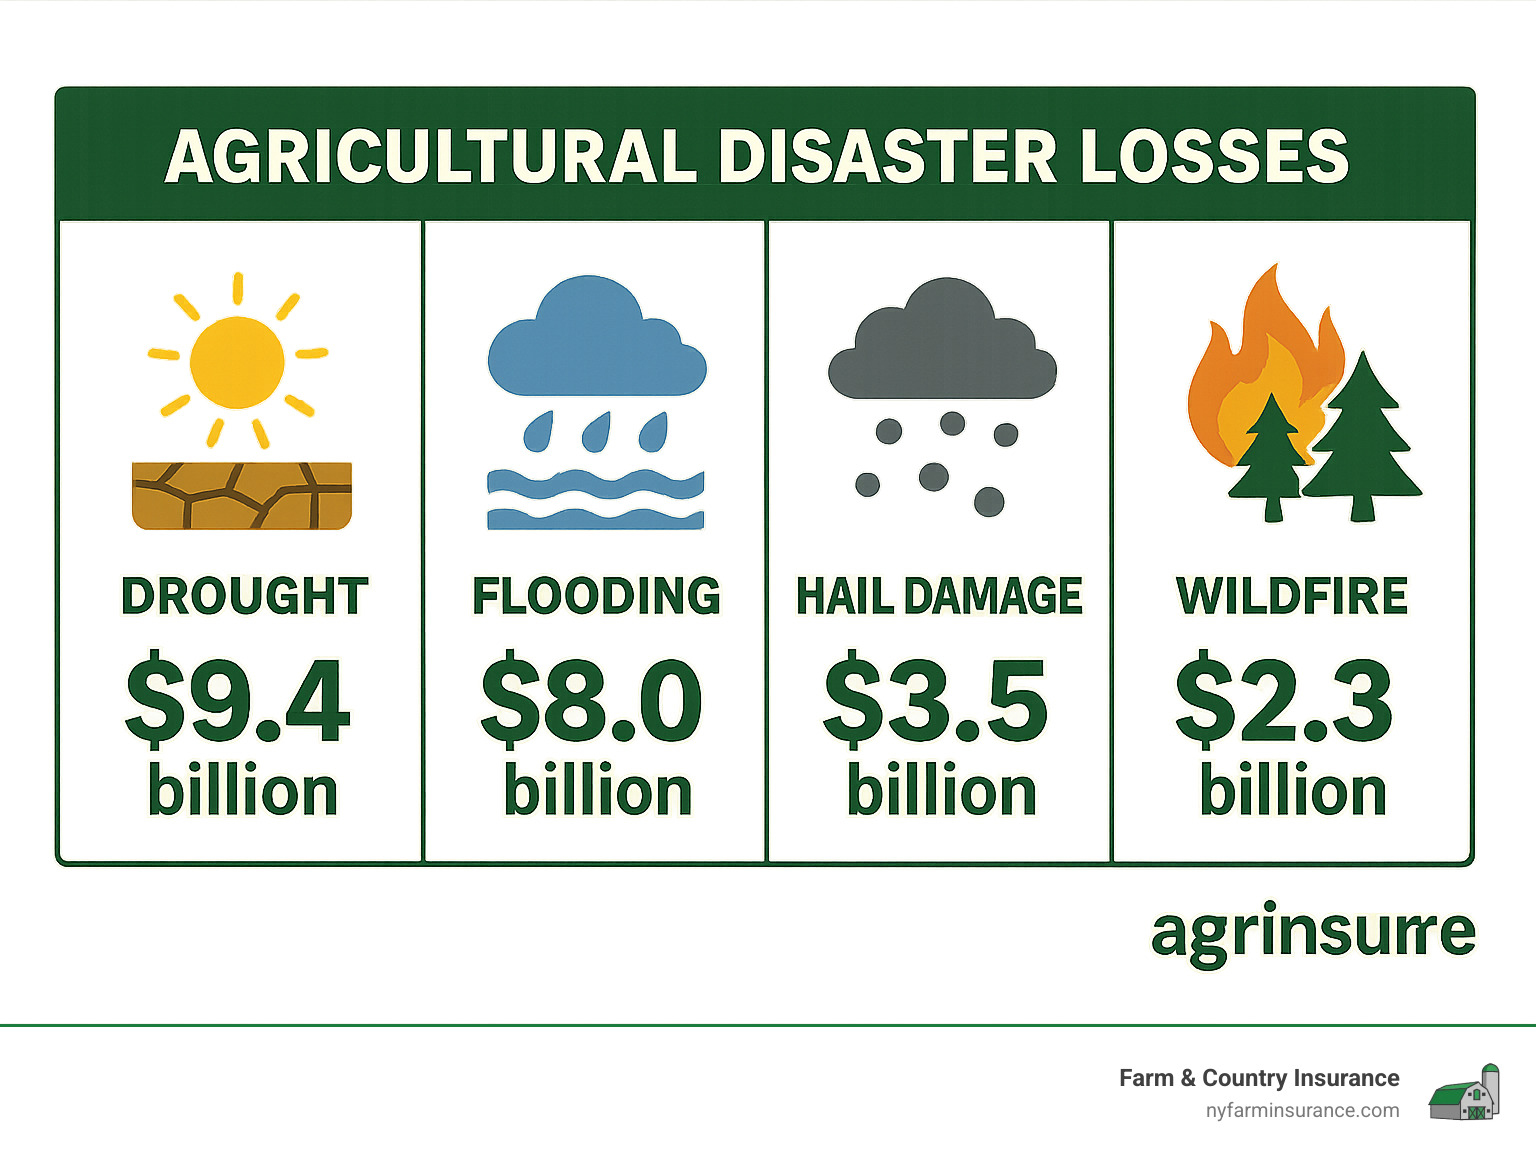
In 2023 alone, natural disasters caused more than $21.94 billion in crop and rangeland losses across the United States. With the world’s population expected to grow from 7.5 billion to 10 billion by 2050 (requiring at least a 70% increase in food availability), agricultural operations face increasing pressure to manage risks effectively while maximizing production.
As a New York State farmer, you’re part of an essential industry with 30,650 farms covering 6.5 million acres. Your operation likely faces unique exposures that require custom insurance solutions rather than generic commercial policies.
“To succeed in the evolving agribusiness landscape you must understand the risks that threaten your operation and your options to help protect it,” notes industry experts. This is especially true for the 98% of New York farms that are family-owned and represent generations of hard work and investment.
I’m Casey Love, owner of Farm & Country Insurance, specializing exclusively in agribusiness insurance with deep roots in New York’s farming communities. My experience helping hundreds of agricultural operations secure customized coverage ensures your farm’s unique risks are properly protected.

Agribusiness Insurance 101: Definition, Scope & Who Needs It
Agribusiness insurance is specialized coverage custom for commercial farming operations and related businesses that grow, manufacture, process, and distribute agricultural products. It goes far beyond what standard business policies offer, addressing the unique challenges and risks that come with agricultural production and distribution.

Here in New York, our agricultural landscape is wonderfully diverse. From the sprawling dairy farms of Cayuga County to the picturesque vineyards dotting the Finger Lakes region, each operation faces its own set of challenges. At Farm & Country Insurance, we’ve walked alongside farmers through drought years and bumper crops alike, and we understand that cookie-cutter insurance solutions simply don’t cut it.
Did you know New York is home to 30,650 farms covering 6.5 million acres? Each one needs protection as unique as the land they tend.
What Sets Agribusiness Insurance Apart from Standard Policies
When you’re in the business of growing food or raising livestock, your insurance needs are fundamentally different from those of a retail store or office.
Agribusiness insurance recognizes these differences by bundling property and liability coverages specifically designed for agricultural operations. Your barns, silos, irrigation systems, and specialized equipment require valuation methods that standard policies might miss entirely. The seasonal nature of farming means your inventory value can triple during harvest time – something a standard business policy won’t account for.
Weather vulnerability is another critical factor. When a severe storm rolls through, it doesn’t just damage your buildings – it can destroy an entire season’s worth of crops. Food safety concerns bring another layer of complexity, with contamination and recall exposures that most businesses never face.
“Farm insurance eliminates the confusion and allows you to simplify your insurance into a single policy,” as many of our clients have finded. This comprehensive approach ensures there are no dangerous gaps between your home, personal property, and business assets protection.
Types of Operations Classified as Agribusinesses
Agriculture in New York State contributes nearly 200,000 jobs to our economy, spanning a remarkable variety of operations. The businesses that typically benefit from agribusiness insurance include:
Family farms and ranches, commercial growers, grain operations, dairy farms, and livestock producers form the backbone of our agricultural community. Supporting these are the processors and distributors – food manufacturers, feed mills, grain elevators, and farm supply stores that keep the industry moving.
Specialty operations like vineyards, wholesale nurseries, and seed production facilities face their own unique challenges. And let’s not forget the growing agritourism sector, with corn mazes, farm tours, and U-pick operations that invite the public onto agricultural land.
Each of these businesses faces distinct exposures that require specialized coverage. A vineyard hosting weekend tastings has very different liability concerns than a grain elevator. A dairy operation’s property needs bear little resemblance to those of a farm supply store.
At Farm & Country Insurance, we’ve spent decades learning the ins and outs of these operations. We know that your farm isn’t just a business – it’s often your home, your heritage, and your future all rolled into one. That’s why we take the time to understand exactly what makes your operation unique before recommending coverage.
Want to learn more about the specific risks and coverages for your type of agribusiness? Visit our detailed guide on Agribusiness for more information.
Coverage Breakdown: Core to Specialized Protections
When it comes to protecting your farm or agricultural business, there’s no such thing as a one-size-fits-all solution. At Farm & Country Insurance, we understand that New York farmers face unique challenges that require custom protection strategies. We work with you to build comprehensive agribusiness insurance programs that address both everyday risks and those specific to your operation.
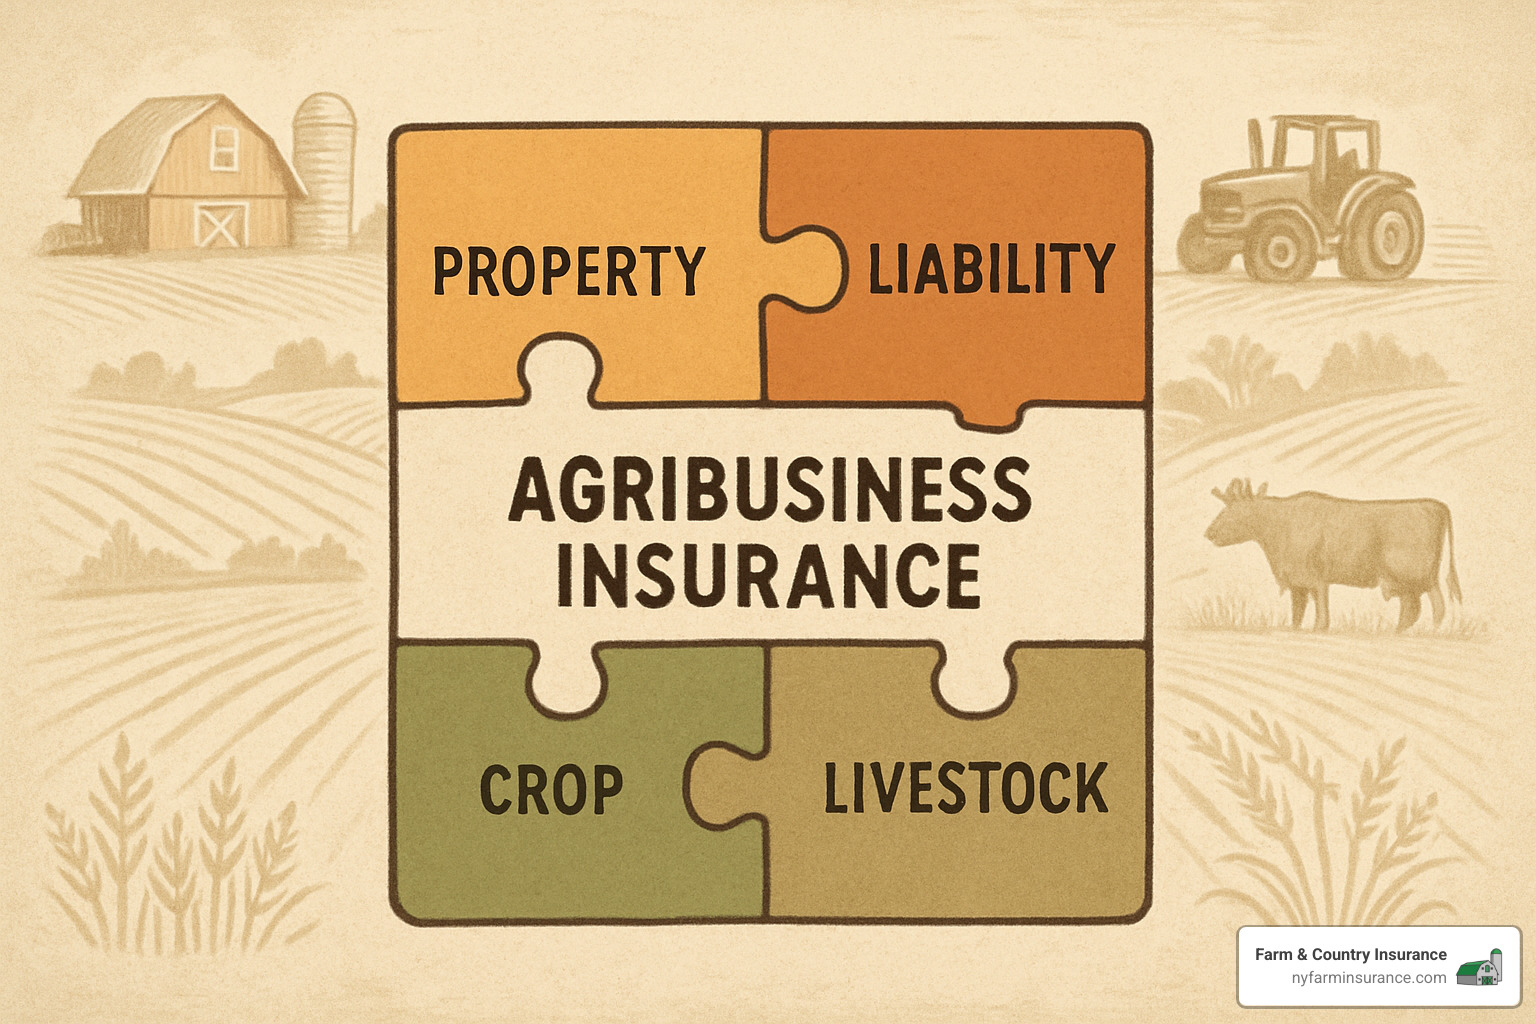
Core Agribusiness Insurance Coverages You Can’t Ignore
Every farm, whether you’re raising dairy cows in Wyoming County or growing apples in the Hudson Valley, needs certain fundamental protections. Think of these as the backbone of your agribusiness insurance plan:
Property Coverage protects your physical assets – those barns, silos, and processing facilities that represent generations of investment. It also covers your equipment, machinery, and inventory like seed, feed, and fertilizer. We can write your policy with different valuation methods depending on your needs: Actual Cash Value accounts for depreciation, Replacement Cost Value provides full replacement, and Functional Replacement Cost covers modern equivalents of older structures.
General Liability is your shield against claims when someone gets injured on your property or claims your products caused harm. This includes defense costs, which can be substantial even if you’ve done nothing wrong. As one of our dairy farmers recently told us, “I never thought I’d get sued until a delivery person slipped on ice near my milk house. That liability coverage saved my operation.”
Commercial Auto coverage is essential for any farm vehicles that travel public roads. That grain truck you use during harvest or the pickup that runs to the feed store – they all present significant liability exposure once they leave your property.
Workers’ Compensation isn’t just a legal requirement if you have employees – it’s peace of mind. Agriculture remains one of the most hazardous industries, and this coverage ensures your workers are protected while shielding your operation from potentially devastating claims.
Multi-Peril Crop Insurance (MPCI) works alongside your standard agribusiness insurance to protect your income when Mother Nature doesn’t cooperate. While administered through the USDA’s Risk Management Agency, we can help you understand how it fits into your overall protection strategy. More info about Agricultural Business Insurance
Optional & Niche Endorsements for Unique Risks
Beyond these essentials, we offer specialized coverages that address the unique aspects of your operation:
Pollution Liability steps in when standard policies won’t. If you accidentally release pesticides, fertilizers, or fuel, this coverage helps with cleanup costs and third-party claims. For New York farmers working near watersheds or residential areas, this protection is increasingly important.
Equipment Breakdown coverage can be a lifesaver during critical times. When that combine breaks down mid-harvest or your milk cooling system fails, this coverage helps with repairs and lost income during downtime.
Product Recall protection is vital for food producers. Imagine having to pull your products from store shelves due to contamination concerns – the costs can be staggering without proper coverage.
Agritourism Liability provides specialized protection for farms that welcome visitors for pick-your-own operations, corn mazes, or farm tours. Standard policies often exclude these activities, leaving a dangerous gap in coverage.
Cyber Liability has become essential as farms increasingly adopt digital technologies. From precision agriculture systems to online sales platforms, your digital assets need protection from increasingly sophisticated threats.
Business Interruption coverage keeps money flowing when disaster strikes. After a fire or windstorm damages your facilities, this coverage helps replace lost income while you rebuild.
Livestock Mortality and Disease protection safeguards your investment in animals, particularly important for dairy operations or those with high-value breeding stock.
Peak Season Coverage recognizes that your inventory – and risk exposure – fluctuates throughout the year, providing increased limits during harvest or high-inventory periods.
Parametric Weather Insurance offers innovative protection triggered by specific weather events like excessive rainfall or drought, paying out quickly without the traditional claims process. Latest data on crop losses
At Farm & Country Insurance, we don’t just sell policies – we build protection plans that grow with your operation. We understand that each farm has its own unique risk profile, whether you’re managing a century-old family dairy or launching a new vineyard in the Finger Lakes. Our deep agricultural roots mean we speak your language and understand the challenges you face every day.
Determining & Maintaining the Right Protection
Selecting the right agribusiness insurance coverage is just the first step in protecting your farm operation. As your business grows and evolves, your insurance needs will change too.
Step-by-Step Agribusiness Insurance Sizing Process
At Farm & Country Insurance, we’ve helped countless New York farmers find the perfect coverage balance. Here’s how we approach this important process:
Start with a thorough asset inventory of everything you own—from your main barn to that vintage tractor you still use during harvest. Document building ages, equipment conditions, and current replacement values. I can’t tell you how many times I’ve seen farmers shocked at how much their operation is actually worth when we put it all on paper!
Next, we’ll identify your unique exposures. A U-pick apple orchard faces completely different risks than a dairy operation or grain farm. We’ll look at who visits your property, what contracts you have with suppliers, and even your environmental considerations like chemical storage or manure management.
Your loss history tells an important story too. Have you filed multiple claims for the same issue? That might signal a problem we can address with preventive measures rather than just insurance. As one farmer told me recently, “I never realized our equipment breakdowns followed a pattern until we looked at five years of claims together.”
Choosing the right deductibles is all about balance. Higher deductibles mean lower premiums but more out-of-pocket costs when something goes wrong. We’ll help you find that sweet spot based on your operation’s cash flow and risk tolerance.
When it comes to coverage structure, some farms do best with comprehensive package policies while others need individual policies for specific risks. For operations with multiple revenue streams, Whole-Farm Revenue Protection might make sense. And don’t forget about umbrella liability—it’s relatively inexpensive protection against those catastrophic claims that could otherwise devastate your farm.
Finally, consult with specialists who truly understand agriculture. At Farm & Country Insurance, we live and breathe New York farming. We know the difference between a heifer and a Holstein, and we understand why your sprayer needs special coverage during application season. This agricultural expertise matters when crafting your protection plan.
Beyond Insurance: Proactive Risk Management
Insurance is crucial, but it’s just one piece of your farm’s protection puzzle. The best claim is the one you never have to file!
Employee training might not seem like an insurance issue, but well-trained workers are far less likely to cause accidents. Whether it’s proper chemical handling procedures or equipment operation safety, investing in training pays dividends in reduced claims and a safer workplace.
Don’t underestimate the power of regular maintenance. That loose electrical connection in the milking parlor? The worn hydraulic hose on your combine? These small issues can lead to major losses if left unchecked. Preventive maintenance is always cheaper than emergency repairs—or worse, a total loss.
For livestock operations, biosecurity measures are non-negotiable. One breach could introduce disease that decimates your herd. Simple visitor protocols, equipment sanitation between fields, and feed quality controls can protect your animals and your bottom line.
Every farm needs a continuity plan. What happens if your irrigation system fails during a drought? Or if your primary milk hauler goes out of business? Having backup systems and alternative suppliers identified before disaster strikes can mean the difference between a minor hiccup and a major crisis.
Staying on top of regulatory compliance not only keeps you legal—it keeps you safer. From Food Safety Modernization Act requirements to environmental protection regulations, compliance programs reduce your risk exposure and often lead to better operational practices.
“Insurance is what you need when your risk management fails,” a wise farmer once told me. At Farm & Country Insurance, we believe in helping you build both: robust agribusiness insurance coverage and practical risk management strategies that work together to protect everything you’ve built.
Looking for specialized guidance on protecting your unique operation? Learn more about working with an Ag Insurance Agency that truly understands your needs.
Claims, Federal Programs & Compliance Essentials
When disaster strikes your farm, understanding how your agribusiness insurance responds—and how it works alongside federal programs—can make all the difference in your operation’s recovery and future.
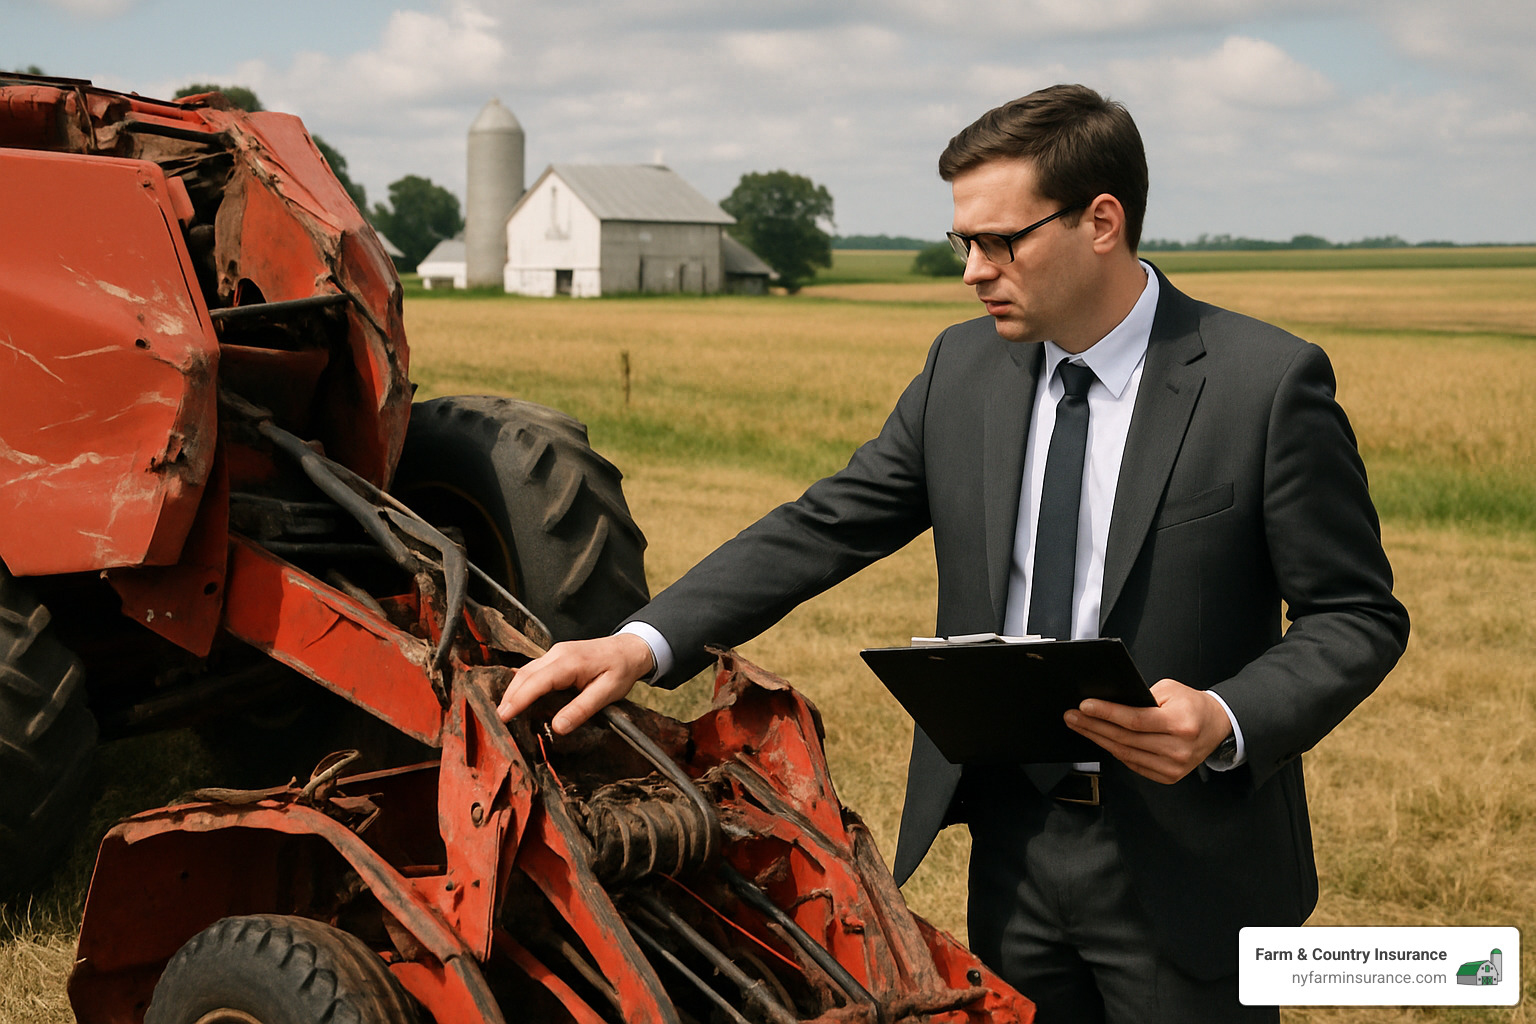
How Agribusiness Insurance Responds to Loss Scenarios
The true value of your insurance becomes clear when you need to file a claim. Here’s how coverage typically responds to common farm disasters:
When hail pounds your barn roof, your property coverage steps in to pay for repairs or replacement. The check you receive depends on your chosen valuation method—actual cash value, replacement cost, or functional replacement cost—but having the right coverage means you won’t face the full financial burden alone.
Take the Cayuga County dairy farmer who experienced devastating roof damage during last year’s hailstorm. Because they had replacement cost valuation, their policy covered the full $75,000 needed for modern materials and complete restoration, not just the depreciated value of their 15-year-old roof.
Liability protection proves its worth when the unexpected happens. When a visitor slipped on wet concrete at an Owasco U-pick operation, their agribusiness insurance covered the $15,000 in medical expenses plus $5,000 in legal fees, resolving the situation before it escalated to a costly lawsuit.
Vehicle incidents can be particularly troublesome for farm operations. A grain truck from a Scipio farm collided with a passenger vehicle on a county road last harvest season. Their commercial auto policy handled the $50,000 in damage to the other vehicle and $100,000 in medical expenses for the injured driver—expenses that would have been catastrophic if paid out-of-pocket.
Disease outbreaks among livestock represent another significant risk. When a dairy herd in Fleming was affected by disease, specialized livestock mortality coverage provided $150,000 to help rebuild the herd without financial devastation. Without this protection, generations of careful breeding and investment could have been lost.
The claims process itself follows a predictable pattern: report promptly, document thoroughly with photos and notes, meet with the adjuster, review the settlement offer, and receive payment to begin repairs. At Farm & Country Insurance, we walk alongside our clients through each step, ensuring fair and timely settlements when you need them most.
Leveraging Federal Safety Nets Alongside Your Policy
Your private agribusiness insurance works hand-in-hand with several federal programs to create a comprehensive safety net:
Multi-Peril Crop Insurance (MPCI) forms the foundation of risk management for most crop producers. This federally subsidized program protects against yield losses from natural causes, with coverage levels from 50% to 85% of expected yield or revenue. The government covers 33–62% of premium costs, making this protection more affordable for farmers facing tight margins.
For specialty crop producers growing commodities not covered by traditional crop insurance, the Noninsured Crop Disaster Assistance Program (NAP) fills important gaps. With a service fee up to $325 per crop (capped at $825 per county), NAP provides basic catastrophic coverage with additional buy-up options for greater protection.
Market-related losses trigger different concerns than production losses. That’s where Agricultural Risk Coverage (ARC) and Price Loss Coverage (PLC) programs come in. These safety nets are triggered by county-level revenue shortfalls or national price declines, complementing your crop insurance by addressing different risk factors.
New York’s substantial dairy industry benefits from the Dairy Margin Coverage (DMC) program, which provides payments when the difference between milk price and feed cost falls below your selected coverage level. This protection against margin compression works alongside private dairy insurance products for more complete protection.
The Supplemental Coverage Option (SCO) helps narrow the gap between individual coverage levels and total crop value. This county-level coverage supplements your individual MPCI policy by covering a portion of your deductible, with USDA paying 65% of the premium cost.
Effectively coordinating these federal programs with your private agribusiness insurance requires expertise in both systems. At Farm & Country Insurance, we help clients develop integrated risk management strategies that maximize protection while controlling costs. We understand the unique challenges facing New York farmers and can help you steer both private insurance and government programs to create the strongest possible safety net for your operation.
Whether you’re dealing with a severe weather event, liability claim, or market downturn, having the right combination of private insurance and federal program participation ensures your farm can recover and continue its legacy. We’re here to help you understand how these protections work together to safeguard everything you’ve built.
Emerging Risks & Your Questions Answered
The agricultural landscape is evolving rapidly, with new technologies and changing climate patterns introducing novel risks that require innovative insurance solutions.

Agribusiness Insurance and AgTech Innovations
Modern farming increasingly relies on technology, creating new exposures that traditional agribusiness insurance policies might not adequately address:
- Precision Agriculture Equipment
- GPS-guided tractors and harvesters
- Variable-rate application systems
- Remote sensing technologies
These high-value systems require specialized coverage for both physical damage and operational failures.
- Drone Operations
- Aerial imaging and crop monitoring
- Targeted application of inputs
- Liability exposures from operations
Standard liability policies may exclude drone-related incidents, necessitating specific coverage.
- Internet of Things (IoT) Sensors
- Soil moisture monitors
- Weather stations
- Livestock health trackers
- Equipment performance sensors
These connected devices introduce cyber vulnerabilities that traditional farm policies don’t address.
- Data Management and Analytics
- Crop yield data
- Soil testing information
- Market forecasting systems
The value of agricultural data assets and potential liability from data breaches require new insurance approaches.
- Autonomous Equipment
- Self-driving tractors
- Robotic milking systems
- Automated feeding systems
The liability implications of autonomous equipment failures present complex insurance challenges.
As one industry expert notes, “To succeed in the evolving agribusiness landscape it’s critical to know the risks that threaten your operation and understand your options to help protect it.” This is particularly true as AgTech adoption accelerates.
At Farm & Country Insurance, we stay at the forefront of these emerging risks, developing coverage solutions that protect your investment in agricultural technology while enabling innovation.
Frequently Asked Questions about Agribusiness Insurance
Do I need separate crop insurance if I already have agribusiness insurance?
This is one of the most common questions we hear at Farm & Country Insurance, and the answer is typically yes.
Agribusiness insurance packages are comprehensive, but they have specific boundaries. Your farm policy covers your barns, tractors, stored grain, and liability risks – but growing crops in the field are a different story altogether.
Think of it this way: the corn still standing in your field faces completely different risks than the corn you’ve already harvested and stored in your bin. Once harvested, your crops become business personal property covered under your farm policy. But while they’re growing? That’s where Multi-Peril Crop Insurance (MPCI) steps in.
MPCI is a separate program administered by the USDA Risk Management Agency that specifically protects against yield or revenue losses in your fields. What makes it particularly valuable is that the federal government subsidizes a significant portion of the premium – often 50-65% depending on your coverage level.
For New York farmers, we typically recommend a layered approach: agribusiness insurance for your operation’s physical assets and liability exposures, combined with crop insurance for your production risks. This strategy ensures you don’t have coverage gaps that could threaten your farm’s financial stability.
How does agribusiness insurance pricing work?
Pricing for agribusiness insurance isn’t one-size-fits-all – it’s custom to your specific operation. When we calculate premiums at Farm & Country Insurance, we consider several key factors.
Your operation’s type and size play a significant role. A 1,000-acre grain farm in Cayuga County will have different premium factors than a 50-acre vegetable operation in the Hudson Valley. We look at what commodities you produce, your annual revenue, total acreage, and for livestock operations, the number and type of animals.
Location factors matter tremendously. Is your farm near a fire station? What flood zone are you in? How vulnerable is your region to severe storms? All these geographical considerations impact your rates.
The coverage options you select naturally affect pricing. Higher limits, lower deductibles, and additional endorsements for specialized risks will increase premiums, but they also provide greater protection when losses occur.
Your loss history tells insurance carriers a story about your operation’s risk level. A farm with multiple claims in recent years will typically face higher premiums than one with a clean record. That’s why implementing strong risk management practices often pays for itself through premium savings.
Finally, your buildings’ characteristics factor into pricing. Newer structures with updated electrical systems generally cost less to insure than older buildings with outdated wiring. Metal buildings often receive better rates than wooden structures due to their superior fire resistance.
At Farm & Country Insurance, we work with multiple carriers to find the right balance of comprehensive coverage and competitive pricing for New York agricultural operations.
What’s the difference between a farm & ranch policy and a commercial agribusiness package?
The distinction between these policy types often causes confusion, but understanding the difference is crucial for proper coverage.
A farm & ranch policy is designed with the family farm in mind. It uniquely bridges personal and business insurance by covering both your home and your agricultural operation under one policy. This integration makes sense for operations where the family lives on the farm property and personal and business activities naturally overlap.
These policies typically provide coverage for your dwelling, personal belongings, farm structures, equipment, and liability – all wrapped into one package. They’re generally more straightforward in their rating structure and work well for small to medium-sized farms with relatively simple operations.
A commercial agribusiness package, on the other hand, is built for larger or more complex agricultural businesses. These policies focus exclusively on business assets and activities – they don’t include coverage for your personal residence or belongings. If you have a commercial agribusiness package, you’ll need a separate homeowners policy.
Commercial packages offer more customization options and specialized coverages for operations that involve significant processing, manufacturing, or distribution activities. They typically provide more robust business interruption coverage and higher liability limits, which become increasingly important as operations scale up.
Many New York farms fall somewhere in the middle of these categories. A family dairy that’s expanded to include a creamery, or a traditional grain operation that’s added direct-to-consumer sales might benefit from elements of both policy types.
At Farm & Country Insurance, we don’t force your operation into a predetermined box. Instead, we evaluate your specific situation to determine whether a farm & ranch policy or commercial agribusiness package better protects your livelihood. Our deep understanding of New York agriculture helps us create insurance solutions that grow and adapt alongside your farm business.
Conclusion
Navigating today’s agricultural landscape requires more than just hard work and good planning – it demands a thoughtful approach to protecting everything you’ve built. Agribusiness insurance forms the cornerstone of that protection, creating a safety net that lets you focus on what you do best: farming.
Throughout New York’s diverse agricultural regions, from the dairy operations of Cayuga County to the specialty crops of the Hudson Valley, one thing remains constant – the need for protection that truly understands your unique operation.
The most effective protection strategy combines several key elements:
First, your coverage must be custom specifically to your operation. The insurance that works for a vineyard won’t necessarily address the needs of a dairy farm or grain operation. At Farm & Country Insurance, we take the time to understand exactly what makes your farm unique before recommending solutions.
Second, true protection often comes from layering different types of coverage. Your private agribusiness insurance works alongside federal programs like MPCI or NAP to create a comprehensive safety net. This complementary approach ensures you’re not left with dangerous gaps in your protection.
Third, insurance works best when paired with proactive risk management. Simple steps like regular equipment maintenance, employee safety training, and emergency planning can prevent many losses before they happen. The best insurance claim is the one you never have to file.
Finally, your protection needs regular attention. As your operation grows and changes, your insurance should evolve with it. We recommend annual reviews to keep your coverage aligned with your current reality – not what your farm looked like years ago.
Since 1984, Farm & Country Insurance has been standing beside New York’s farmers through changing markets, evolving regulations, and unpredictable weather patterns. We’ve seen how the right agribusiness insurance program can make the difference between a temporary setback and a financial disaster.
Looking ahead, agriculture faces significant challenges – from feeding a growing global population to adapting to climate change and incorporating new technologies. With proper protection in place, your operation can steer these challenges from a position of strength and confidence.
Your farm represents more than just a business – it’s your heritage, your passion, and often your family’s future. Protecting it deserves the specialized attention that only comes from working with insurance professionals who truly understand agriculture.
To discuss your specific agribusiness insurance needs or schedule a comprehensive risk assessment of your operation, contact Farm & Country Insurance today. Our agricultural specialists are ready to help you protect what matters most—your farm, your family, and your future.