
Protecting Your Farm’s Lifeline: Equipment Insurance Essentials
When you wake up before dawn to harvest your corn or plant your spring crops, you’re relying on machinery that represents one of your farm’s biggest investments. That’s where agricultural equipment insurance comes in – not just as a policy, but as protection for your livelihood.
Agricultural equipment insurance provides specialized coverage designed specifically for farmers, protecting the machinery that keeps your operation running. Unlike standard property insurance, this coverage follows your equipment wherever it goes – across your fields, to a neighbor’s farm, or on public roads.
At its core, this insurance reimburses you when covered perils damage or destroy your equipment. These perils typically include fire, theft, vandalism, wind, hail, flooding, collision, and overturn incidents. Without this protection, a single equipment loss could set your operation back years.
The numbers tell a sobering story. American farmers invest approximately $13.7 billion annually in tractors and self-propelled machinery. Yet nearly 1,500 tractors disappear from farms each year, with a dismal recovery rate of only 16%. Meanwhile, severe weather events continue to increase in both frequency and intensity, putting your equipment at greater risk.
When choosing agricultural equipment insurance, most farmers select one of three approaches:
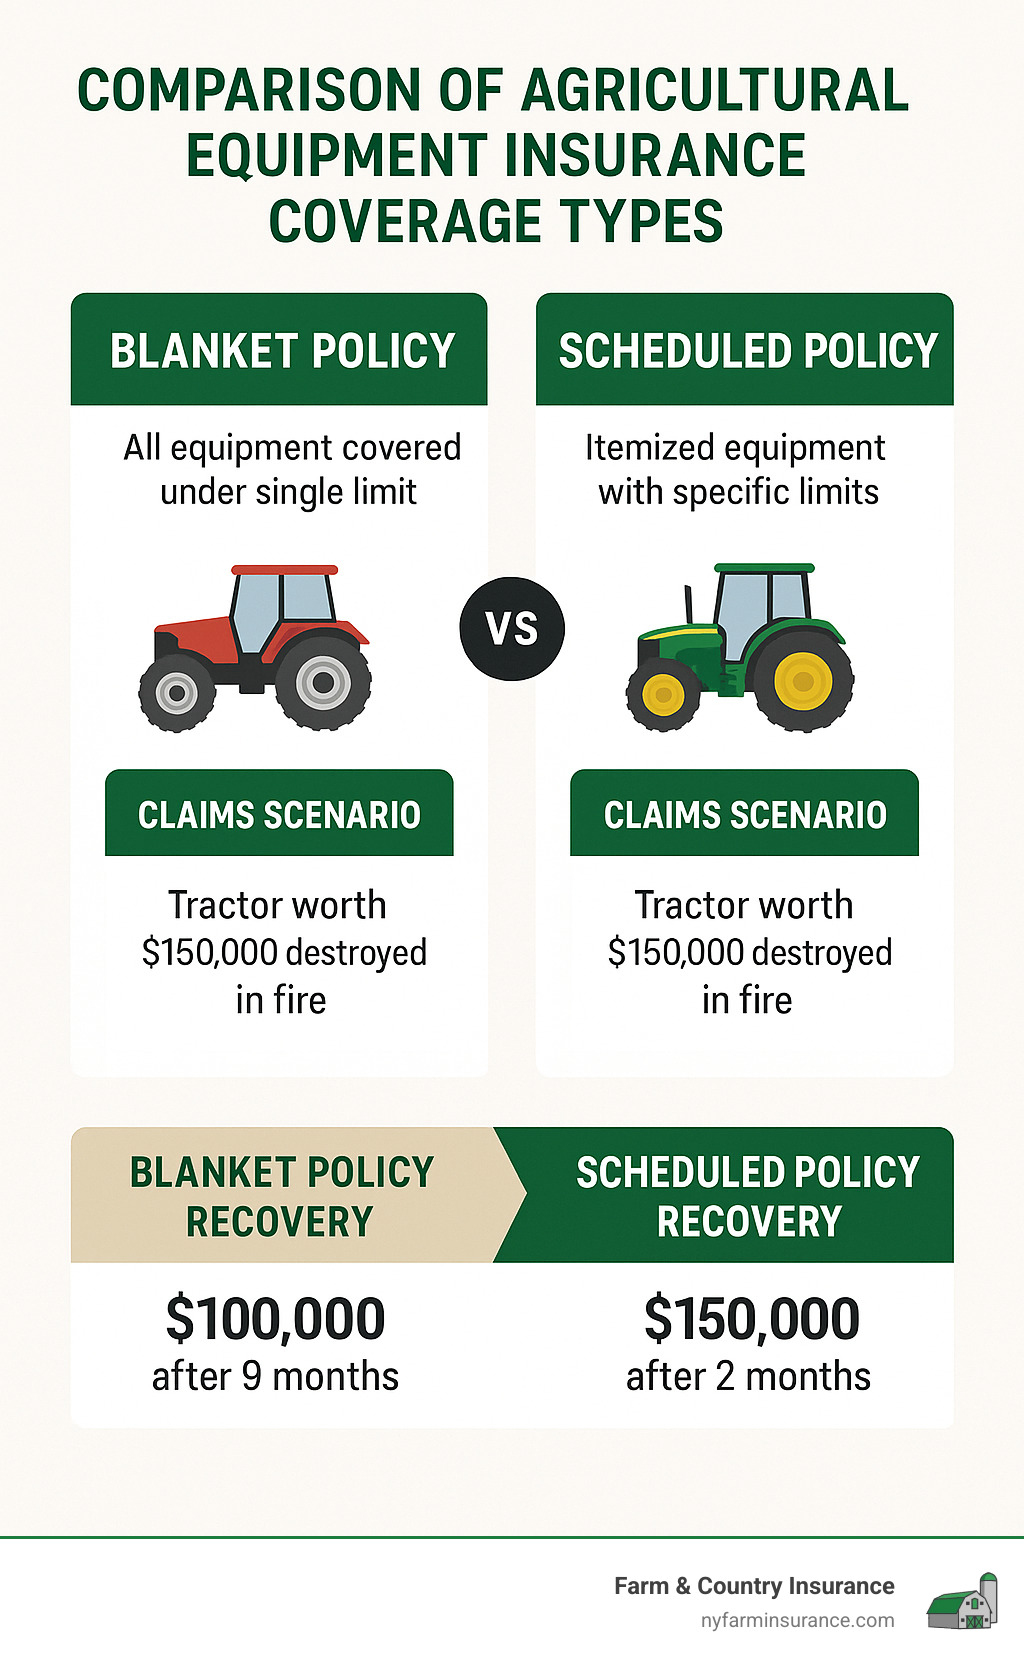
Blanket coverage provides simplicity with a single limit covering all your equipment. This works well for operations with many similar-valued items and frequent equipment changes.
Scheduled coverage offers itemized protection with specific values for each piece of equipment. This gives you greater certainty about replacement values for your most critical machinery.
Hybrid coverage combines both approaches – scheduling your high-value items individually while covering remaining equipment under a blanket limit. This balance often provides the best protection for diverse farming operations.

Here at Farm & Country Insurance, we’ve been helping New York farmers protect their equipment investments since 1984. We understand that every farming operation has unique needs, which is why we take the time to understand your specific equipment usage patterns and risks before recommending coverage.
What Is Agricultural Equipment Insurance?
Agricultural equipment insurance is a specialized form of coverage custom specifically for farmers and agricultural businesses. Think of it as protection designed for the unique challenges of farming operations – where your valuable machinery might be working across multiple locations rather than sitting in one place.
Unlike standard property insurance, agricultural equipment coverage is typically written on an inland marine basis. This simply means it’s designed for mobile property that moves from place to place – perfect for tractors, combines, and other equipment that travel between fields, storage locations, and sometimes public roads.
One of the most valuable aspects of this coverage is that it typically operates on an “open-perils” concept. Rather than limiting protection to specific scenarios, these policies cover all risks of physical loss unless specifically excluded. This provides much broader protection than “named perils” policies that only cover losses specifically listed.
As the Mobile Agricultural Machinery and Equipment Coverage Form (MAMECF) states: “Covered Causes of Loss means direct physical loss to Covered Property unless the loss is excluded or limited in this Policy.”
Most agricultural equipment policies also specify a policy territory – the geographic areas where coverage applies. This becomes especially important for farmers who operate across county or state lines, particularly during harvest season when equipment might travel significant distances from the home farm.
How Agricultural Equipment Insurance Differs from Property & Auto
When farmers ask us at Farm & Country Insurance why they can’t just rely on their property or auto insurance, we explain several critical differences that make agricultural equipment insurance essential.
Mobility Considerations: Standard property insurance works well for buildings and stationary equipment, but falls short for machinery that regularly moves between locations. While auto insurance covers road-registered vehicles, it’s designed primarily for transportation vehicles – not specialized farm implements. Agricultural equipment insurance bridges this gap by protecting machinery wherever farming operations take it.
Road Liability Gaps: Many farmers are surprised to learn that driving farm equipment on public roads creates significant liability exposures not covered by standard policies. As one farmer from Cayuga County told us: “I assumed my auto policy would cover my tractor when I drove it on the county road between fields. It wasn’t until after an accident that I finded the gap in my coverage. That mistake cost me nearly $15,000 out of pocket.”
Business-Use Exclusion: Personal auto policies typically exclude business use entirely. Since farm equipment is inherently used for business purposes, it requires specialized coverage that acknowledges its commercial nature and provides appropriate protection.
Trailer vs. Implement Distinctions: Auto policies might cover traditional trailers, but typically exclude implements towed behind tractors. Items like plows, discs, planters, and balers require specialized coverage that understands their unique function and value. Agricultural equipment insurance recognizes these distinctions and provides appropriate coverage for both trailers and implements.
The bottom line is that farming operations present unique insurance challenges that standard policies simply weren’t designed to address. Proper agricultural equipment insurance fills these critical gaps, giving farmers peace of mind that their substantial machinery investments are properly protected.
Why Farmers Need It: Risks & Real-World Losses
Farming has always been a profession of risk, but the modern farmer faces even greater stakes with the significant investment in equipment that powers today’s agricultural operations. The threats to these vital assets make agricultural equipment insurance not just advisable, but essential.
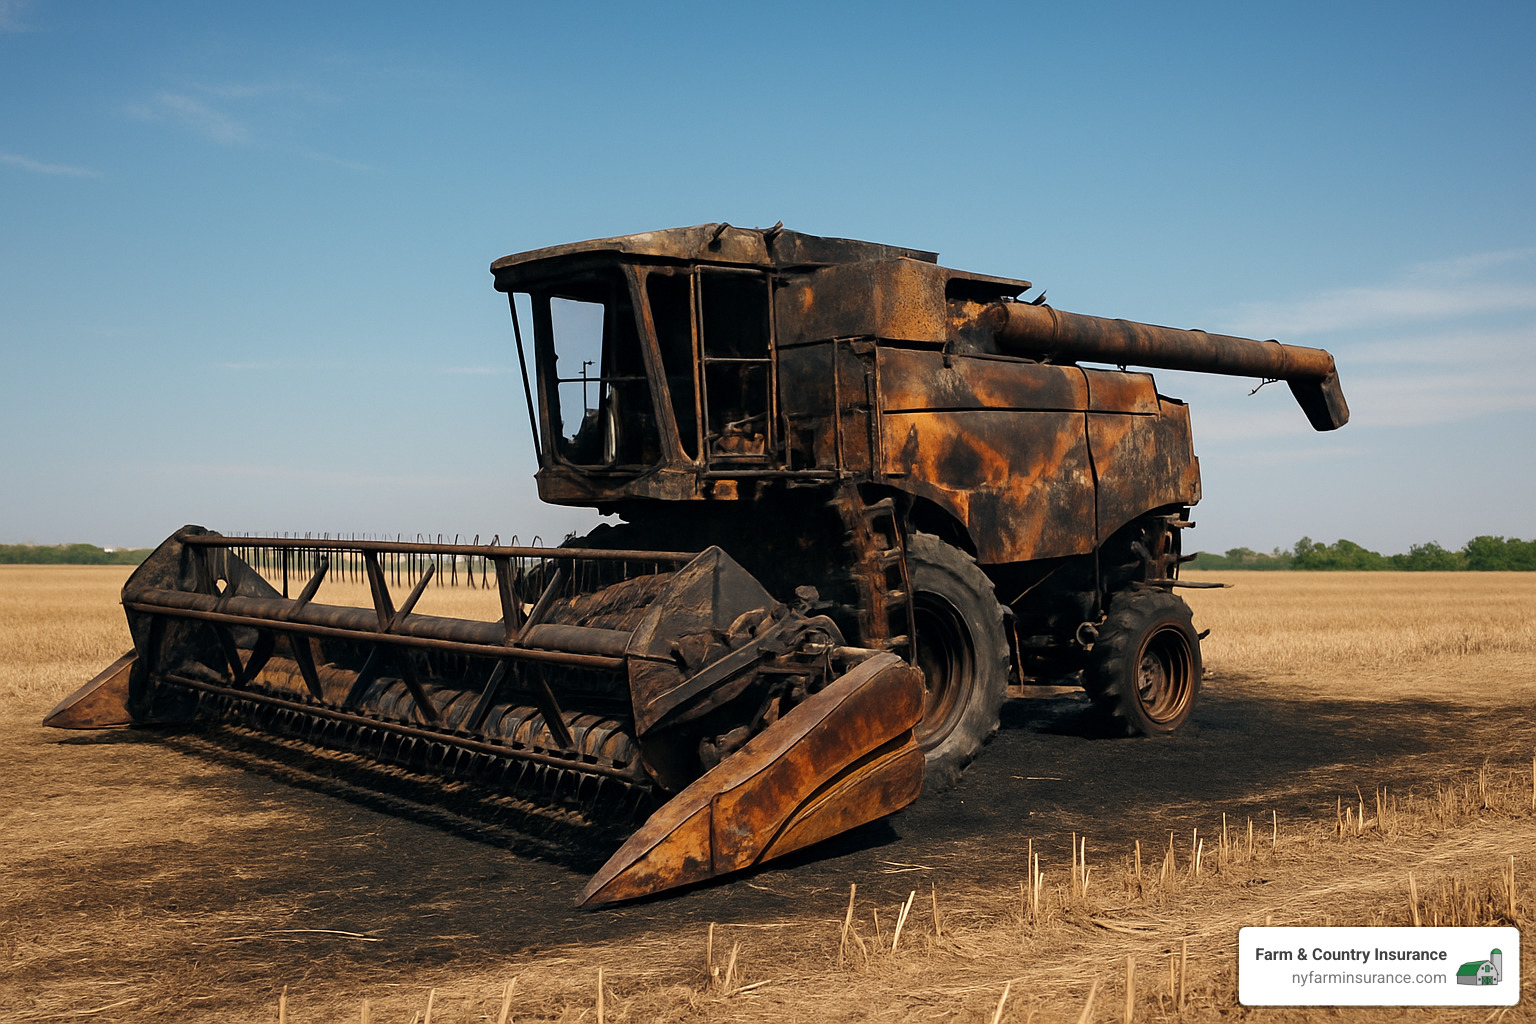
Fire represents one of the most devastating risks to farm equipment. With fuel tanks, hydraulic systems, and complex electrical components all operating in dusty, sometimes chaotic environments, the risk of ignition is ever-present. I’ll never forget when our client from Sennett watched helplessly as his $375,000 combine was engulfed in flames during corn harvest. Thanks to his comprehensive insurance, he had a replacement within weeks instead of facing financial devastation that might have ended his farming career.
Flood damage is increasingly common with our changing climate patterns. Several of our clients in Aurelius learned this harsh lesson in 2022 when unexpected heavy rains flooded their machine sheds near creek beds. Modern equipment with sensitive electronics and computerized systems can be completely ruined by water intrusion, turning a $200,000 tractor into an oversized paperweight overnight.
Wind & Hail events seem to be growing more severe each year. A hailstorm can shatter cab glass, dent exteriors, and damage delicate sensors and GPS equipment. What’s worse, these storms often hit during the growing season when equipment is out in the fields without shelter.
Overturn incidents happen even to the most careful operators. New York’s rolling hills and sometimes challenging terrain create natural rollover risks. One moment of misjudgment on a slope can put a tractor or sprayer on its side, resulting in tens of thousands in damage even with modern rollover protection systems.
Theft & Vandalism might surprise some, but farm equipment theft is alarmingly common. Consider this: American farmers invest approximately $13.7 billion annually in tractors and self-propelled machinery. With that kind of value in the field, thieves have taken notice. Nearly 1,500 tractors are reported stolen each year across the country, with a dismal recovery rate of only 16%. Without insurance, that stolen equipment represents a devastating financial blow.
The downtime costs following equipment damage or theft often exceed the value of the machine itself. During critical planting or harvest windows, every day counts. As one of our clients from Moravia explained after his sprayer was damaged by hail: “I wasn’t just looking at repair costs. I was facing a two-week delay during prime application time. The loss of use coverage in my policy helped rent replacement equipment and saved my crop.”
The reality is stark: farming operations depend on functioning equipment to maintain productivity and profitability. Latest research on farm equipment losses shows that uninsured equipment losses are among the top reasons for farm business failures.
At Farm & Country Insurance, we’ve seen how proper agricultural equipment insurance has saved family farms that might otherwise have buckled under the financial strain of replacing vital machinery. The peace of mind that comes from knowing your equipment investments are protected allows you to focus on what you do best – farming.
Core Coverages in Agricultural Equipment Insurance
When you’re investing in the machinery that keeps your farm running, you need insurance that truly understands the unique needs of agricultural operations. Agricultural equipment insurance offers protection custom specifically to farmers, with several core coverage options that can be customized to fit your operation.
Covered Equipment Types
Your farm relies on a diverse fleet of machinery, and a good agricultural equipment insurance policy covers them all. From your workhorse tractors to the high-tech GPS systems guiding them, comprehensive coverage protects your investments.
Modern policies typically cover tractors of all sizes, combines with their headers and attachments, self-propelled and pull-behind sprayers, irrigation equipment like center pivots and pumps, and even the precision farming technology that’s become essential to today’s operations. Equipment trailers and portable structures are usually included too.
According to standard policy language, “Mobile agricultural machinery and equipment means mobile devices used in the everyday operation of the farm including accessories, tools and spare parts.”
Many of our clients at Farm & Country Insurance are surprised to learn their coverage can extend beyond the obvious large machinery to include items like horse tack, portable livestock equipment, farm office equipment, tools, and even portable structures. This comprehensive approach ensures your operation stays protected across the board.
Blanket vs. Scheduled Agricultural Equipment Insurance
When setting up your agricultural equipment insurance, you’ll face an important decision: blanket coverage, scheduled coverage, or a hybrid approach. Each has distinct advantages for different farming operations.
Blanket coverage offers wonderful simplicity – all your equipment falls under a single coverage limit. This means new equipment is automatically covered (within limits), and you don’t need to update your policy with every equipment change. The potential downside? Most blanket policies include coinsurance requirements, typically around 80%, meaning you must insure to at least 80% of your equipment’s total value.
With scheduled coverage, each piece of equipment is individually listed with its own assigned value. This creates perfect clarity about what’s covered and for how much. You’ll receive the full insured value (minus your deductible) without worrying about coinsurance penalties. The trade-off is needing to update your policy whenever your equipment lineup changes.
Many farmers find the sweet spot with a hybrid approach. As one Farm & Country Insurance client from Owasco explains: “We schedule our high-value combines and tractors separately, but keep all our tillage equipment under a blanket policy. This gives us maximum protection where we need it most, while keeping the policy manageable.”
Fortunately, most policies include a “newly acquired machinery extension” that provides temporary coverage (typically 30 days) for new equipment purchases up to a specified limit (often $100,000). This gives you breathing room to officially add new equipment to your policy.
Optional Coverages in Agricultural Equipment Insurance
Beyond standard protections, several valuable optional coverages can significantly improve your agricultural equipment insurance:
Equipment Breakdown coverage protects against mechanical and electrical failures not caused by normal wear and tear – particularly valuable for newer equipment with complex electronics and emission systems that can be costly to repair.
Foreign-Object Ingestion protection is a lifesaver when equipment picks up unexpected items. A farmer in Fleming shared his experience: “When my combine picked up a piece of metal that had fallen off a truck, it caused $22,000 in damage to the rotor. This optional coverage saved me from a significant out-of-pocket expense.”
Rented/Borrowed Equipment coverage provides protection for machinery you temporarily use from others. Many policies automatically include up to $10,000 in coverage for borrowed equipment, with options to increase this limit if needed.
For machinery up to eight years old, Replacement Cost Coverage pays the full replacement cost without depreciation – an increasingly important option as equipment values continue to climb.
During critical planting or harvest windows, Loss of Use coverage can be invaluable, covering rental costs for substitute equipment while yours is being repaired after a covered loss.
Some policies even offer special Cab Glass Coverage with reduced or no deductible, recognizing that this is a common and relatively minor claim that shouldn’t penalize farmers with full deductible charges.
For more information about these and other valuable coverage add-ons, visit our detailed guide at More info about coverage add-ons.
Valuing & Listing Your Machinery Correctly
Proper valuation is perhaps the most critical aspect of agricultural equipment insurance. Underinsuring your equipment can leave you with significant out-of-pocket expenses after a loss, while overinsuring means paying unnecessary premium.
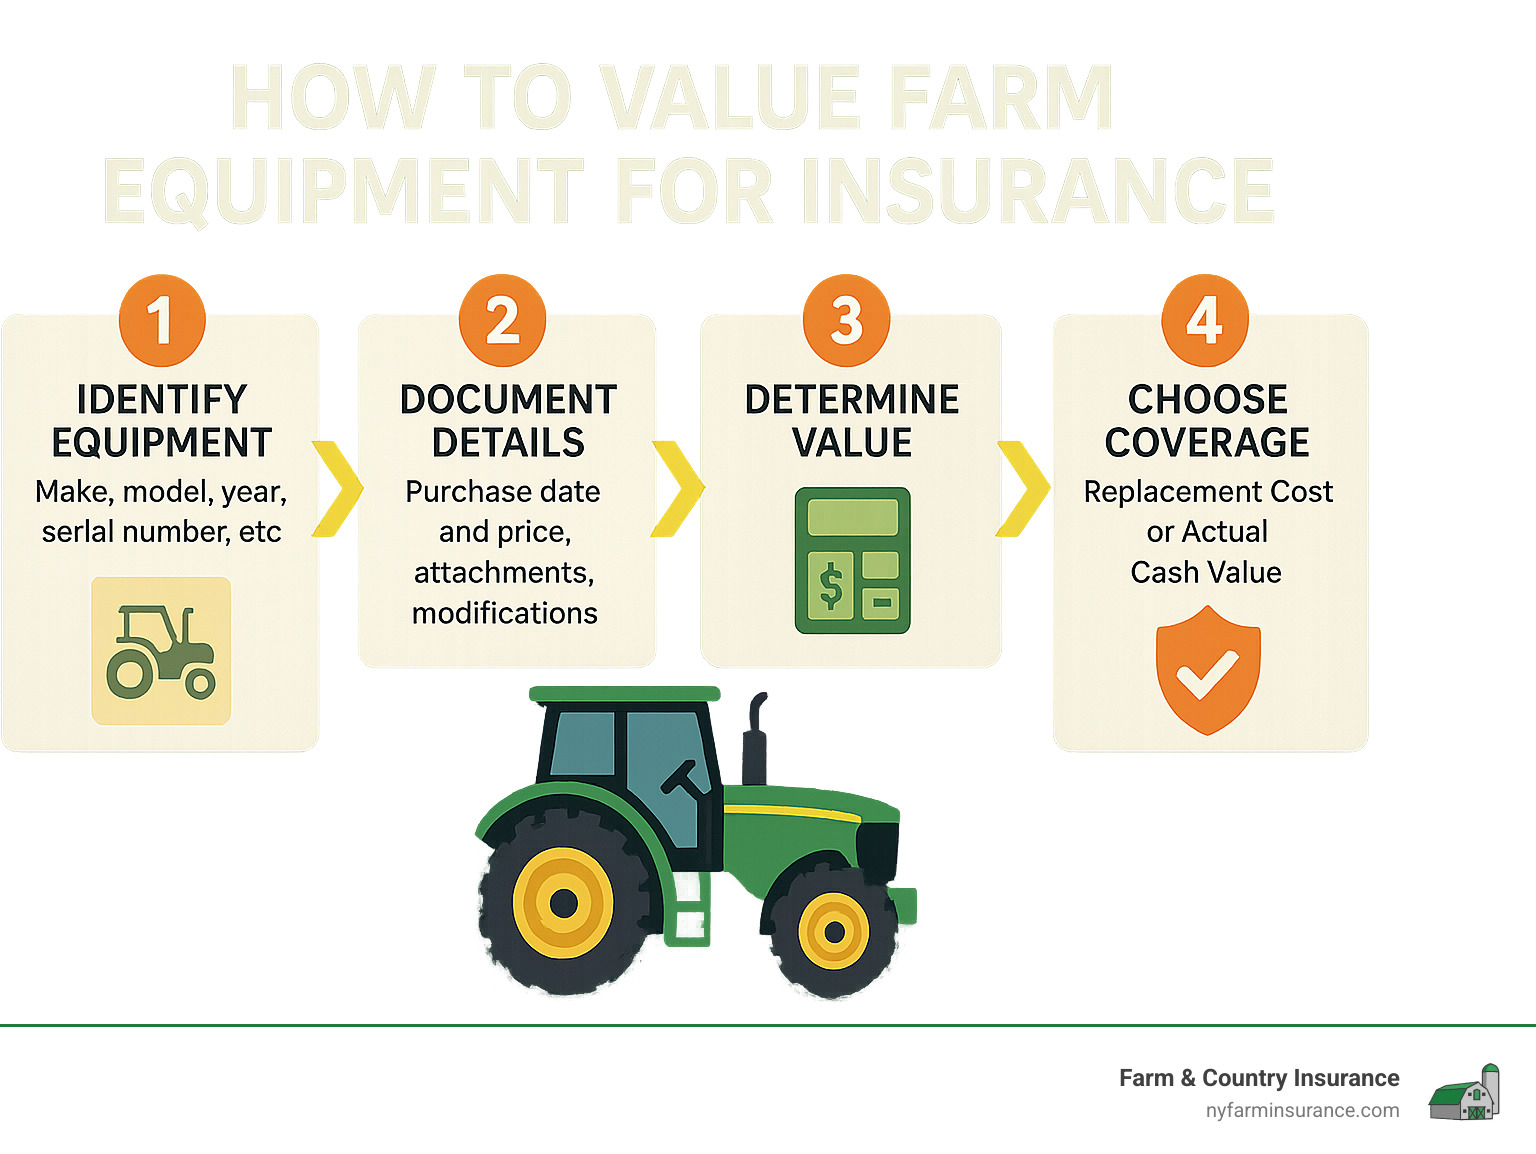
The first step is creating a comprehensive inventory of all your farm equipment. For each piece, you should document:
- Make, model, and year
- Serial number
- Purchase date and price
- Current replacement cost
- Attachments and modifications
- Special features or technology packages
When it comes to valuation, you’ll typically choose between:
Replacement Cost (RC): Pays the cost to replace the equipment with new equipment of like kind and quality, without deduction for depreciation. This is generally available for equipment up to eight years old.
Actual Cash Value (ACV): Pays replacement cost minus depreciation based on age and condition. This is typically used for older equipment.
One of our Farm & Country Insurance clients in Genoa shared this insight: “I was surprised to learn that my five-year-old tractor would cost 30% more to replace today than what I paid for it. Having my agent help me properly value my equipment for replacement cost made all the difference when I had a claim.”
Documentation Essentials
Proper documentation is crucial for both securing the right coverage and ensuring smooth claims processing. Here are the essential documents to maintain:
Purchase Invoices: Keep original purchase documents showing date, price, and specifications.
Photos: Take detailed photos of equipment from multiple angles, updated annually. Include close-ups of serial numbers and any custom features.
Maintenance Logs: Document all maintenance and repairs, which can help establish the condition of the equipment in the event of a claim.
UCC Filings: If equipment is financed, keep copies of UCC filings and loan documentation, as lenders typically have requirements for insurance.
Depreciation Schedules: Tax depreciation schedules can help establish value and ownership.
A Farm & Country Insurance client from Scipio told us: “After a fire destroyed our machine shed and the equipment inside, having detailed inventory records and photos made the claims process much smoother. We received our settlement within three weeks because we could clearly document what we lost.”
Premium Pricing & Ways to Save
What determines the cost of your agricultural equipment insurance? It’s a question we hear often at Farm & Country Insurance, and understanding these factors can help you find meaningful savings without cutting corners on protection.
The price tag on your policy is influenced by several key elements. First and foremost is your equipment value – this drives the bulk of your premium cost. For perspective, a $1,500,000 blanket equipment policy typically costs around $4,600 annually, which breaks down to approximately $3.06 per $1,000 of coverage.
Your farm’s location crime score matters too. Different regions of New York have varying risk profiles for equipment theft, with some areas commanding significantly higher premiums than others. Similarly, your storage practices play a crucial role – equipment tucked away in secure buildings generally qualifies for better rates than machinery left in open fields or unsecured locations.
How intensively you use your equipment affects your premium as well. Usage hours matter to insurers, with seasonally-used equipment often qualifying for lower rates compared to machinery that’s working year-round. And don’t overlook your deductible choice – bumping up from a $500 to a $2,500 deductible could trim your premium by 15-20%.
“When I increased my deductible and installed security lighting around my equipment barn, my premium dropped by almost $700 a year,” shares one of our clients from Aurelius. “The lighting cost me about $400 to install, so I came out ahead in the first year alone.”
There are several practical ways to bring down your insurance costs without compromising coverage:
Safety devices make a difference – GPS tracking systems, immobilizers, and other anti-theft devices not only protect your equipment but can earn you discounts. Secure storage is another straightforward approach; simply storing equipment in locked buildings when not in use can lower your rates.
Many insurers, including Farm & Country Insurance, offer telematics discounts for equipment with systems that monitor usage and maintenance. Package policies are worth exploring too – combining your equipment coverage with other farm insurance can open up multi-policy discounts.
Implementing and documenting risk management protocols and maintenance schedules demonstrates responsibility to insurers, potentially lowering your premiums. And don’t forget the importance of an annual review – regularly revisiting your coverage ensures you’re not paying to insure equipment you no longer own.
Some of the most cost-effective risk control upgrades include:
- Security lighting around equipment storage ($200-500)
- Trail cameras at farm entrances ($50-150 each)
- Equipment identification etching ($25-100 per machine)
- Fuel lockouts ($75-200 per machine)
- Master electrical disconnects ($100-300 per machine)
A longtime Farm & Country Insurance client from Cato put it best: “Farming margins are too tight to overpay for insurance. By installing GPS trackers on our high-value equipment and improving our storage security, we reduced our insurance premium by nearly 12%. The investment paid for itself in the first year.”
The cheapest policy isn’t always the best value. Working with an agent who understands agricultural operations can help identify the right balance between premium savings and proper protection for your operation’s specific needs.
Filing a Claim: Step-by-Step Guide
When disaster strikes your farm equipment, knowing exactly how to steer the claims process can make all the difference between a quick recovery and weeks of frustration. At Farm & Country Insurance, we’ve guided hundreds of New York farmers through this process, and we’ve learned what works.
The First 24 Hours Matter Most
When something happens to your equipment, don’t wait. Contact your insurance provider immediately after finding damage or theft. Most policies specifically require “prompt notice,” and delays can give insurers reason to question your claim. At Farm & Country Insurance, we maintain a 24/7 claims hotline specifically for agricultural equipment emergencies because we understand that equipment failures don’t always happen during business hours.
For theft situations, file a police report right away. Your insurer will require this documentation, but more importantly, providing authorities with detailed information (serial numbers, unique features, and recent photos) significantly improves your chances of recovery.
“When my Kubota disappeared from our field overnight, I called both Farm & Country Insurance and the sheriff within the hour,” recalls a client from Fleming. “The equipment was recovered three days later in a neighboring county, largely because I had documentation ready for the authorities immediately.”
Document Everything
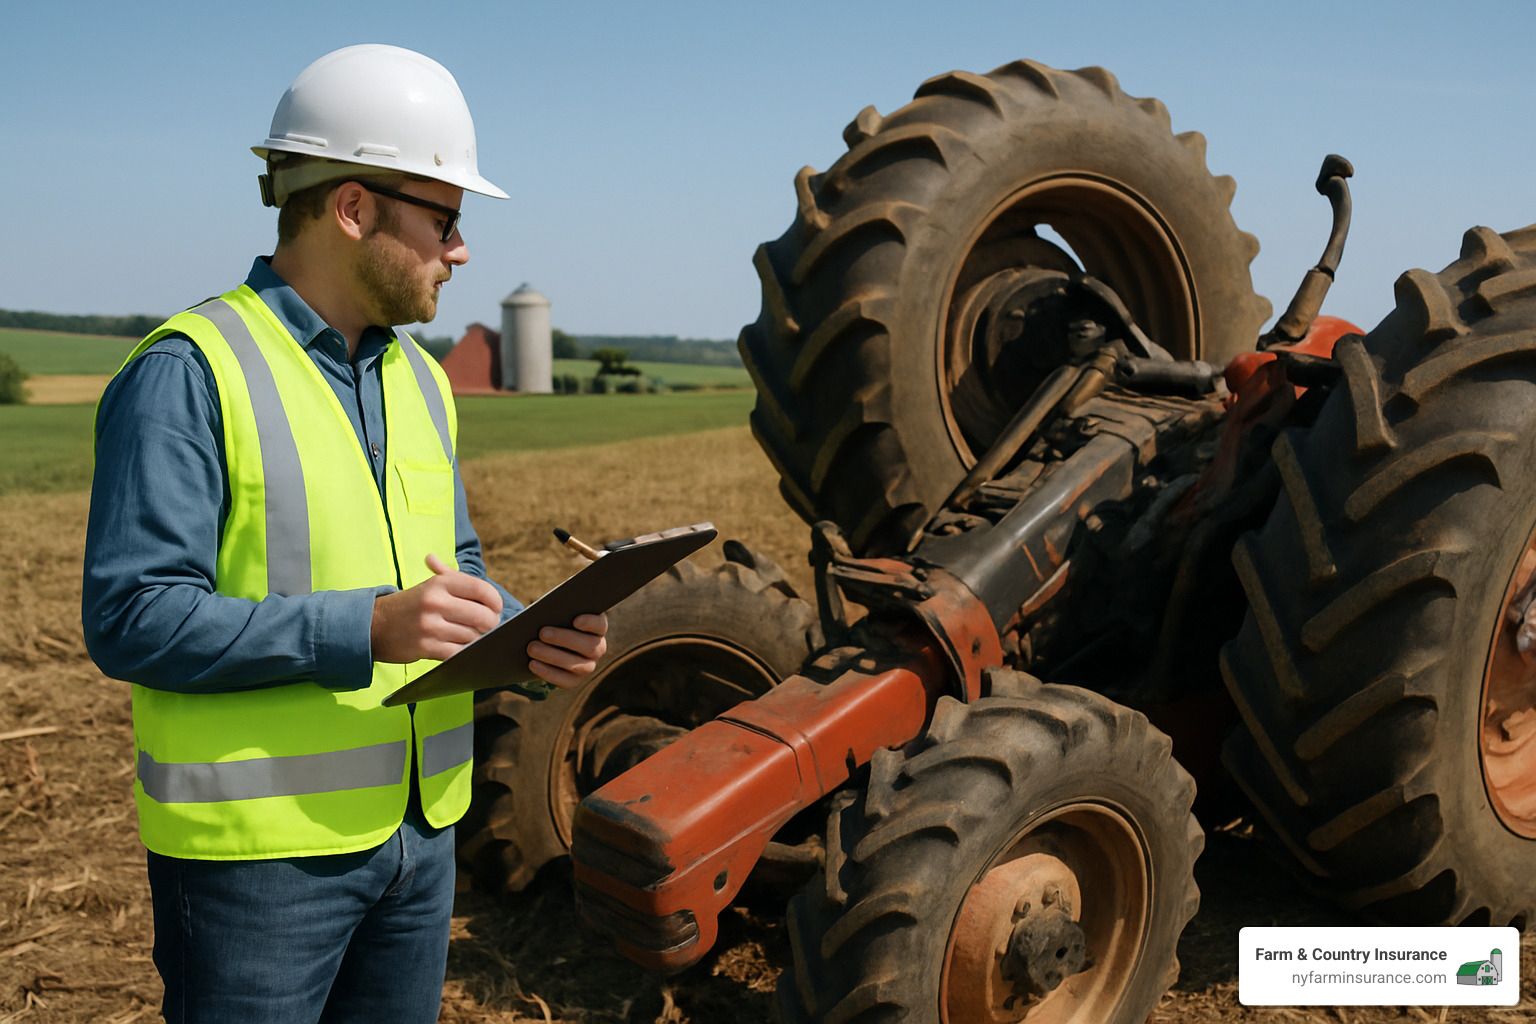
Before moving anything, grab your phone and take extensive photos of the damage. Capture wide shots showing the entire scene and close-ups highlighting specific damage points. These images often become crucial evidence during the claims process.
One grain farmer from Aurelius told us: “When lightning struck our grain auger, I took about 30 photos from every angle before anyone touched it. The adjuster later told me those pictures cut at least a week off our claim processing time because they answered so many of his questions upfront.”
The Adjuster Visit
An insurance adjuster will inspect significant damage, typically within 24-72 hours for major losses. If possible, be present during this inspection to answer questions about the equipment’s maintenance history and circumstances of the loss. Your knowledge often helps clarify details that might otherwise slow down your claim.
Getting Repair Estimates
Your insurer will likely require at least one repair estimate from a qualified equipment dealer or repair shop. For complex or expensive repairs exceeding $10,000, they might request multiple quotes. Having established relationships with reputable equipment dealers in central New York means Farm & Country Insurance clients often receive priority service when seeking these estimates.
Salvage Decisions
If your equipment is deemed a total loss, you’ll need to discuss salvage options with your adjuster. Sometimes, keeping the damaged equipment for parts makes sense (with its salvage value deducted from your claim payment). Other times, it’s better to let the insurance company handle disposal. This is a conversation worth having, especially for specialized equipment with valuable components.
Payment Timeline and Getting Back to Work
Most straightforward equipment claims settle within 2-4 weeks. More complex situations involving multiple pieces or special-order parts from overseas might take longer. At Farm & Country Insurance, we pride ourselves on our average 18-day payment timeline for equipment claims – significantly faster than the industry average.
“When our sprayer overturned on a hillside last spring, I was panicking about missing our narrow application window,” shares a vegetable farmer from Ira. “The Farm & Country claims team not only processed our claim quickly but arranged for a rental sprayer within 48 hours while repairs were being completed. That kind of understanding of farming timelines saved our crop.”
The claims process is exactly why you’ve been paying premiums all these years. Don’t hesitate to ask questions, request updates, or seek clarification at any point. A good agricultural insurance provider understands that your livelihood depends on getting your equipment back in operation as quickly as possible.
New York Considerations & Choosing a Provider
Farming in New York comes with its own unique set of challenges and opportunities that directly impact your agricultural equipment insurance needs. From the apple orchards of Western New York to the dairy farms of the North Country, each operation faces distinct risks.
State Road-Use Laws: New York has specific regulations about farm equipment on public roads that can affect your coverage needs. If you’re like most New York farmers who manage multiple parcels separated by public roadways, you’ll need insurance that specifically addresses equipment transport between locations.
“I never thought twice about driving my tractor between fields until I learned about the liability gap in my policy,” shares a Farm & Country Insurance client from Seneca County. “Having coverage specifically designed for New York road regulations gave me peace of mind.”
Lender Requirements: If you’ve financed your equipment, your lender will have specific insurance requirements. Farm & Country Insurance has established relationships with all major agricultural lenders across New York, ensuring your policy satisfies their requirements while still providing the protection you actually need.
Umbrella Coordination: Let’s face it – New York can be a litigious environment. Coordinating your equipment policy with an umbrella liability policy becomes increasingly important as your operation grows. This coordination ensures there are no coverage gaps that could leave you exposed after an incident.
Seasonal Considerations: Our diverse New York growing seasons mean your equipment usage patterns likely change throughout the year. Your insurance should reflect these seasonal realities, from spring planting equipment to fall harvest machinery.
Regulatory Checkpoints for New York Operators
New York farmers steer a complex regulatory landscape that directly intersects with agricultural equipment insurance:
DMV Registration Triggers: While farm tractors are generally exempt from DMV registration, self-propelled equipment like sprayers might require registration when used on public roads. This registration status directly impacts your insurance requirements and coverage options.
Workers’ Comp Links: If employees operate your equipment, New York law requires workers’ compensation coverage. Your equipment policy should coordinate seamlessly with your workers’ comp to ensure complete protection for both your assets and your team.
Environmental Rules: New York maintains strict environmental regulations regarding fluid spills from damaged equipment. Standard policies might not fully cover cleanup costs if hydraulic fluid or fuel leaks into soil or waterways after an accident. Additional pollution liability coverage might be necessary to fully protect your operation.
A multi-generation farmer from Cayuga County told us: “After we had a hydraulic line break near a creek, we realized how vulnerable we were to environmental liability claims. Adjusting our coverage to address this specific risk was one of the smartest decisions we made.”
Provider Comparison Checklist
When selecting an insurance provider for your farm equipment, consider these essential factors:
Financial Strength: Choose an insurer with robust financial ratings that can weather widespread disaster events. The last thing you need is an insurance company that can’t pay claims after a regional catastrophe affects multiple farms.
Claims Service: Look for insurers with dedicated agricultural claims specialists who understand the difference between a combine and a chopper. General adjusters often lack the specialized knowledge needed to properly assess farm equipment damage.
Agribusiness Specialization: A company that primarily insures homes and autos may not understand the seasonal urgency of agricultural claims. Seek providers with specific farm expertise who understand that a broken combine during harvest isn’t just an inconvenience—it’s an emergency.
Local Risk Control: Providers with a local presence can offer practical, on-farm risk assessments custom to your specific operation and the unique weather patterns of your region in New York.
Coverage Flexibility: Farming operations evolve constantly. Your insurer should offer coverage options that can grow and adapt with your changing equipment needs without requiring a complete policy overhaul.
Policy Integration: Your equipment coverage should work in harmony with your other farm policies, creating a comprehensive protection plan rather than a patchwork of conflicting coverages.
“After twenty years of farming, I’ve learned that not all insurance is created equal,” explains a Farm & Country Insurance client from Ontario County. “Finding an agent who actually visits my farm, understands my operation, and tailors coverage to my specific needs made all the difference when we had a claim last harvest.”
Since 1984, Farm & Country Insurance has specialized in protecting New York farms with insurance solutions that reflect the realities of agriculture in our state. More info about farm business insurance is available for those looking to ensure their entire operation is properly protected.
Frequently Asked Questions about Agricultural Equipment Insurance
Do I really need coverage for older, lower-value implements?
Yes, even older equipment deserves consideration for agricultural equipment insurance. While the equipment itself may have depreciated, its functionality remains valuable to your operation.
The reality is that replacement costs have likely increased significantly, even for older models. Parts availability for older equipment is often limited too, which can dramatically increase repair costs when something breaks. Perhaps most importantly, the downtime from uninsured equipment can impact your operations far beyond the equipment’s actual value.
A Farm & Country Insurance client from Locke put it perfectly: “I debated dropping coverage on my 15-year-old disk harrow, thinking its $12,000 value wasn’t worth the premium. Then a fire in my equipment shed damaged it beyond repair. Finding a replacement during spring tillage would have been impossible without insurance covering the unexpected $22,000 replacement cost.”
For those lower-value items that still keep your farm running, consider a blanket policy with a higher deductible. This approach keeps premiums manageable while maintaining protection against major losses that could derail your operation at critical times.
How is newly purchased equipment protected before I update my policy?
Most agricultural equipment insurance policies include automatic coverage for newly acquired equipment, typically for 30 days after purchase. This temporary coverage gives you breathing room to formally add the equipment to your policy without worrying about gaps in protection.
However, this automatic coverage does come with important limitations. It’s usually temporary (often just 30 days), and there’s typically a maximum dollar limit (commonly $75,000-$100,000). The equipment must generally be similar to what you already have insured, and you must notify your agent or insurer as soon as practical.
“When I purchased a new planter mid-season, I was relieved to learn it was automatically covered under my existing policy’s newly acquired equipment provision,” explained a Farm & Country Insurance client from Mentz. “This gave me peace of mind until I could formally add it to my policy after the planting season.”
The best practice is simple: contact your agent either before or immediately after major equipment purchases. This small step ensures you have proper coverage from day one and prevents any surprises if something happens during that initial period.
Will my policy follow the machine if I lend it to a neighbor?
This question comes up constantly when discussing agricultural equipment insurance, especially in farming communities where neighborly equipment sharing is common practice. The answer depends on your specific policy, but most policies do provide some coverage when equipment is temporarily used by others.
In most cases, coverage follows the equipment rather than the operator. The borrower must have your permission to use the equipment, and it should be used for similar agricultural purposes as you would use it. Some policies may limit coverage for borrowed equipment to a specific radius from your farm.
However, there are potential limitations to be aware of. If your neighbor is using the equipment commercially (for hire), coverage may be excluded. Damage resulting from improper use or gross negligence might not be covered either. And perhaps most importantly, liability coverage may not extend to the borrower’s operation.
“I regularly exchange equipment with neighboring farms during harvest,” said a Farm & Country Insurance client from Montezuma. “We made sure each of our policies had the proper endorsements to cover equipment while in someone else’s care, which has made these arrangements much less stressful.”
For those regular equipment sharing arrangements that make farming communities work, consider creating a formal written agreement and confirm coverage details with your agent. This small bit of preparation can save relationships and equipment when the unexpected happens.
Conclusion
As the sun sets over your fields, your equipment sits ready for tomorrow’s challenges. That machinery represents not just a significant investment, but the very heartbeat of your operation. Agricultural equipment insurance isn’t just another line item in your farm budget—it’s the safety net that keeps your operation running when the unexpected strikes.
I’ve spent years watching New York farmers face everything from sudden hailstorms to equipment fires to theft. The difference between those who bounced back quickly and those who struggled often came down to one thing: proper insurance coverage.
At Farm & Country Insurance, we’ve been walking alongside New York farmers since 1984. We’ve celebrated with families when their stolen tractor was recovered and insurance covered the damages. We’ve also comforted farmers who finded too late that their coverage had critical gaps.
“Insurance is like a parachute,” one of our clients from Scipio told me recently. “You hope you never need it, but when you do, you’re mighty glad it’s there—and that you didn’t go with the cheapest option.”
Your equipment deserves protection that’s as hardworking and reliable as you are. That means reviewing your coverage annually as equipment values and your operation change. Farm machinery has appreciated significantly in recent years, and yesterday’s coverage limits might leave you underprotected today.
Detailed documentation is your best friend when it comes to claims. Those equipment photos you take “just in case” become invaluable when you’re trying to prove what you lost. One client told me the 30 minutes he spent photographing his equipment and storing serial numbers saved him weeks of headaches after a fire.
Don’t overlook the value of optional coverages like replacement cost protection and loss of use. When your combine goes down during harvest, the ability to rent replacement equipment can save your entire crop—and your bottom line.
Smart farmers know that risk management goes beyond insurance. Simple security practices like removing keys, installing kill switches, and keeping equipment in well-lit areas not only reduce your premiums but also prevent losses in the first place.
Perhaps most importantly, partner with insurance specialists who understand farming. When you call with a claim about a PTO failure or foreign object damage, you shouldn’t have to explain basic farming concepts to your agent.
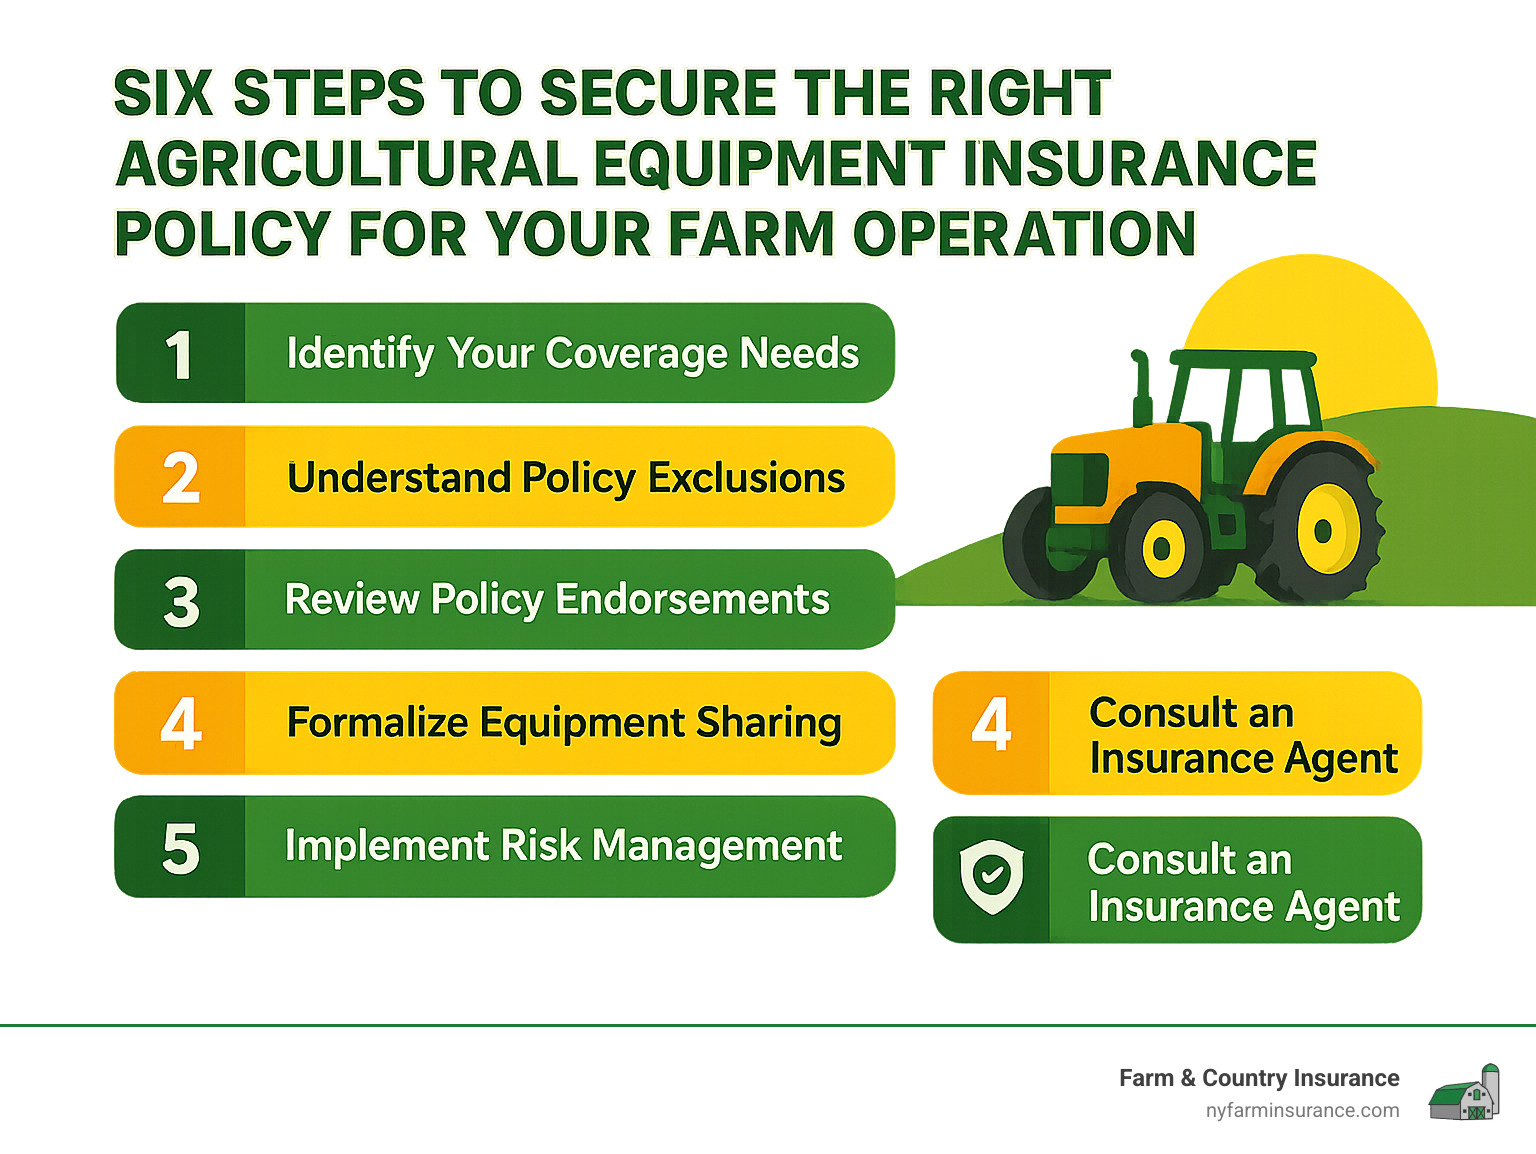
Farming has always been about managing what you can control while preparing for what you can’t. You can’t stop the hailstorm, but you can make sure you have the right agricultural equipment insurance in place before it hits.
As a fourth-generation farmer from Cayuga County told me, “My grandfather taught me that good farmers plan for bad weather. These days, good farmers also plan for equipment failures, accidents, and theft.”
For more information about protecting your farm equipment or to schedule a no-obligation coverage review, contact Farm & Country Insurance today. Our team understands New York agriculture and can help you develop protection that’s as unique as your operation. After all, we’ve been helping farms like yours since 1984, and we’d be honored to help yours too.