
Understanding the Shield for Your Farmland
Agricultural land insurance is a specialized risk management tool designed to protect farmers against financial losses due to damage or destruction of their agricultural land from various perils including drought, flood, wind, frost, excessive rain, heat, disease, and pest infestations.
What is Agricultural Land Insurance?
* Coverage for the land itself, separate from structures and equipment
* Protection against natural disasters, weather events, and environmental damage
* Risk transfer mechanism that provides financial stability for farmers
* Available through both government programs and private insurers
Agricultural land insurance differs from standard homeowners and farm insurance by specifically focusing on the productivity and value of the land itself, rather than just buildings and equipment. While farm and ranch insurance typically covers structures, machinery, livestock, and liability, agricultural land insurance addresses the unique risks to soil quality, productive capacity, and land value.
For farmers who depend on their land as their primary productive asset, having dedicated protection through agricultural land insurance provides critical financial security against unpredictable events that could otherwise devastate their operations and livelihood.
My name is Casey Love, owner of Farm & Country Insurance, and with over 15 years of experience specializing in agricultural land insurance across New York State, I’ve helped hundreds of farmers secure their most valuable asset – their land.

Know your agricultural land insurance terms:
– agricultural equipment insurance
– farm fire insurance
Understanding Agricultural Land Insurance
When we talk about agricultural land insurance, we’re not just discussing another policy – we’re talking about protecting the very soil that sustains farming operations. This specialized coverage safeguards the foundation of your farm – the land itself – in ways standard insurance simply doesn’t.

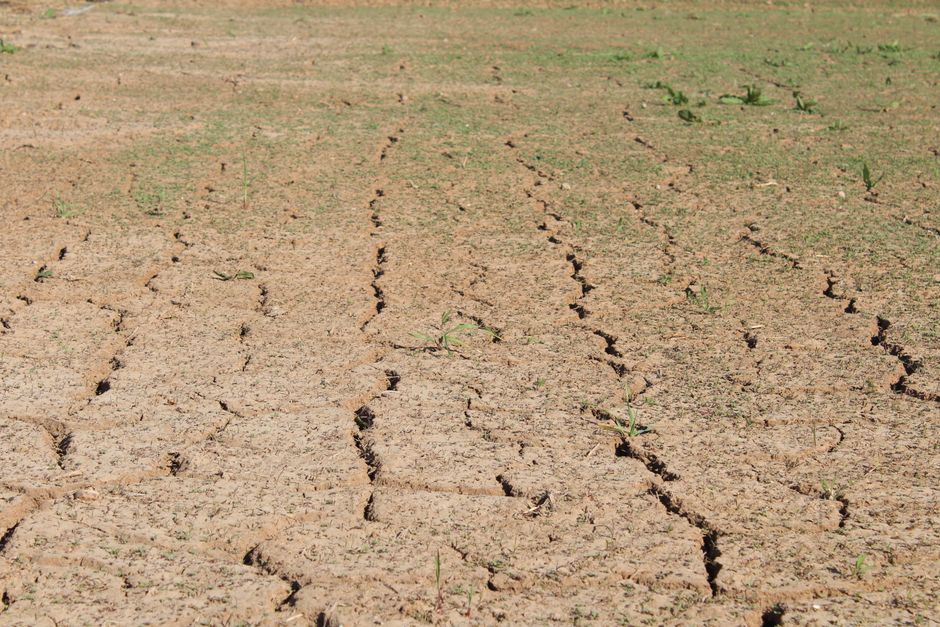
According to the USDA Risk Management Agency (RMA), agricultural land insurance provides affordable protection that reduces the financial blow when disaster strikes your fields. Here in New York state, where our farmers face everything from flash floods to late frosts, this protection isn’t just nice to have – it’s essential.
“Your land is your livelihood,” shares Jason Miller, a third-generation dairy farmer from Cayuga County. “When a flash flood washed away three acres of our topsoil last spring, our agricultural land insurance was the only thing that kept us from financial disaster. The coverage helped us restore the land to productive capacity within months.”
This unique insurance operates through a public-private partnership. In the United States, the Federal Crop Insurance Corporation provides the financial backbone and subsidies, while private companies like Farm & Country Insurance handle the policies. Our northern neighbors have a similar system called AgriInsurance, which shares costs between federal, provincial, and producer levels.
The Policy Types available cover a wide range of threats including drought, excessive moisture, freeze, hail, wind, wildlife damage, disease, insect problems, and fire – essentially, all the things that keep farmers up at night.
How Agricultural Land Insurance Differs From Homeowners & Farm/Ranch Policies
I can’t tell you how many times I’ve sat with farmers who believed their regular farm policy covered everything. The truth is, there’s a world of difference:
| Farm/Ranch Insurance | Agricultural Land Insurance |
|---|---|
| Covers buildings, equipment, livestock | Focuses on the land itself |
| Addresses liability for operations | Addresses productivity losses |
| Protects personal property | Protects soil quality and land value |
| May exclude farming operations | Specifically designed for agricultural use |
Standard homeowners policies explicitly exclude farming operations, and even basic farm insurance often misses land-specific risks.
“The biggest gap I see is farmers thinking their general liability covers land restoration,” explains Sarah Johnson, our risk management specialist at Farm & Country Insurance. “When a client’s irrigation pond dam failed and caused significant erosion damage to 15 acres of prime cropland, they were shocked to find their regular farm policy didn’t cover the $75,000 in land restoration costs. That’s when the value of dedicated agricultural land insurance becomes crystal clear.”
For complete protection, consider specialized coverage like Farm Liability Insurance alongside your land insurance to ensure nothing falls through the cracks.
Who Can Buy Agricultural Land Insurance?
Good news – eligibility for agricultural land insurance is broader than many realize. Active farmers and ranchers naturally qualify, but so do absentee landowners who lease their land, beginning farmers, agricultural cooperatives, and ag businesses with land holdings.
The USDA has worked hard to make these programs accessible, especially for new farmers. Special programs help beginning farmers qualify for agricultural assessment right from year one, with provisions to help them meet income requirements as they grow.
At Farm & Country Insurance, we’ve guided countless new farmers through these specialized programs. The Beginning Farmer and Rancher benefits can be a game-changer, offering additional premium subsidies and fee waivers during those make-or-break early years.
When underwriting your policy, insurers typically look at your soil quality, productivity history, flood risk, topography, previous claims, and conservation practices. The more information you can provide, the better your coverage options will be.
Government Agencies & Their Role
Several government agencies work behind the scenes to make agricultural insurance possible:
The USDA Risk Management Agency (RMA) oversees the Federal Crop Insurance Program, developing premium rates and new insurance products. They’re the architects of the system that protects American farmers.
The Federal Crop Insurance Corporation (FCIC), born during the Dust Bowl era in 1938, provides the financial backing that makes these programs stable and reliable.
Agriculture and Agri-Food Canada runs a similar program for our Canadian neighbors, with provinces handling the local delivery.
These agencies provide critical support through premium subsidies (sometimes covering up to 65% of the cost), reinsurance arrangements, development of innovative insurance products, technical assistance, and comprehensive data collection.
“The public-private partnership model has proven remarkably effective,” notes Tom Williams, agricultural economist. “Federal crop insurance is available in every state, with more than 1.1 million policies providing over $150 billion in protection for American farmers annually.”
For detailed information on specific programs and subsidies available to New York farmers, check out the Insurance Fact Sheets from the RMA, or better yet, give us a call at Farm & Country Insurance. We speak farmer, and we know these programs inside and out.
Main Types of Agricultural Insurance Policies
When considering agricultural land insurance, farmers should understand the range of policy types available to protect their operations. These policies work together to create a comprehensive risk management strategy.

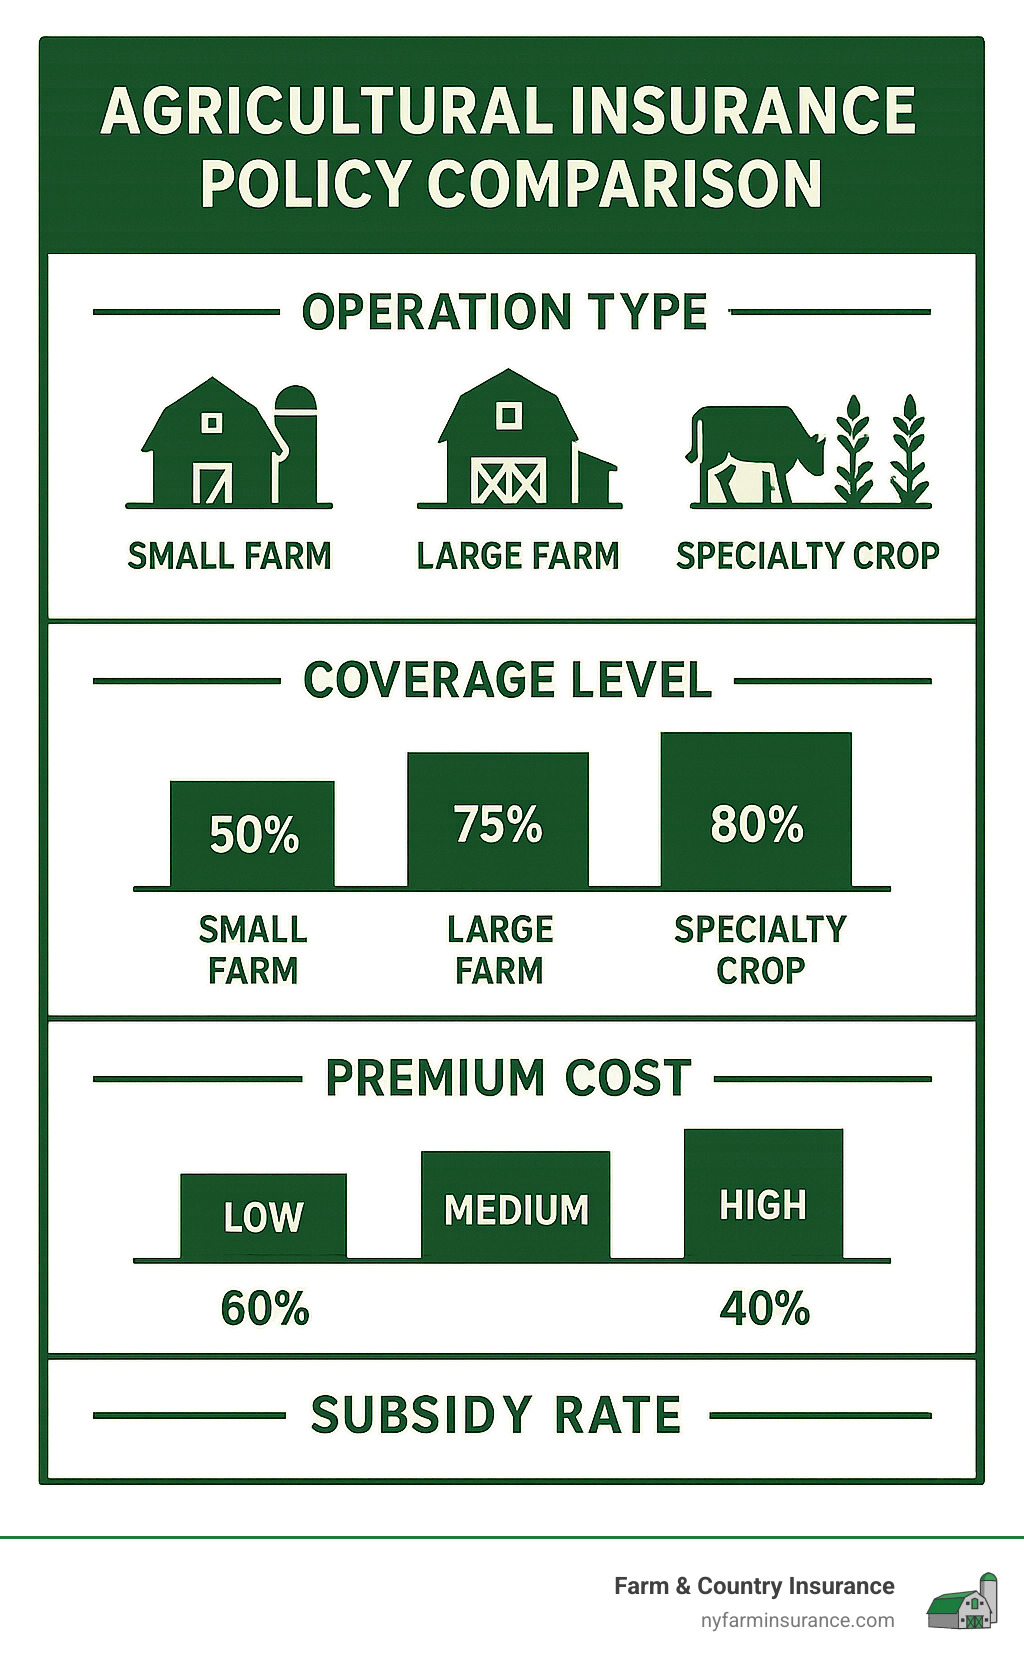
Crop Insurance Essentials
Crop insurance forms the foundation of many agricultural insurance portfolios. Think of it as your farm’s financial safety net when Mother Nature doesn’t cooperate.
“I remember when hail destroyed half of Jim’s corn crop last summer,” says Sarah Thompson, an agent at Farm & Country Insurance. “His Yield Protection policy made the difference between a tough year and a catastrophic one.”
Yield Protection (YP) covers you when natural disasters reduce your harvest below your guaranteed level. It’s straightforward – if your yield drops, you receive payment based on the shortfall.
Revenue Protection (RP) takes things a step further by guarding against both poor yields and falling prices. This popular option has saved countless New York farms during volatile market years.
Area Risk Protection Insurance (ARPI) works differently, using county-level data rather than your individual farm’s numbers. It’s often more affordable but less customized to your specific operation.
For New York farmers, timing is everything. Miss the March 15th deadline for spring crops, July 15th for certain forage crops, or November 20th for fall-planted crops, and you’ll have to wait until next year for coverage. I’ve seen too many farmers learn this lesson the hard way.
Livestock & Pasture Programs
If you raise animals, your insurance needs are different from crop-only operations.
“My dairy clients sleep better knowing they’re protected against both feed cost spikes and milk price crashes,” explains Mike Johnson of Farm & Country Insurance. “The right combination of livestock policies makes this possible.”
Livestock Risk Protection (LRP) works like an insurance policy against market price declines for cattle, lamb, and swine. When prices fall below your guaranteed level, you receive compensation regardless of what happens on your farm.
Livestock Gross Margin (LGM) offers a slightly different approach by protecting the difference between feed costs and market value – your gross margin. For dairy farmers across Central New York, this can be particularly valuable.
Pasture, Rangeland, and Forage (PRF) insurance is a bit different. Using a rainfall index, it compensates you when precipitation falls below normal levels, affecting your grazing land or hay production. You can learn more about how these fit with other coverage types through our Livestock Policies resource.
These specialized programs work alongside traditional Agricultural Business Insurance to create a comprehensive safety net for livestock producers.
Whole-Farm & Specialty Coverage
Modern farms often don’t fit neatly into traditional categories, which is why specialty policies have become increasingly important.
Whole-Farm Revenue Protection (WFRP) is perfect for diversified operations. Instead of insuring each crop separately, it covers your entire farm revenue under one policy. This simplifies paperwork and often provides better protection for farms growing multiple crops.
“When the Rodriguez family transitioned their 80 acres to a mix of vegetables, flowers, and berries for their CSA program, traditional crop insurance wasn’t the right fit,” shares Tom Wilson from Farm & Country Insurance. “WFRP gave them the flexibility they needed during this risky transition.”
Micro Farm coverage specifically serves small operations with up to $100,000 in revenue. It’s tailor-made for the growing number of direct-market farms across New York state.
Organic Crop Insurance recognizes the unique challenges and price premiums of certified organic production. These modified policies account for the different economics of organic farming.
Specialty producers haven’t been forgotten either. Nursery Value Select protects plants and trees against weather damage, while in Canada, AgriInsurance even extends to maple syrup production – vital for many northern New York producers.
The key is finding the right mix of policies for your specific operation. At Farm & Country Insurance, we’ve been helping New York farmers steer these choices since 1984, ensuring they have the protection that matches their unique needs.
Agricultural Land Insurance Costs & Subsidies
When farmers ask me about agricultural land insurance costs, I always tell them it’s like buying a custom suit – the price varies widely based on your specific measurements. Understanding what goes into premium calculations and available subsidies can help you find coverage that fits both your needs and budget.
How Premiums Are Calculated
Behind every agricultural land insurance premium is a careful analysis of your farm’s unique risk profile. Insurance companies examine several key factors:
Your soil quality matters tremendously – farms blessed with rich, productive soils typically enjoy lower premiums because they’re less likely to experience devastating yield losses. Similarly, your production history speaks volumes; farms with consistently strong yields demonstrate lower risk and often qualify for better rates.
“Last year, I worked with two neighboring farms in Seneca County,” shares Robert Johnson, senior agent at Farm & Country Insurance. “Despite being just a mile apart, their premiums differed by nearly 30% because one had implemented drainage improvements and had a stellar 10-year yield history, while the other struggled with inconsistent production.”
Your location plays a crucial role too. Farms in flood-prone areas or regions susceptible to drought face higher premiums reflecting these geographical risks. The coverage level you select – whether you’re protecting 65%, 75%, or 85% of your expected yield – directly impacts your premium costs. Higher protection equals higher premiums.
How you organize your insurable acreage (your “unit structure”) can significantly affect costs. Many of our clients at Farm & Country Insurance save substantially by switching from basic units to enterprise units, which combine all acreage of a single crop within a county.
For a practical sense of potential costs, we regularly use the USDA’s Cost Estimator tool with farmers. A typical 500-acre corn operation in Central New York might see premiums ranging from $20-45 per acre depending on these various factors.
Financial Assistance & Discounts
The good news? You’re not shouldering these costs alone. Substantial support exists to make agricultural land insurance more affordable:
The federal government provides impressive premium subsidies ranging from 38% to 67%, with higher subsidy percentages typically applying to lower coverage levels. This means the government might pay well over half your premium costs.
Beginning farmers receive extra help through the USDA’s Beginning Farmer and Rancher benefits. I’ve seen new farmers save thousands through waived administrative fees and additional premium support during those critical early years when every dollar counts.
Canadian farmers experience a different but equally supportive system. Under AgriInsurance, premium costs are shared between producers (typically 40%), provincial governments, and the federal government – creating a true partnership approach to agricultural risk management.
At Farm & Country Insurance, we work with carriers offering meaningful discounts for smart farming practices. “One dairy farmer in Owasco cut his premium by 12% after showing us documentation of his cover crop program and improved drainage system,” notes Sarah Miller, one of our senior agents. “These practices not only improved his soil health but made him a better insurance risk.”
Many farmers find additional protection through comprehensive Farm Policy Insurance options that complement their primary coverage and create multiple layers of financial security.
While premium costs matter, the right agricultural land insurance provides something priceless: peace of mind knowing your farm’s most valuable asset – your land – has protection when nature throws its worst your way.
Application, Renewal & Claims Process for Agricultural Land Insurance
Let’s face it – paperwork isn’t anyone’s favorite part of farming. But understanding the rhythm of agricultural land insurance deadlines can make all the difference when disaster strikes. As a New York farmer, knowing when and how to handle your insurance matters is just as important as knowing when to plant and harvest.
Key Dates & What Happens If You Miss Them
The agricultural insurance world runs on a calendar that every farmer needs to mark clearly:
Sales Closing Date: This is your absolute deadline to apply for new coverage or make changes to existing policies. For most spring crops across New York, circle March 15th on your calendar in red ink.
Acreage Reporting Date: By July 15th for most spring-planted crops, you’ll need to tell your insurer exactly what you’ve planted and where. Think of this as taking attendance for your fields.
Production Reporting Date: Usually coming about 45 days after the sales closing date, this is when you submit your yield history. Your past performance affects your future rates, so accuracy matters here.
Premium Billing Date: August 15th is when most spring crop premium bills arrive in your mailbox. Budget accordingly!
End of Insurance Period: Your coverage has a finish line – typically at harvest, the end of the marketing period, or a specific calendar date, depending on your policy.
Thomas Anderson from our team at Farm & Country Insurance has seen it all when it comes to missed deadlines: “Missing the sales closing date is like trying to buy car insurance after you’ve had an accident. It simply won’t work. You’ll have to wait until next crop year, leaving your farm completely exposed to whatever Mother Nature throws your way.”
If you miss the acreage reporting deadline, your policy technically remains in effect, but any claim becomes a complicated mess with potentially reduced payments. Late production reporting often results in assigned yields that might be lower than what you actually produced, affecting your guarantees for years to come.
For specific dates in your county for your particular crops, the RMA’s Information Browser is an essential bookmark on your computer.
Filing a Claim When Disaster Strikes
When trouble hits your farm, knowing the proper claim steps can mean the difference between quick recovery and financial struggle:
First, call your agent immediately – not tomorrow, not next week. Claims must be reported within 72 hours of finding damage. At Farm & Country Insurance, we maintain a 24-hour claims hotline because we know disasters don’t wait for business hours.
Before you touch anything, document everything. Take photos and videos showing the extent of damage. Your smartphone can be your best ally in the claims process.
Even though it might seem pointless, continue caring for damaged crops as if they were still viable, unless your adjuster specifically says otherwise. Abandoning them prematurely can jeopardize your claim.
When the adjuster visits, be prepared to walk your land together. These professionals are trained to assess agricultural damage fairly, but they rely on your knowledge of your own operation.
Jennifer Williams from our Farm & Country Insurance team recalls a success story: “When heavy rains washed away topsoil on a client’s 200-acre farm in Sennett last year, we had an adjuster on-site within 48 hours. Because the farmer had fantastic documentation and followed every procedure by the book, their $63,000 claim for land restoration was processed in less than three weeks.”
All claims are evaluated against “good farming practices” – the production methods recognized by agricultural experts as appropriate for your crop and region. Cutting corners on these practices can lead to denied claims, regardless of how severe your damage might be.
For most agricultural land insurance claims, you can expect this timeline:
– Initial inspection within 1-2 weeks after filing
– Claim processing taking 2-4 weeks after you’ve submitted all documentation
– Payment typically arriving within 30 days of claim approval
The path from disaster to recovery isn’t always quick, but with proper documentation and prompt reporting, Farm & Country Insurance works to make it as smooth as possible for New York farmers.
Choosing the Right Agricultural Land Insurance Coverage
Selecting the optimal agricultural land insurance coverage isn’t just about checking a box—it’s about protecting your livelihood and the land that sustains your operation.
Tools & Resources to Guide Your Decision
Finding your way through the maze of agricultural insurance options doesn’t have to be overwhelming. Several practical tools can light the path forward.
The USDA’s Agent Locator is your first stop to connect with knowledgeable professionals who understand both insurance products and local farming conditions. These agents can be worth their weight in gold when it comes to translating insurance jargon into plain English.
“Think of the Cost Estimator Tool as your financial crystal ball,” says Michael Thomas, senior risk analyst at Farm & Country Insurance. “It won’t predict the future, but it will show you what different coverage scenarios might cost your operation.” This online calculator helps farmers compare premiums across various coverage levels without committing to anything.
Indemnity Maps might sound technical, but they’re essentially storytellers—showing where and when losses have historically occurred in your region. These visual tools reveal patterns that might not be obvious otherwise, helping you focus your coverage where it matters most.
At Farm & Country Insurance, we’ve gone a step further for New York farmers by creating region-specific risk assessment tools.
“Our clients in the Finger Lakes region face different challenges than those in the Hudson Valley,” explains Thomas. “We developed a New York-specific worksheet that’s helped dozens of farmers align their coverage with actual risk exposure rather than just following their neighbor’s lead.”
When choosing coverage, consider your operation’s unique fingerprint: your financial cushion for absorbing losses, the quirks of your local weather patterns, your specific soil types, your crop diversity, and any requirements from lenders or market contracts. These factors should shape your coverage decisions more than general advice.
For a truly comprehensive shield around your farm business, explore broader Agriculture Insurance options alongside your land-specific coverage.
Agricultural Land Insurance for Diversified & Small-Scale Farms
If you’re running a smaller or more diverse operation, you might have felt left out of traditional crop insurance programs in the past. The good news? The insurance world has finally started catching up with the reality of modern farming.
Whole-Farm Revenue Protection has been a game-changer for diversified farms. Instead of insuring each crop separately (an administrative nightmare for diverse operations), WFRP covers revenue from everything you produce under one policy umbrella, up to $8.5 million.
The newer Micro Farm policy is even better news for small producers. If your farm generates up to $100,000 in revenue, this streamlined option dramatically reduces the paperwork burden while providing meaningful protection. It’s particularly valuable for direct-market farms, CSAs, and value-added producers who previously struggled to find appropriate coverage.
Emily Wilson from Farm & Country Insurance recently helped a client in Ledyard who perfectly illustrates this evolution: “This farmer runs a beautiful 15-acre vegetable operation with both direct sales and a CSA program. Traditional crop insurance was like trying to fit a square peg in a round hole, but the Micro Farm policy clicked into place perfectly—providing affordable protection that acknowledged their unique business model rather than fighting against it.”
For organic producers, dedicated Organic Price Elections now reflect the premium prices these products command in the marketplace. This means coverage levels align with actual market values rather than conventional crop prices.
Farms with agritourism components face a double challenge—protecting both their agricultural production and their visitor experiences. We typically recommend layering agricultural land insurance with specialized liability coverage to create a comprehensive safety net for these multifaceted operations.
The insurance industry has come a long way in recognizing that not all farms fit the conventional mold. Whether you’re growing specialty mushrooms, raising heritage livestock, or producing maple syrup, there’s likely a coverage option that fits your unique operation—you just need to know where to look.
Frequently Asked Questions about Agricultural Land Insurance
What risks does agricultural land insurance cover that crop insurance doesn’t?
When farmers ask me this question, I always explain that crop insurance and agricultural land insurance serve different but complementary purposes. While crop insurance protects what you grow, land insurance protects where you grow it.
Agricultural land insurance specifically addresses these often-overlooked risks:
Soil erosion damage is a major concern for many of our clients. After heavy rainfall or flooding, topsoil loss can be devastating. Your land insurance covers the costs to restore this precious resource.
Land contamination protection is another crucial benefit. If your soil productivity is damaged by accidental chemical spills or drift from neighboring properties, your land insurance steps in where crop policies won’t.
Infrastructure damage to irrigation systems, drainage tiles, terraces and other land improvements are covered too. These systems are vital to your land’s productivity but fall outside typical crop policy coverage.
Geological events like landslides and sinkholes can suddenly render portions of farmland unusable. Agricultural land insurance provides financial protection against these unpredictable disasters.
I remember when David Thompson, one of our agents at Farm & Country Insurance, helped a client in Conquest after the severe flooding in 2019. “Their farm lost nearly 2 inches of topsoil across 40 acres,” David told me. “Their agricultural land insurance covered the $28,000 cost of soil replacement and restoration, which their crop policy wouldn’t have touched.”
Are there subsidies for new and young farmers?
Yes! If you’re just starting your farming journey, there’s good news about financial support for your insurance needs.
Beginning farmers receive several significant benefits that can make agricultural land insurance much more affordable:
Premium subsidies give you an additional 10% discount on some coverage levels, which can make a substantial difference in your annual costs. The $655 administrative fee for catastrophic and additional coverage policies? Completely waived for qualifying beginning farmers.
“Many young farmers don’t realize they can defer premium payments until the end of the crop year,” explains our senior agent at Farm & Country Insurance. “That flexibility with cash flow can be a game-changer when you’re just getting established.”
You’ll also benefit from increased substituted yield adjustment at 80% of the applicable T-Yield instead of the standard 60%, giving you better coverage during those crucial early years.
To qualify, you need to have operated a farm for 5 years or less. Be prepared to provide tax records and evidence of your farm participation.
Beyond federal programs, New York State offers additional support through the Department of Agriculture and Markets, including specialized land access programs and grants that work wonderfully alongside your insurance coverage.
How fast can I expect a payout after filing a claim?
Nobody wants to wait for money when disaster strikes, but the timeline for agricultural land insurance claims does vary based on several factors.
Simple claims often settle within 2-3 weeks, while more complex land restoration claims might take 4-8 weeks to process completely. Your documentation readiness makes a huge difference – claims with complete records move much faster than those requiring additional information gathering.
During widespread disasters, adjusters may be handling many cases simultaneously, which can extend timelines. And when it comes to erosion or contamination claims, expert assessment is usually required, which adds some time to the process.
At Farm & Country Insurance, we’ve developed systems to expedite claims for our clients. Robert Davis from our team shared a success story: “We had a client in Scipio whose land was severely damaged by a flash flood in June—right in prime growing season. By having our team pre-assemble the required documentation and working directly with the adjuster, we helped secure payment within 18 days, allowing immediate restoration work to begin.”
While most insurance companies issue payments within 30 days of claim finalization, we understand that every day matters when your land needs restoration. That’s why we work closely with adjusters and claims departments to accelerate the process whenever possible.
The sooner you contact us after finding damage, the quicker we can start the claims process for you. That first phone call can make all the difference in how quickly you receive your payout.
Conclusion
Agricultural land insurance isn’t just another expense for your farm—it’s a crucial safety net that protects your most valuable asset. After all, without productive land, there simply is no farm.
Throughout this guide, we’ve seen how this specialized coverage goes beyond traditional crop insurance to safeguard the very soil beneath your feet. For New York farmers battling increasingly unpredictable weather patterns—from flash floods in the Southern Tier to drought conditions in Western New York—having solid protection creates a foundation of financial stability in an inherently uncertain business.
I’ve worked with hundreds of farmers across Cayuga County and beyond, and I’ve seen how proper coverage has helped them bounce back from events that could have ended their family’s farming legacy. One client in Scipio told me, “When that washout took half my best field, I thought we were done for. But our land insurance coverage meant we could rebuild rather than give up.”
Since opening our doors in 1984, we at Farm & Country Insurance have been deeply committed to helping New York’s agricultural community steer these complex waters. We understand the unique challenges faced by dairy producers in Moravia, vegetable growers in Fleming, and orchard owners in the Finger Lakes because we’ve walked those fields alongside you.
When thinking about protecting your farm, remember:
Your agricultural land insurance should match your specific operation. The coverage that works for your neighbor’s dairy farm might not be right for your diversified vegetable operation. That’s why we take the time to understand exactly what you grow, how you grow it, and what keeps you up at night.
Don’t overlook the substantial government subsidies that can make coverage surprisingly affordable. Many farmers I meet are genuinely surprised when they see the actual numbers—especially beginning farmers who qualify for additional support programs.
Timing matters enormously in this business. Missing a sales closing date by even one day means waiting an entire year for coverage. Our team at Farm & Country Insurance helps clients stay ahead of these critical deadlines.
When disaster strikes, quick action and thorough documentation make all the difference between a smooth claim and a frustrating experience. Having someone in your corner who knows exactly what adjusters need to see can shave weeks off your claim processing time.
Whether you’re managing thousands of acres or a small specialty crop operation, there’s an insurance solution designed for your needs. The agricultural insurance landscape has evolved dramatically in recent years, with new options like Micro Farm coverage bringing protection to farms of all sizes.
As you consider your risk management strategy, I invite you to Contact our farm-certified team for a personalized review of your current coverage. Our decades of experience specifically in New York agriculture positions us to provide guidance that goes beyond generic insurance advice.
Because when it comes to agricultural land insurance, having a partner who understands both insurance and farming isn’t just helpful—it’s essential. Your land is too important to trust to anyone else.