
Protecting Your Agricultural Investment in the Empire State
When the sun rises over your barn in the rolling hills of Upstate New York, there’s a certain peace that comes with knowing your agricultural investments are protected. Barn insurance New York isn’t just another policy – it’s your safety net against the unpredictable forces that threaten the structures at the heart of your farm operation.
From the historic timber-frame barns dotting the Finger Lakes to modern metal structures in the Hudson Valley, proper insurance coverage is what stands between a temporary setback and a financial disaster. As a New York farmer, your barn likely represents one of your most significant investments, housing everything from valuable equipment and livestock to this season’s harvest.
What makes barn insurance New York different from standard homeowners coverage? The answer is specialization. Traditional homeowners policies typically exclude or severely limit coverage for agricultural structures, leaving dangerous gaps in protection. A dedicated barn policy, however, addresses the unique risks facing farm buildings across our state’s diverse climate zones.
Here at Farm & Country Insurance, we’ve spent nearly four decades getting to know the specific challenges New York farmers face. I’m Casey Love, and my team has helped countless farm owners sleep better at night knowing their barns are properly protected against fire, wind damage, theft, and potential liability claims.
Barn insurance New York policies typically include:
* Property coverage protecting the structure itself
* Contents coverage for equipment and supplies stored inside
* Liability protection if someone is injured in or around your barn
Most farm owners can expect basic coverage to start around $1,500 annually, though costs vary based on factors like your barn’s size, age, construction materials, and intended use. Farm & Country Insurance works with several trusted insurance providers to find the right coverage for your specific needs.
When you’re ready to explore coverage options, you’ll need information about your barn’s dimensions, construction materials, age, purpose, security features, and replacement value. But don’t worry – we’ll guide you through the process with the same care we’d show our own family farms.


Barn Insurance New York Basics
When we talk about Barn insurance New York, we’re referring to specialized coverage that goes far beyond what your standard homeowner’s policy offers. While farm insurance generally protects your entire agricultural operation, barn insurance specifically focuses on safeguarding the structures that house your valuable equipment, livestock, feed, and other essential assets.
Since 1984, Farm & Country Insurance has been helping farmers across the Empire State understand the critical difference between general property insurance and the specialized protection their barns require. Having insured over 650 New York farms, we’ve gained unique insight into the specific challenges facing agricultural structures in our diverse climate regions.
As one of our long-time clients recently shared, “Your farm is your home, your livelihood, your culture, your employees’ jobs, your heritage, your family’s future and so much more.” This perspective drives everything we do when creating Barn insurance New York solutions custom to your operation.
The Scientific research on farm insurance from Cornell University underscores the importance of specialized coverage, while our guide on Farm Policy Insurance provides a deeper dive into comprehensive protection.
It’s worth noting that the New York Safety in Agritourism Act provides some liability protection for farms that host visitors, but only if you follow strict guidelines. This makes proper barn insurance even more crucial for operations welcoming the public to your property.
Why Barn Insurance New York Matters
For most farmers, barns represent one of their largest capital investments outside of land itself. Asset protection is paramount – a properly insured barn ensures you can rebuild after a catastrophic event without depleting your savings or taking on unexpected debt.
Revenue continuity is another critical factor. If your barn houses essential equipment or livestock, damage could halt your operations completely. The right insurance helps you recover quickly and maintain income when disaster strikes.
There are also practical lender requirements to consider. If you have a mortgage or loan on your farm property, your lender will typically require adequate insurance on all structures, including barns – it’s not optional.
Tracy M., a grain farmer from Cayuga County, recently shared this experience with us: “We had a sprayer damaged in a collision and needed to rent one quickly to finish application. Fortunately, Farm & Country Insurance had added ‘Extra Expense’ to our policy years ago, so the insurance covered the rental unit.” These real-world situations demonstrate why thoughtful coverage matters.
Types of Barns Covered by Barn Insurance New York
New York’s agricultural landscape is wonderfully diverse, and so are the types of barns that dot our countryside. Barn insurance New York policies can be customized for various structures, each with unique needs:
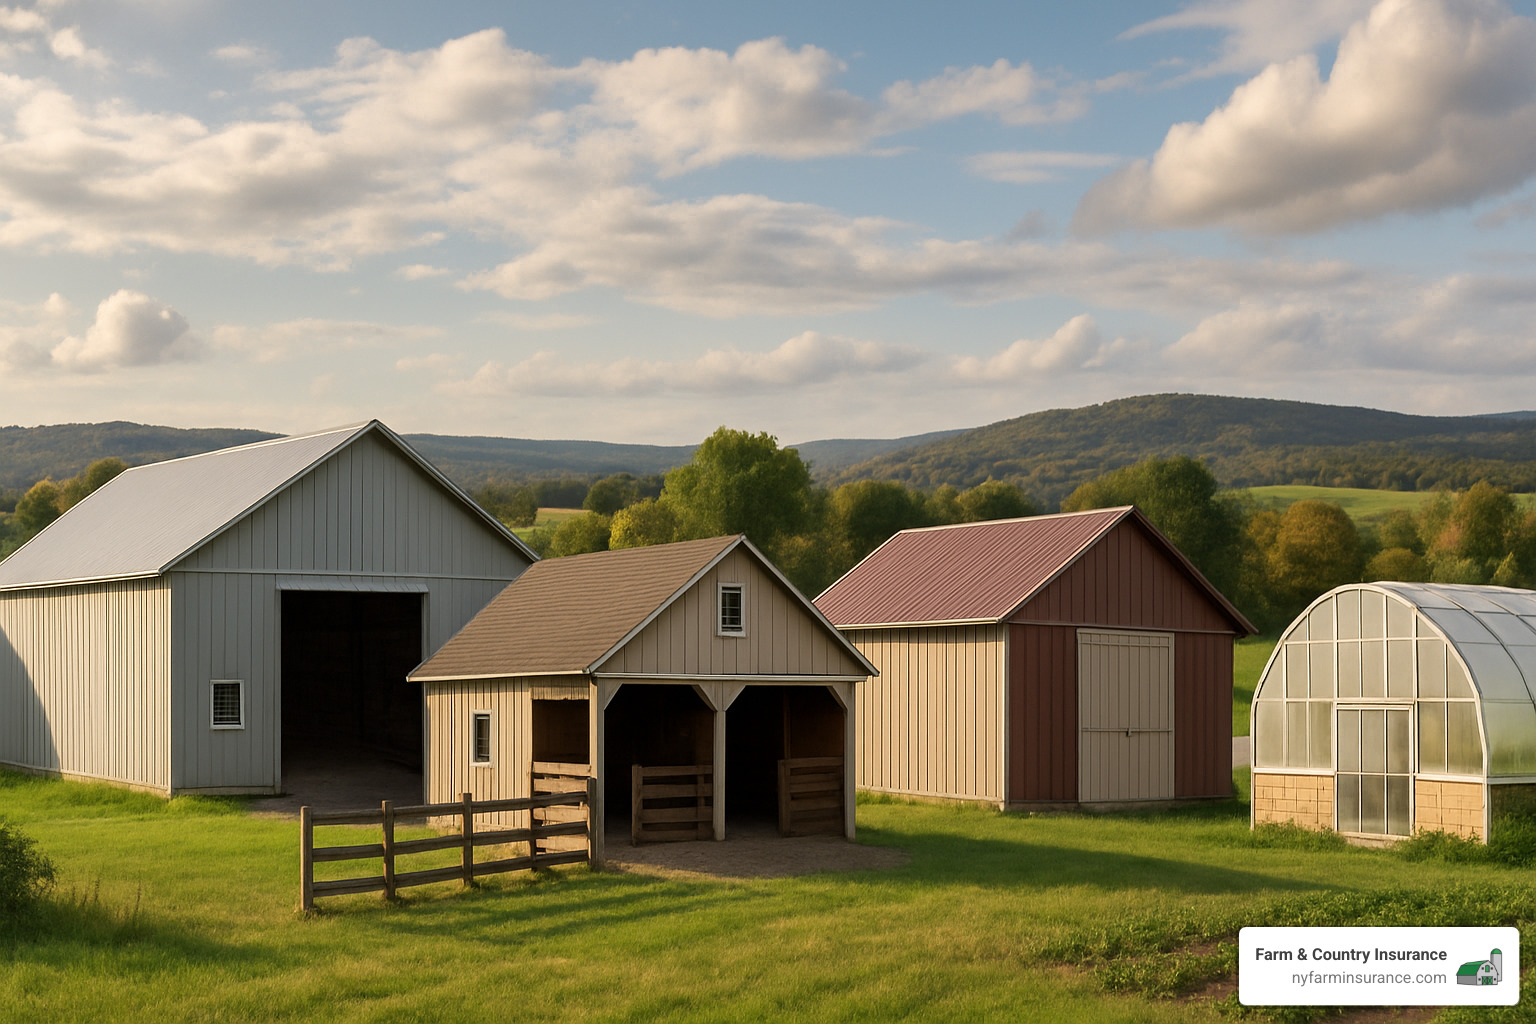
Dairy barns often include specialized equipment like milking parlors and bulk tanks that require specific coverage considerations. We understand the unique challenges dairy farmers face and can tailor protection accordingly.
Horse barns and stables typically need additional liability coverage, especially if you board other people’s horses or offer riding lessons. The equine industry has its own set of risks that standard policies might miss.
Pole barns are economical structures popular for equipment storage throughout New York. Their post-frame construction often qualifies for different rates based on their building characteristics.
Metal buildings have become increasingly common on modern farms. These structures often have different risk profiles and may qualify for discounts due to their fire resistance properties.
Equipment sheds purpose-built to house valuable machinery require appropriate coverage limits that reflect the true replacement cost of both the building and its contents.
Greenhouses, while not traditional barns, face unique risks from weather events and can be covered under specialized policies that understand their particular vulnerabilities.
At Farm & Country Insurance, we’ve seen and covered them all – from historic timber-frame barns in the Hudson Valley to modern metal structures in Western New York. We understand that no two farms are alike, and your Barn insurance New York policy should reflect your operation’s specific needs.
Coverage, Exclusions, Liability & Claims
When it comes to protecting your agricultural structures, understanding exactly what your barn insurance New York policy covers (and doesn’t cover) makes all the difference. At Farm & Country Insurance, we’ve spent decades helping farmers steer the complexities of insurance coverage to ensure they’re properly protected against the unique challenges of New York’s agricultural landscape.
Covered Perils
Your barn insurance New York policy typically shields you from a range of common threats. Fire protection tops the list for most farmers, and with good reason – the combination of hay storage, electrical systems, and equipment makes barns particularly vulnerable to fire damage.
Wind and hail protection is equally crucial in our region, where severe weather can strike in any season. I remember visiting a farm in Seneca County after a particularly violent summer storm – the metal roofing had been peeled back like the lid of a sardine can. Thankfully, their barn insurance New York policy covered the repairs completely.
Other standard covered perils include lightning strikes (both direct hits and nearby strikes that damage electrical systems), theft and vandalism, weight of ice and snow (a serious concern during our Upstate winters), and structural collapse resulting from covered events.
Excluded Risks
Just as important as knowing what’s covered is understanding what isn’t. Standard barn insurance New York policies typically exclude flood damage, which requires separate flood insurance – something many farmers overlook until it’s too late. Similarly, earthquake damage, while uncommon in our region, requires a specific endorsement.
Normal wear and tear falls squarely on your shoulders as the owner. Think of it this way: insurance covers sudden, unexpected events, not the gradual deterioration that comes with time. The same goes for insect or vermin damage, which is considered preventable through regular maintenance. And of course, intentional damage is never covered – insurance is designed to protect against misfortune, not mischief.
Claims Process for Barn Damage
When disaster strikes, knowing how to steer the claims process can mean the difference between a smooth recovery and frustrating delays. First, contact your agent immediately – waiting even a few days can complicate your claim. While you wait for the adjuster, document everything with photos and videos before cleaning up.
When the adjuster visits, they’ll assess the damage and estimate repair costs. Based on your coverage terms (replacement cost vs. actual cash value – we’ll cover this later), you’ll receive a settlement proposal. Once approved, you can begin rebuilding.
One of our clients, a dairy farmer from Owasco named Mike F., shared this experience: “When milk prices continued their slump for yet another year, Farm & Country Insurance was proactive in helping us keep costs down. Without us asking, they secured a better rate on our farm insurance to help us through the tough times.” This kind of personalized service is what sets specialized farm insurers apart.
Liability if Someone Gets Hurt
A critical aspect of barn insurance New York that many farmers underestimate is liability coverage. If someone is injured on your property – whether it’s a delivery person, farm worker, or visitor – you could be financially responsible.
Good liability coverage includes medical payments coverage for immediate medical expenses regardless of fault. It also provides legal defense coverage for attorney fees and court costs if you’re sued, and bodily injury liability that pays damages if you’re found legally responsible for someone’s injuries.
For farms with substantial assets or those that regularly welcome the public, we often recommend umbrella liability policies. These provide an extra layer of protection beyond your standard policy limits – think of it as an insurance safety net for your farm’s financial future.
Special-Use Barns: Agritourism & Events
Many New York farms have diversified by opening their barns for agritourism or events. While this can create valuable additional income, it also introduces new liability concerns that standard barn insurance New York policies might not address.
If you offer hayrides or corn mazes, host weddings or farm-to-table dinners, or allow the public to pick their own produce, you’ll need specialized coverage. Liquor liability becomes essential if alcohol is served at events, and proper safety signage is not just good practice – it’s often required for insurance coverage to apply.
New York’s Safety in Agritourism Act provides some liability protection for farm visitors, but only if you follow specific guidelines including proper signage and reasonable safety measures. At Farm & Country Insurance, we help you understand how to align your insurance coverage with these requirements, protecting both your visitors and your financial security.
When it comes to farm safety and risk management, resources like Farm safety & risk management and our guide on How to Prevent a Barn Fire offer valuable insights to help you protect what matters most.
Valuation, Pricing, Discounts & Legal Requirements
When it comes to protecting your barn, one of the biggest decisions you’ll face is how to value your structure. This choice not only affects what you’ll pay each month but also what you’ll receive if disaster strikes.
Replacement Cost vs. Actual Cash Value
Let’s break down the two main ways your barn can be insured:
Replacement Cost (RC): This pays to rebuild your barn with similar materials and quality, without subtracting for depreciation. While premiums run higher, you’ll get enough to rebuild properly after a loss.
Actual Cash Value (ACV): This pays what your barn is worth at the time of loss, accounting for depreciation. Your premiums will be lower, but you might need to dip into savings to fully rebuild.
At Farm & Country Insurance, we typically recommend replacement cost coverage whenever possible, especially for newer barns or those you’ve recently fixed up. After all, the last thing you want after losing a barn is to find you can only afford to rebuild half of it!

Factors Affecting Barn Insurance Pricing
Your barn insurance New York premium isn’t pulled from thin air. Several factors determine what you’ll pay:
The size matters – larger barns naturally cost more to insure. Age plays a big role too – that 100-year-old barn might have character, but insurers see increased risk. The materials used to build your barn affect both fire risk and how well it stands up to storms.
What you keep inside your barn dramatically impacts your premium. A barn full of expensive equipment presents different risks than one housing only hay. Your location matters too – how close is the nearest fire station? What’s the weather typically like in your corner of New York?
Your deductible choice gives you some control – opt for a higher out-of-pocket amount, and you’ll generally see lower premiums. And just like with other insurance, your claims history follows you. Previous losses may bump up what you pay going forward.
Basic barn insurance New York coverage might start around $1,500 annually, but if you’re looking to protect a larger operation with comprehensive coverage, expect to pay more.
Legal Requirements for Barn Insurance in New York
Unlike your car insurance, New York doesn’t legally require you to insure your barn – but that doesn’t mean you can skip it. Several situations make barn insurance effectively mandatory:
If you have a mortgage on your property, your lender will almost certainly require insurance on all structures, including barns. They’re protecting their investment, after all.
Workers’ compensation becomes required when you have employees working in your barn and cash wages exceed $1,200 in the previous calendar year. This is a New York state requirement, not something you can negotiate around.
For farms venturing into agritourism, while the New York Safety in Agritourism Act provides some liability protection, these safeguards only apply if you follow specific guidelines – which often include having proper insurance coverage.
Getting a Quote: Information Checklist
When you’re ready to request a barn insurance New York quote, having your ducks in a row saves time and ensures an accurate estimate. Here’s what you’ll need:
Know your barn’s exact dimensions and square footage – rough estimates won’t cut it. Have details about when it was built and any renovations you’ve made. Information about your roof’s type, material, age, and recent inspections will be important too.
Insurance companies want to know about your electrical system – when was it last updated and what type of wiring is in place? Be prepared to explain what you’ll be storing in the barn and what security features you have (lighting, cameras, alarms).
Don’t forget to mention any previous claims you’ve filed, and have recent photos of both the exterior and interior of your barn ready to share.
At Farm & Country Insurance, we take the time to understand your specific situation. As Doug D. from Sennett told us: “Whether I call the office to talk with Wendy or Audra, or call my agent direct, I get the same excellent service. It’s reassuring that my requests always get tended to quickly with the team approach that Farm & Country uses.”
Cutting Premiums Without Cutting Coverage
Nobody wants to pay more than necessary for insurance, but skimping on coverage is a risky game. Here are smarter ways to reduce your barn insurance New York costs:
Bundle your policies. Combining your barn coverage with other insurance often leads to meaningful discounts. Updating your electrical systems to meet National Fire Protection Association standards can lower your premiums while making your barn safer.
Installing sprinkler systems or other fire protection measures might seem expensive upfront but can significantly reduce your insurance costs over time. Membership in agricultural organizations like the New York Farm Bureau might give you access to special group rates.
Consider a higher deductible if you have the financial cushion to handle a larger out-of-pocket expense when filing a claim. Just be sure you’re comfortable with that amount should disaster strike.
Looking for more ways to protect your investment? Check out our article on Is Your Farm Property Underinsured? The Answer Might Surprise You for eye-opening insights that could save you from a financial disaster.
Risk Management & Policy Optimization
At Farm & Country Insurance, we believe that the best insurance policy is one you never need to use. That’s why we emphasize risk management alongside comprehensive barn insurance New York coverage. We’ve helped hundreds of New York farmers protect their agricultural investments while keeping premiums manageable through smart prevention strategies.
Proactive Risk Management for Barns
New York’s varied climate presents unique challenges for barn owners. Heavy winter snow, summer thunderstorms, and seasonal temperature swings all take their toll on agricultural structures.
Snow-load engineering isn’t just a technical term – it’s peace of mind when February brings two feet of heavy, wet snow. Many of our clients have avoided catastrophic collapses by ensuring their barn roofs meet or exceed local snow load requirements. As one Ontario County dairy farmer told us, “That extra $2,000 in trusses saved my entire operation during the blizzard of ’22.”
Lightning protection systems make financial sense in a state where thunderstorms are common from spring through fall. Modern lightning rods and surge protectors are surprisingly affordable and can prevent fires that might otherwise destroy generations of hard work in minutes.
Proper ventilation serves multiple purposes in New York barns. Beyond keeping livestock comfortable, good airflow reduces moisture that can rot wooden structures and creates less favorable conditions for fires to spread. Several of our clients have installed ridge vents or cupolas during routine roof maintenance, improving both building longevity and safety.
Strategic equipment separation costs nothing but thoughtful planning. Storing fuels, chemicals, and combustible materials away from hay, straw, and electrical panels dramatically reduces fire risk. We’ve seen too many total losses that began with a small, preventable ignition next to flammable materials.
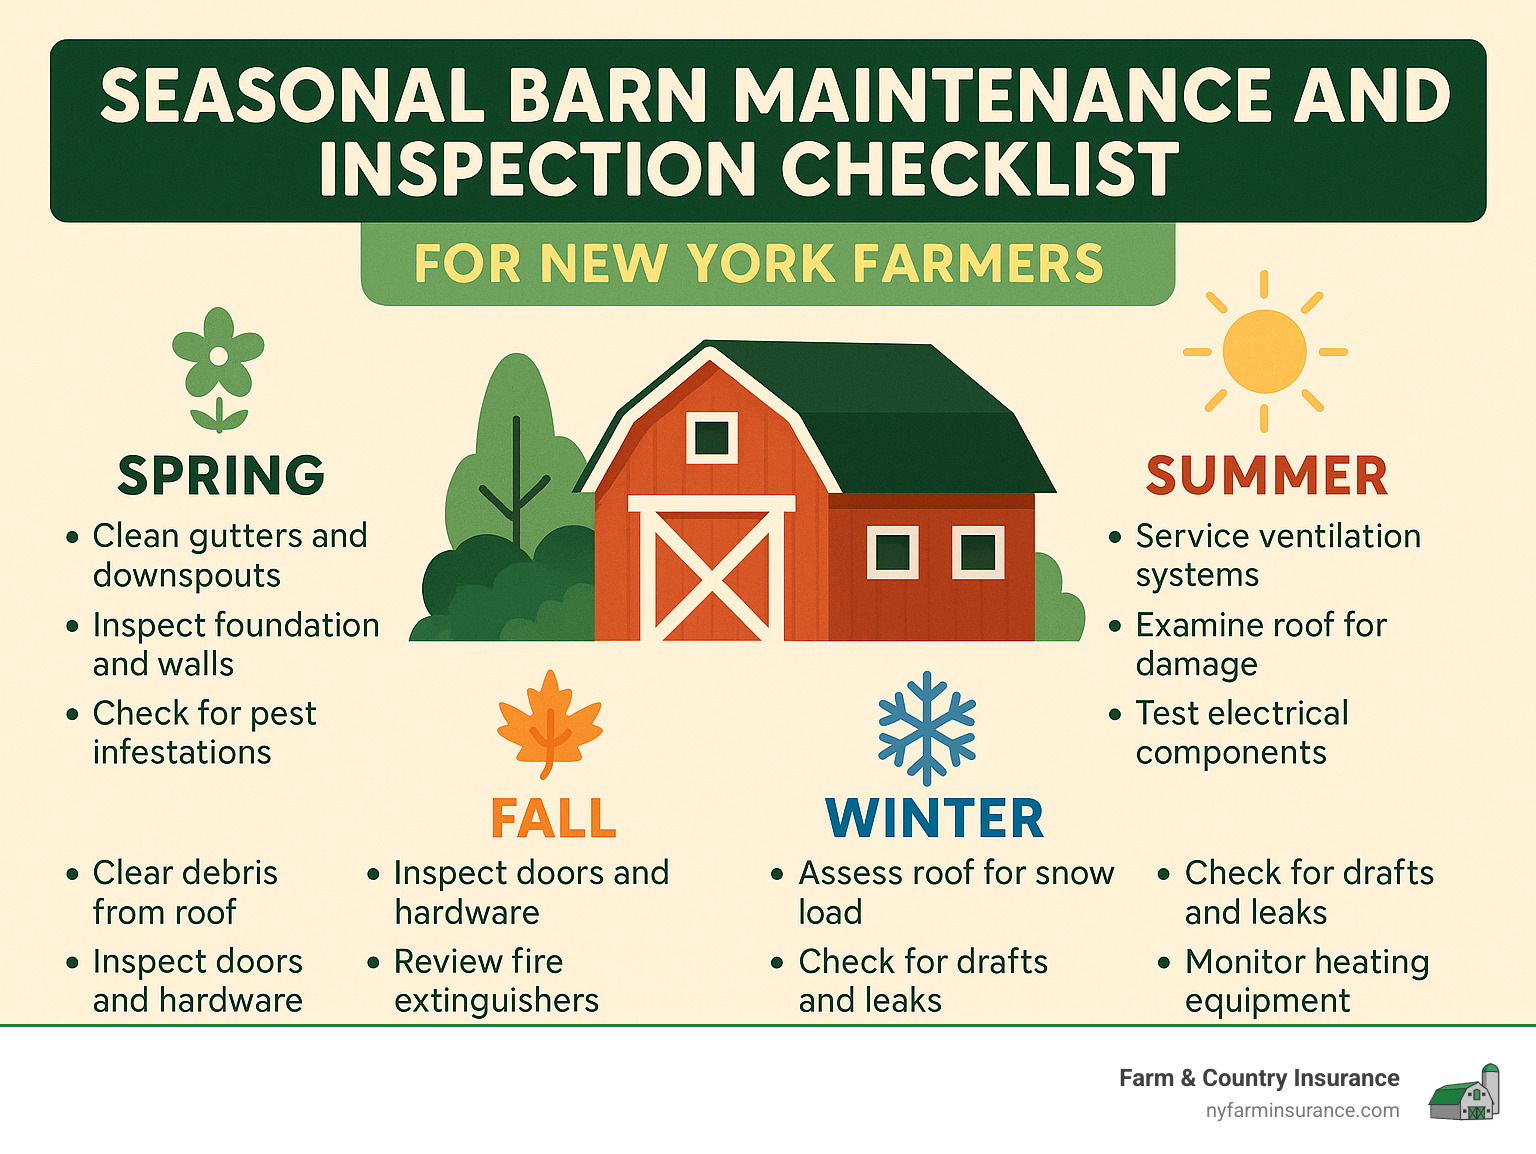
Seasonal inspections might seem tedious, but they’re invaluable. Spring and fall checks of electrical systems, roofing, and structural elements help catch small problems before they become insurance claims. Many Farm & Country Insurance clients have developed simple checklists to ensure nothing gets overlooked during busy farming seasons.
Customizing Your Policy with Endorsements
Standard barn insurance New York policies provide excellent foundational coverage, but most agricultural operations benefit from custom endorsements that address their specific risks.
Livestock coverage becomes essential when your barn houses valuable animals. Whether you’re raising prize-winning Holsteins or boarding high-value horses, this endorsement ensures you’re protected if building damage leads to animal loss or injury.
Equipment breakdown protection has become increasingly important as modern barns incorporate sophisticated systems. When a ventilation failure or electrical malfunction threatens livestock or stored crops, this coverage helps restore operations quickly.
Pollution liability might sound like something only large industrial farms need, but even modest operations store enough fertilizers, pesticides, and fuels to create environmental hazards if accidentally released. This coverage helps with cleanup costs and potential third-party claims.
Cyber protection isn’t just for office buildings anymore. As one Finger Lakes vineyard owner finded when hackers targeted his automated climate control system, modern agriculture increasingly relies on connected technology that can be vulnerable to attacks.
Business interruption coverage provides income if barn damage halts your operations. We’ve seen this endorsement save family farms when fire or storm damage would have otherwise meant months without revenue during rebuilding.
“No matter what the size of your farm or ranch…we can tailor your insurance coverage to protect your property and minimize your liability,” is our approach at Farm & Country Insurance. We understand that every agricultural operation is unique, with its own risk profile and insurance needs.
Pole & Metal Buildings vs Traditional Wood
The barns dotting New York’s countryside now showcase a mix of traditional timber frames alongside modern pole and metal structures. Each construction type offers different insurance considerations worth understanding.
Wind resistance varies significantly between building types. Metal and properly engineered pole barns typically withstand higher wind speeds than conventional wood structures, potentially qualifying for premium discounts. Several of our clients in windswept areas of Western New York have seen meaningful premium reductions after upgrading to engineered buildings.
Fire resistance generally favors metal buildings, though contents still present significant fire risks regardless of construction type. The real insurance advantage comes when metal construction is paired with thoughtful storage practices and modern electrical systems.
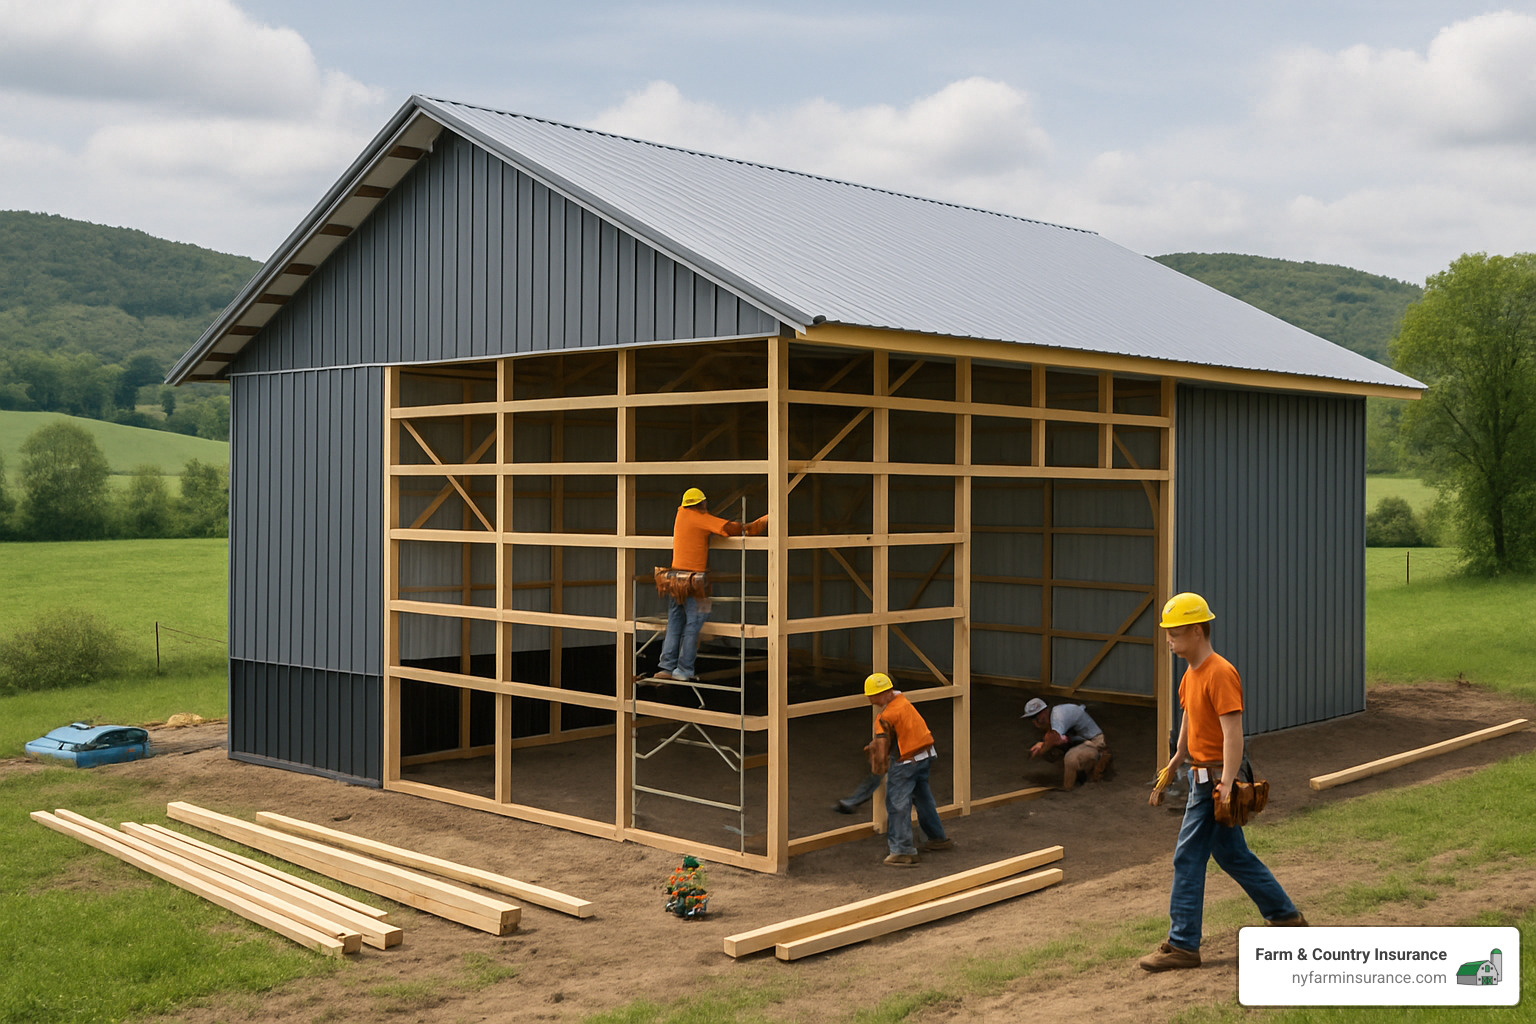
Corrosion and maintenance challenges differ between construction types. While wood barns may need periodic painting and board replacement, metal buildings can develop rust issues, particularly in dairy operations where high humidity is common. Insurers look favorably on buildings that show evidence of regular maintenance regardless of material.
Special endorsements may be necessary for certain modern construction methods. For example, fabric-covered hoop structures might need specific coverage language that standard policies don’t include. At Farm & Country Insurance, we ensure your policy language matches your actual structures.
Construction discounts often apply to newly built barns that incorporate current building codes. These discounts can be substantial – we’ve seen premium differences of 15-25% between older structures and new construction of similar size and purpose.
For farmers considering new construction, we can provide guidance on how different building methods might affect your long-term insurance costs. As one client recently told us, “The insurance savings alone are covering a big chunk of our loan payment on the new equipment barn.”
By combining smart risk management with custom coverage, Farm & Country Insurance helps New York farmers protect their barns while keeping insurance costs reasonable. We’ve been doing exactly that since 1984, and we’d love to help you too.
Frequently Asked Questions about Barn Insurance New York
How does the claims process work if my barn is destroyed?
When disaster strikes your barn, knowing what to do next can bring enormous peace of mind during a stressful time. If your barn is damaged or destroyed, contact us at Farm & Country Insurance right away – we’re here to help you through every step.
The claims process typically unfolds like this: First, you’ll want to document everything with photos and videos before anything is moved or cleaned up. Next, take reasonable steps to prevent further damage, like covering a damaged roof with a tarp. Our claims team will arrange for an adjuster to visit your property, often within 24-48 hours for serious losses.
“When my equipment shed collapsed after that heavy snowstorm last winter, I was in a panic,” shares Tom from Ontario County. “My agent at Farm & Country Insurance walked me through exactly what to do and had an adjuster out the next day. I couldn’t believe how smooth the process was.”
With barn insurance New York policies that include replacement cost coverage, you’ll receive funds to rebuild your structure using current materials and methods without deduction for depreciation. We’ll stay involved throughout the rebuilding process, helping to ensure contractors meet quality standards and that you’re satisfied with the results.
Can I bundle barn, dwelling, and crop coverage under one policy?
Yes! One of the smartest ways to protect your farm is through a comprehensive policy that brings all your coverage needs under one roof. At Farm & Country Insurance, we typically recommend bundling your:
- Farm home and personal property
- Barns and outbuildings
- Equipment and machinery
- Livestock protection
- Crop coverage options
This approach does more than just save you money (though the discounts are certainly nice). It eliminates dangerous coverage gaps that can occur when using separate policies from different companies. It also simplifies your life tremendously – one policy, one renewal date, one agent who understands your entire operation.
For specialized crop risks, we can help coordinate your private barn insurance New York policy with federally subsidized crop insurance programs through the USDA Risk Management Agency. This combination provides the most comprehensive protection against both weather-related crop losses and structural damage to your farm buildings.
What endorsements should I add for hosting events or boarding horses?
When your barn becomes more than just an agricultural building – perhaps hosting weddings or boarding horses – your insurance needs change significantly. Standard barn insurance New York policies weren’t designed for these commercial activities.
For farms hosting events like weddings or festivals, we recommend enhancing your policy with higher liability limits (typically $1 million or more), special event coverage for specific dates, and liquor liability if alcohol will be served. Business income protection is also crucial, as it helps replace lost revenue if damage prevents you from hosting scheduled events.
Horse boarding operations face unique risks that require specialized coverage. Care, custody and control coverage protects you if non-owned horses in your care are injured. Equine liability endorsements address the specific risks of working with horses, while tack coverage ensures saddles and equipment are protected.
“We started boarding horses as a side business, not realizing our regular farm policy wouldn’t fully cover it,” explains Sarah from Dutchess County. “Farm & Country Insurance helped us add the right endorsements without breaking the bank. When a boarder’s horse needed emergency vet care after a stall accident, our coverage saved us from a potential financial disaster.”
At Farm & Country Insurance, we’ve worked with dozens of agritourism operations and equine facilities throughout New York State. We understand the unique challenges these diversified farm businesses face and can tailor your barn insurance New York policy to provide the right protection.
Conclusion
Protecting your barn isn’t just about insuring a building—it’s about safeguarding the heart of your farm operation and often your family’s legacy. At Farm & Country Insurance, we’ve spent nearly four decades creating barn insurance New York policies that truly understand the unique challenges faced by agricultural structures across our state.
The weather in New York can be unpredictable and sometimes harsh—from heavy winter snow loads in the North Country to summer thunderstorms in the Finger Lakes region. Your barn stands against these elements day after day, protecting your valuable equipment, livestock, and harvested crops. Shouldn’t your insurance work just as hard?
Since 1984, we’ve walked alongside New York farmers, helping them steer the complexities of agricultural protection. We’ve seen how the right coverage can make the difference between a temporary setback and a devastating financial blow. As one of our long-time clients from Cayuga County recently told us, “Having the right barn insurance gave us the confidence to rebuild better than before after the storm took our roof.”
Whether you’re running a multi-generation dairy operation, boarding horses near Saratoga, or growing organic vegetables in the Hudson Valley, we understand that your barn isn’t just a structure—it’s central to your livelihood. Our team takes the time to learn about your specific operation, recommending coverage that protects what matters most to you.
Don’t wait until after a loss to find gaps in your protection. The time to review your barn insurance New York policy is now, before you need it. Our local agents live and work in the communities we serve, giving us unique insight into the challenges facing New York farmers.
Ready to take the next step? Contact Farm & Country Insurance today for a personalized review of your barn coverage. We’ll walk your property with you, identify potential risks, and create a protection plan that makes sense for both your operation and your budget.
The peace of mind that comes with proper coverage is invaluable. As we like to say to our clients, “We hope you never need to use your policy, but if you do, we’ll be there every step of the way.”
Request a quote today and find why more than 650 New York farms have trusted Farm & Country Insurance with their agricultural protection needs since 1984. After all, your barn protects what matters to you—let us protect your barn.