
Why Every Farm Needs Business Insurance Protection
Why Your Farm is More Than a Home: Understanding Farm Business Insurance
Running a farm means your living space and workplace overlap. Family cars share the driveway with tractors, and customers might walk past your porch to reach the farm stand. That blend is exactly why you need Agricultural Business Insurance—standard homeowners policies simply do not protect business property, equipment, livestock, or customer injuries.
Homeowners insurance typically excludes business activities and commercial structures. If lightning strikes a barn full of machinery or a visitor slips during a dairy tour, a homeowners policy will not help. Business insurance for farms fills that gap so one accident can’t wipe out years of work.
The Unique Risks Facing Today’s Farms
Modern agriculture faces risks that change with every season:
- Severe weather—drought, flood, hail, wind
- Equipment breakdowns during planting or harvest
- Livestock disease or pest infestation
- Product contamination or recalls
- Agritourism injuries and visitor liability
- Sudden market price swings
Farm and Ranch Insurance Coverage is built to handle those challenges so your operation keeps running.
Who Needs Farm Business Insurance?
If your property produces income or exposes you to farm-related liability, you need specialized protection. That includes:
- Dairy, grain, fruit, and vegetable farms
- Vineyards, orchards, and livestock producers
- Hobby farms that sell eggs or board animals
- Large corporate growers and agribusinesses
Coverage is never one-size-fits-all. What Type of Insurance Does a Dairy Farmer Need? looks very different from Hobby Farm Insurance, and Farm & Country Insurance customizes each policy accordingly.
The bottom line: if farming income helps pay your mortgage—or could threaten it—you need business insurance for farms that treats your land as the business it is.
Building Your Shield: Core Coverages in a Farm Insurance Policy
Think of your farm insurance policy as a custom-built shield that protects your operation from every angle. Unlike the one-size-fits-all approach of homeowners insurance, business insurance for farms is designed specifically to handle the unique blend of residential living and commercial farming that defines agricultural life.

What makes Farm Business Insurance special is its flexibility. At Farm & Country Insurance, we work with you to create coverage that matches your actual operation—whether you’re growing vegetables on ten acres in Cayuga County or milking 500 cows in Auburn. You shouldn’t pay for coverage you don’t need, but you also can’t afford to leave gaps in protection.
The beauty of farm insurance lies in its ability to bundle multiple types of coverage into one comprehensive policy. This approach not only saves money but also ensures all your coverage works together seamlessly when you need it most.
Property and Asset Protection
Your farm’s physical assets represent years of hard work and significant financial investment. Property coverage protects these essential elements of your operation, starting with the places where you live and work.
Farm dwellings receive protection that goes beyond typical homeowners coverage. Your farmhouse is covered along with your personal belongings, but the policy recognizes that your home is part of a larger agricultural operation. This means coverage considers factors like the increased liability from having a business on the property and the potential for farm-related damage to your residence.
Barns and outbuildings are the heart of most farming operations, and Farm Building Insurance Policy coverage protects these critical structures. Whether it’s a century-old dairy barn or a modern machine shed, these buildings house expensive equipment and livestock that make your operation possible. Losing a barn to fire or storm damage could shut down your entire operation without proper coverage.
Farm personal property coverage splits into two important categories. Scheduled farm personal property covers your most valuable equipment—tractors, combines, and specialized machinery—with each item individually listed and valued. This ensures you receive full replacement cost for expensive equipment that’s essential to your operation.
Unscheduled property covers smaller tools, supplies, grain, and feed under a blanket limit. This might include hand tools, spare parts, seed inventory, and other items that collectively represent significant value but don’t warrant individual scheduling.
Agricultural Equipment Insurance has become increasingly important as farm machinery costs have skyrocketed. When a new combine can cost more than many people’s homes, having proper equipment coverage isn’t optional—it’s essential for survival.
Liability and Operations Coverage
Liability protection shields your operation from the financial devastation that can result from injury claims or property damage lawsuits. With more people visiting farms for direct sales, tours, and agritourism activities, this coverage has never been more important.
General farm liability through Farm Liability Insurance covers bodily injury and property damage claims arising from your farming activities. This might protect you if a customer is injured while buying produce at your farm stand, if your livestock damages a neighbor’s property, or if someone is hurt during a farm tour.
Product liability coverage has become essential as consumers become more aware of food safety issues. Farm Product Liability Insurance protects against claims that your agricultural products caused illness or injury. Whether you’re selling eggs at a farmers market or milk to a processor, this coverage provides crucial protection.
Commercial auto coverage for farm vehicles addresses the unique needs of agricultural operations. Insurance for Farm Vehicles recognizes that farm trucks, grain haulers, and other commercial vehicles have different usage patterns than typical business vehicles, with seasonal variations and specialized equipment that requires expert understanding.
Workers’ compensation becomes mandatory once you have employees, but it’s also wise protection for farms that rely on family members or volunteers. Traditional farm policies won’t cover injured workers without specific workers’ compensation protection, making this coverage essential for any operation with regular help.
Reading the Fine Print: Common Policy Exclusions
Understanding what your policy doesn’t cover can save you from unpleasant surprises when you need coverage most. Farm insurance policies typically exclude coverage for intentional acts and normal wear and tear—you can’t expect insurance to cover routine maintenance or deliberate damage.
Certain pollutants are often excluded from standard coverage, though specific pollution liability can be added. Custom farming for others requires separate coverage since standard farm policies focus on your own agricultural operations. Non-farm business activities conducted on your property may also need separate coverage.
Flood damage and earthquakes typically require separate policies or endorsements. These exclusions highlight why working with an experienced agent matters—at Farm & Country Insurance, we review these exclusions carefully with every client to ensure you understand your coverage and can add endorsements where needed.
The key is working with agents who understand farming and can help you steer these exclusions to build complete protection for your operation.
Beyond the Barn: Specialized Coverage for Unique Agricultural Risks
While basic farm insurance provides essential protection, many agricultural operations need specialized coverage for unique risks that go far beyond what standard policies cover. Agriculture Insurance encompasses a broad range of specialized protections that can be customized to your specific operation’s needs.
The reality is that farming involves risks you simply won’t find in other industries. Your livelihood depends on the weather, biological systems, environmental factors, and seasonal variations that can change overnight. These unique challenges require specialized insurance solutions that general commercial policies weren’t designed to handle.
At Farm & Country Insurance, we understand that every farm faces different risks. A dairy operation in Western New York has different concerns than a vegetable farm in the Hudson Valley. That’s why we offer custom solutions and endorsements that can be added to your business insurance for farms to create comprehensive protection custom to your specific operation.
Protecting Your Harvest and Herd
Your crops and livestock represent the heart of your farming operation, and protecting them requires specialized coverage that goes beyond basic property insurance. Crop insurance provides crucial protection against weather perils, disease outbreaks, and market price fluctuations that can devastate your income in a single season.
Crop and Livestock Insurance recognizes that farming is inherently risky. A hailstorm can destroy months of work in minutes, while disease can wipe out entire herds. Crop Insurance can be particularly valuable for grain farmers, fruit growers, and vegetable producers who face significant weather-related risks throughout the growing season.
Federal crop insurance programs offer subsidized protection for many crops, with farmers paying only 33-62% of the actual premium cost. These programs can insure 50-85% of average yield and 55-100% of expected price, providing substantial protection against both production and revenue losses. It’s like having a safety net that catches you when Mother Nature doesn’t cooperate.
Livestock insurance protects against animal mortality from disease, accidents, theft, and other covered perils. This coverage becomes particularly important for dairy operations, where individual animals can be worth thousands of dollars, or for breeding operations with high-value genetics. Coverage can include protection against disease outbreaks, weather-related deaths, and even veterinary expenses in some cases.
For operations in areas prone to wildlife damage, coverage for livestock losses due to predation may also be available. After all, bears and coyotes don’t care about your business plan.
Environmental and Specialized Liability
Modern farming operations face increasing environmental scrutiny and regulation, making specialized liability coverage more important than ever. Farm Pollution Liability Coverage has become essential as environmental regulations have tightened and public awareness of agricultural impacts has grown.
This coverage protects against claims related to chemical overspray, manure runoff, groundwater contamination, or other environmental incidents that can result from normal farming activities. Today’s farming operations use pesticides, fertilizers, and generate significant amounts of animal waste—all of which can create environmental liability exposures that weren’t major concerns for previous generations of farmers.
Pollution Insurance provides protection that’s typically excluded from general liability policies. Without this specialized coverage, a single environmental incident could result in cleanup costs and legal expenses that threaten your operation’s survival.
Business interruption coverage becomes crucial when a covered loss prevents your farm from operating normally. This protection helps replace lost income and pays for extra expenses needed to continue operations. This might include the cost of renting equipment after a fire, purchasing feed when your storage facilities are damaged, or finding temporary housing for livestock.
Think of it as income protection for when the unexpected happens. When your barn burns down during harvest season, you’re not just dealing with property damage—you’re facing lost income and additional expenses that can compound the financial impact.
Public Programs: How Government Support Can Work with Your Policy
Federal and state programs provide significant support for agricultural risk management, often complementing private insurance coverage rather than replacing it. Understanding how these programs work with your private business insurance for farms can maximize your protection while minimizing costs.
The USDA’s Risk Management Agency administers crop insurance programs that cover many common crops. These programs are only available through licensed crop insurance agents and provide subsidized protection against weather perils, disease, and price declines. The key is that these programs work best when integrated with your private insurance coverage.
AgriStability provides compensation when farm income drops more than 30% below historical averages, while the Noninsured Disaster Assistance Program (NAP) covers crops not eligible for federal crop insurance. Production Insurance protects against crop losses from weather perils, creating multiple layers of protection for your operation.
These programs work best when integrated with private insurance from Farm & Country Insurance. While government programs often focus on crop and income protection, private insurance provides broader coverage for property, liability, and business risks that government programs don’t address. Fact sheets on USDA programs provide detailed information about available federal support.
The beauty of combining public and private coverage is that you’re not putting all your eggs in one basket. Government programs provide a foundation of protection, while private insurance fills the gaps and provides the comprehensive coverage your operation needs to thrive.
Decoding the Dollars: What Determines Your Farm Insurance Premium?
Price matters, but value matters more. When farmers search for Farm Insurance Near Me, the cheapest quote isn’t a bargain if a single uncovered loss could cost six figures. Understanding the factors an insurer weighs helps you find affordable, appropriate protection.
Key Factors Influencing Your Rates
- Farm size and location
- Type of operation (dairy, grain, produce, etc.)
- Building, equipment, and livestock values
- Claims history
- Chosen liability limits and deductibles
- Number of employees and required workers’ compensation
- Safety measures such as fire suppression or equipment security
None of these items stand alone; they combine to create your unique risk profile and premium.
Small Family Farm vs. Large Commercial Operation
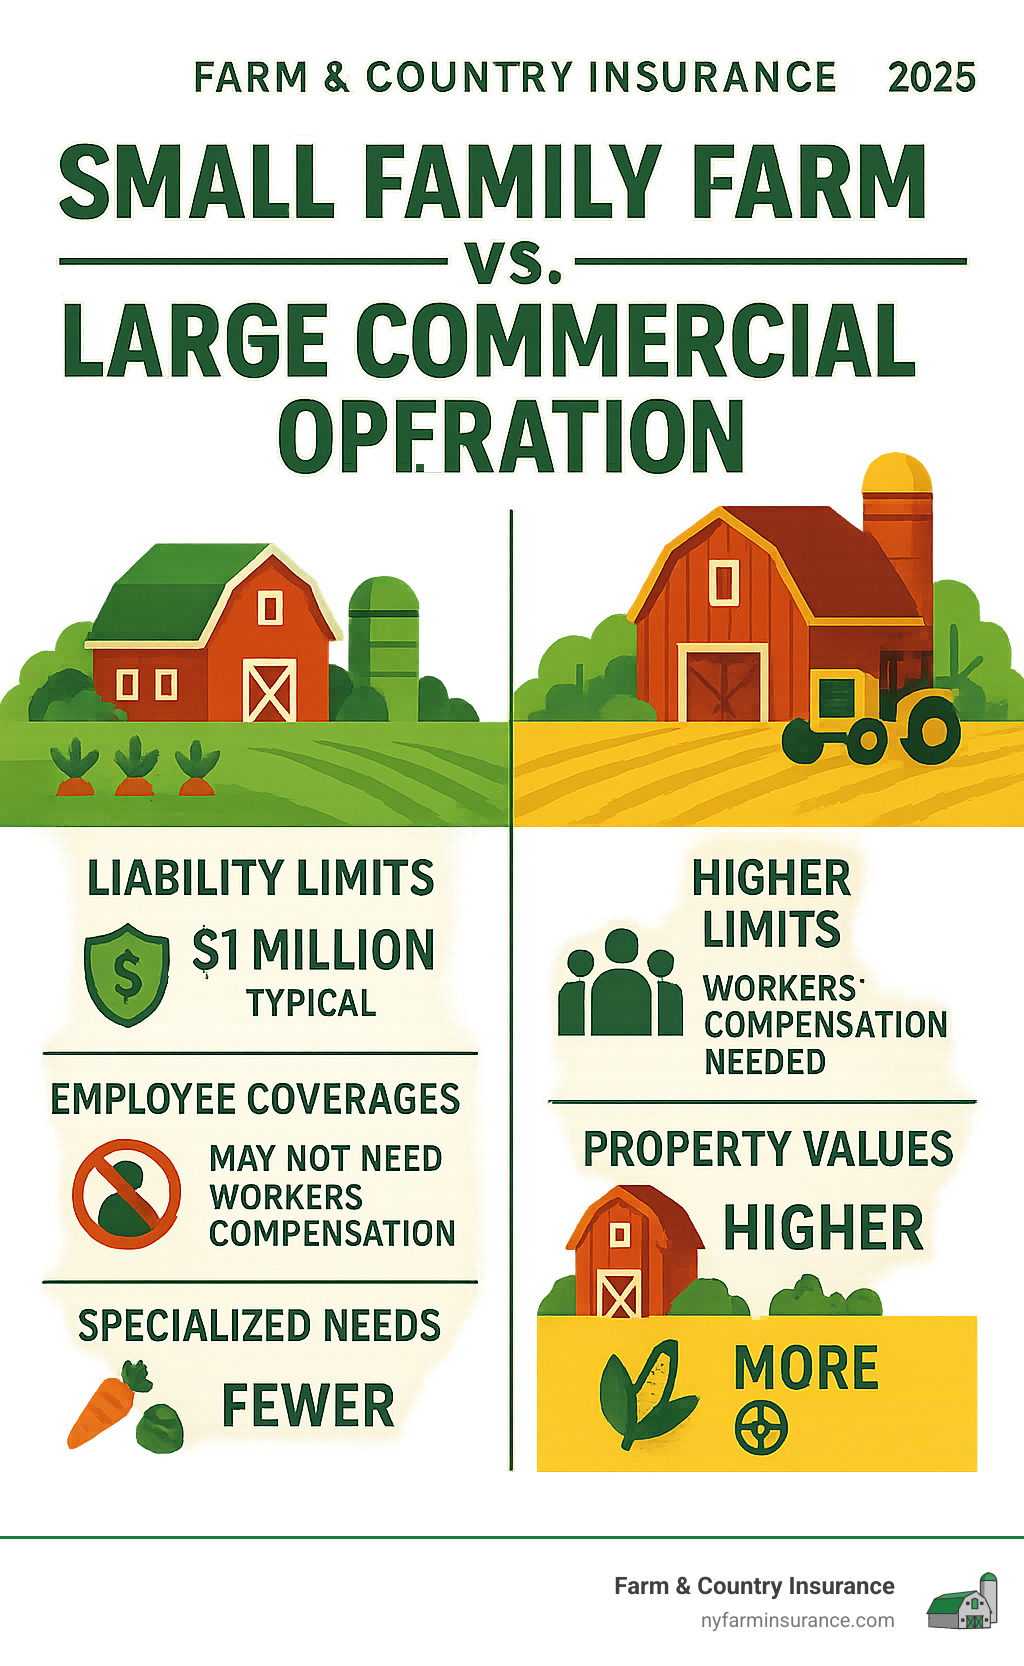
Small farms often operate comfortably with about $1 million in liability protection and no workers’ compensation if they have no employees. Large commercial operations may require $15–20 million in liability, comprehensive employee coverages, and detailed scheduling of high-value machinery spread across multiple sites.
Farm & Country Insurance has advised New York operations of every size since 1984. Whether you manage ten acres in Moravia or thousands near Auburn, we’ll balance premium and protection so you can invest in your farm—not in surprises.
Frequently Asked Questions about Business Insurance for Farms
How much does business insurance for farms cost?
The honest answer is that business insurance for farms costs vary dramatically based on your specific operation, making it impossible to give you an accurate price without sitting down and understanding your unique situation. However, I can share some general ranges that might help you budget.
If you’re running a small hobby farm with just a few chickens and a roadside vegetable stand, you might pay around $1,500 annually for basic coverage. These smaller operations typically have lower property values, fewer liability concerns, and don’t need specialized coverages like workers’ compensation.
Most mid-sized family farms find themselves paying somewhere between $3,000 to $10,000 annually, depending on what they’re growing, how much equipment they own, and what activities they’re involved in. If you’re running farm tours, have a corn maze, or sell directly to customers, you’ll likely be toward the higher end of that range.
Large commercial operations face significantly higher costs—often $15,000 to $50,000 or more annually. These bigger farms need higher liability limits, must carry workers’ compensation, and often require specialized protections that smaller operations don’t need.
Several key factors drive your premium costs: the total value of your buildings and equipment, what type of farming you do, your liability exposures, your claims history, where you’re located, and how many people you employ. An accurate quote really requires a detailed assessment of your specific operation.
Is my home covered under my farm insurance policy?
Yes, and this is actually one of the biggest advantages of farm insurance over trying to piece together separate homeowners and commercial policies. Business insurance for farms recognizes that most agricultural operations include a family residence right on the same property where the farming happens.
Your farm insurance policy typically covers your farmhouse and personal belongings just like a homeowners policy would, but it understands that your home is part of a larger agricultural operation. This means coverage for your house, your furniture, your personal vehicles, and structures like garages or sheds you use for personal purposes.
The key difference is that farm insurance bridges the gap between your personal and business activities in a way that standard homeowners insurance simply can’t. If you tried to rely on homeowners insurance alone, you’d likely find major gaps in coverage when it comes to your farming activities.
That said, the dwelling coverage in your farm policy might have different limits or conditions than a standalone homeowners policy. At Farm & Country Insurance, we always review these coverages carefully to make sure you have adequate protection for both your home and your business.
What’s the difference between farm insurance and crop insurance?
This question comes up constantly, and I understand why it’s confusing. The simple answer is that they protect different things and often work together to give you complete protection.
Farm insurance is like an umbrella that covers all the physical stuff on your farm—your buildings, equipment, livestock, and liability exposures. It protects your barns, tractors, animals, and covers you if someone gets hurt on your property. It’s the foundation that keeps your operation running.
Crop insurance, on the other hand, is specifically designed to protect your growing crops and the income they generate. It covers you when weather, disease, or pests destroy your crops, when market prices drop, or when you can’t even plant because of conditions beyond your control.
Crop insurance is often federally subsidized through USDA programs, which means the government helps pay part of your premium. It’s sold by private agents like us, but the programs are administered by the federal Risk Management Agency.
Most successful farmers carry both types of insurance because they complement each other perfectly. Your farm insurance protects your physical assets and operations, while crop insurance protects your crop investment and revenue. Together, they provide the comprehensive protection that modern farming requires.
Think of it this way: farm insurance protects what you own, crop insurance protects what you grow. You need both to sleep well at night.
Conclusion
Your farm represents more than just a business—it’s your family’s legacy, your community’s food source, and often generations of hard work and dedication. Protecting this legacy requires more than hope and determination; it demands comprehensive risk management through specialized business insurance for farms.
The reality of modern agriculture is that farms blend residential living with commercial operations in ways that create unique exposures. Standard homeowners policies weren’t designed to handle dairy cows, grain storage, or customers visiting your farm stand. Similarly, general business insurance doesn’t account for the seasonal nature of farming, weather dependencies, or the biological risks that livestock and crops face daily.
This is where Farm & Country Insurance makes the difference. Since 1984, we’ve been exclusively focused on protecting New York’s agricultural community. We understand that a hailstorm in July can devastate a corn crop, that a single sick cow can threaten an entire herd, and that equipment breakdown during harvest season isn’t just inconvenient—it’s potentially catastrophic.
Whether you’re running a small hobby farm in Moravia with a few chickens and a vegetable garden, or managing a large commercial dairy operation in Auburn with hundreds of cows and millions in equipment, the right insurance coverage provides the foundation for sustainable farming. It’s the difference between a setback and a disaster, between recovering quickly and losing everything you’ve worked to build.
The investment in proper farm insurance protection pays dividends far beyond the premium cost. When you know your buildings, equipment, livestock, and liability exposures are properly covered, you can focus on what you do best—feeding our communities and stewarding the land for future generations.
Don’t leave your farm’s future to chance. The risks facing modern agriculture are too significant, and the potential losses too devastating to operate without comprehensive protection. From basic property and liability coverage to specialized protections for crops, livestock, and environmental exposures, the right insurance program provides peace of mind and financial security.
Get a personalized assessment of your farm’s unique needs and secure your future today by exploring our Agriculture Insurance solutions. Contact Farm & Country Insurance to discuss how we can tailor protection specifically for your operation, ensuring that you never have to bet the farm on an uncertain future.