Why Finding Cheap Homeowners Insurance Matters More Than Ever
Cheap homeowners insurance lets you protect your biggest investment without draining your wallet. With premiums up roughly 25% since 2021 and the typical policy now nearing $1,000 a year, trimming costs has become a key part of smart homeownership.
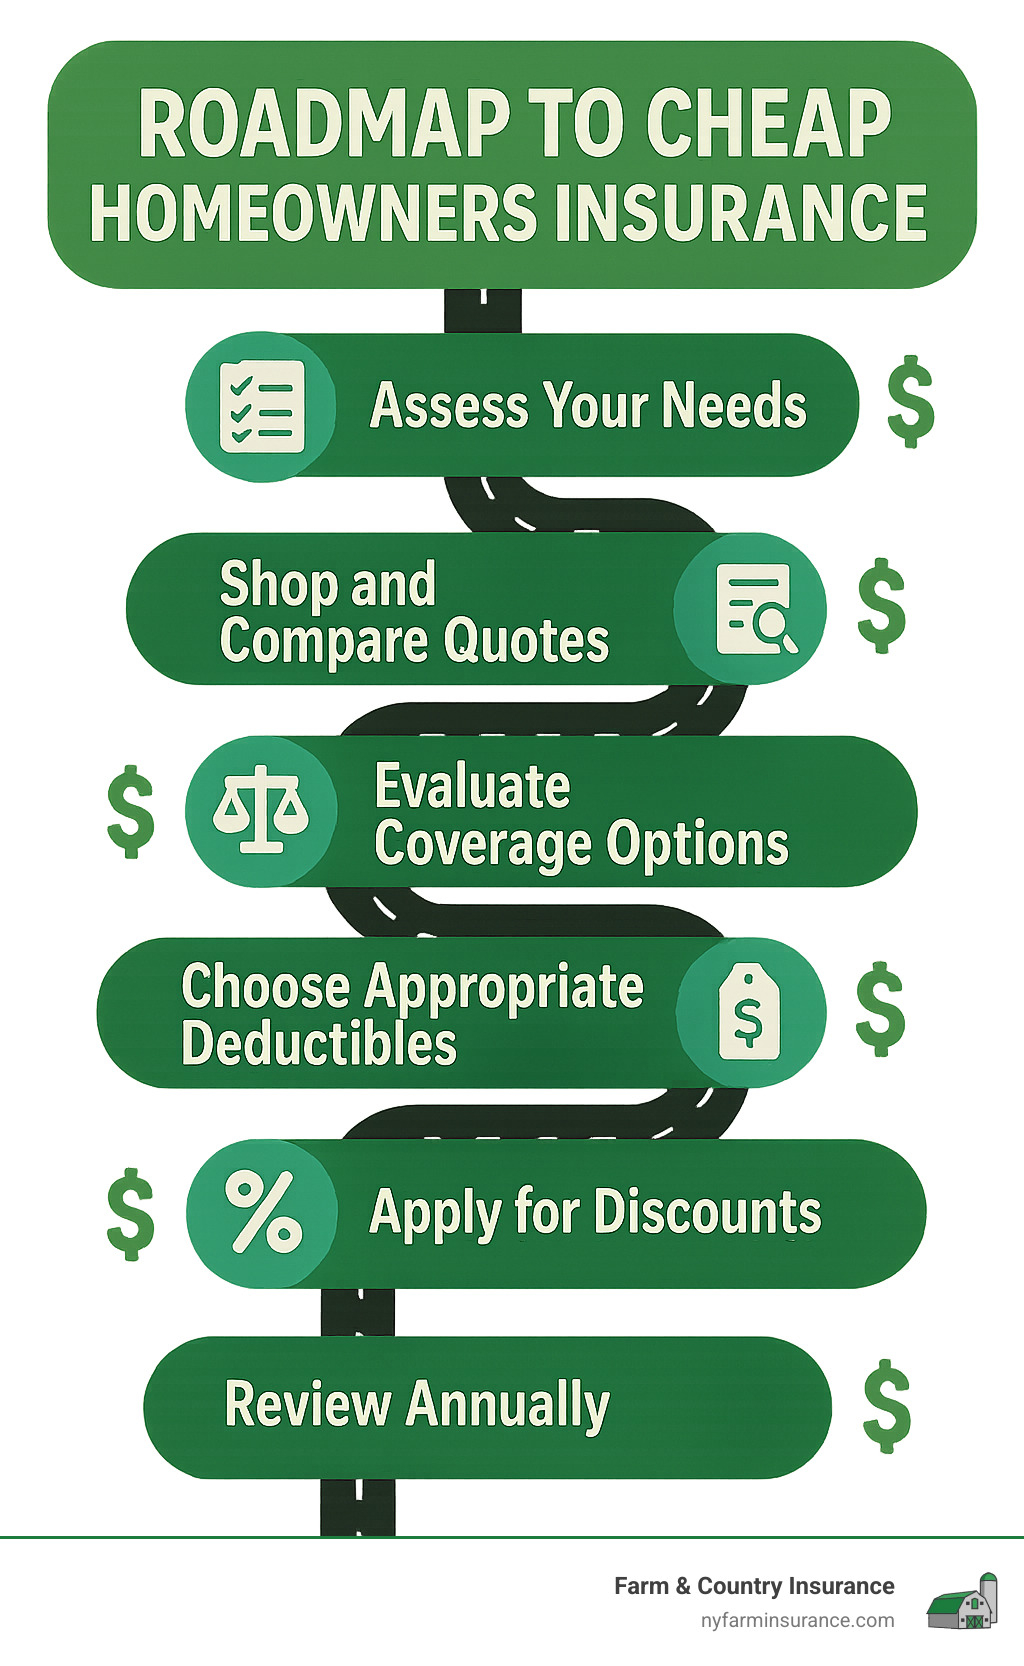
Top 5 Ways to Find Cheap Homeowners Insurance
- Increase your deductible – jumping from $500 to $2,500 can slash rates
- Bundle policies – combine home and auto for up to 15% off
- Shop around – compare quotes every year
- Install safety features – alarms, detectors, and leak sensors earn discounts
- Maintain good credit – higher scores equal lower premiums
Many owners stick with the same policy year after year and end up paying more than necessary. A quick annual quote check can easily uncover $200–$500 in savings.
I’m Casey Love, owner of Farm & Country Insurance, and I’ve watched families across New York save hundreds—sometimes over $1,000—just by applying the steps above while keeping solid coverage.
Understanding Homeowners Insurance: Your First Line of Defense
Homeowners insurance serves as your financial safety net, protecting you from unexpected losses that could otherwise devastate your finances. At its core, homeowners insurance is a contract between you and your insurer where you pay premiums to cover financial risks like damage or loss to your property and belongings due to unforeseen events.
In New York, homeowners insurance isn’t legally required by law, but it’s essentially non-negotiable for most homeowners. If you have a mortgage, your lender will require you to carry homeowners insurance as part of your financing agreement. This requirement exists because your home serves as collateral for the loan, and the lender needs to protect their investment.

Even if you own your home outright, going without homeowners insurance is a significant financial risk. Consider this: the average home in New York costs hundreds of thousands of dollars to rebuild, and that’s before accounting for your personal belongings, temporary living expenses, and potential liability claims.
What a Standard Policy Covers
A standard homeowners insurance policy includes five essential coverage components that work together to protect your financial interests:
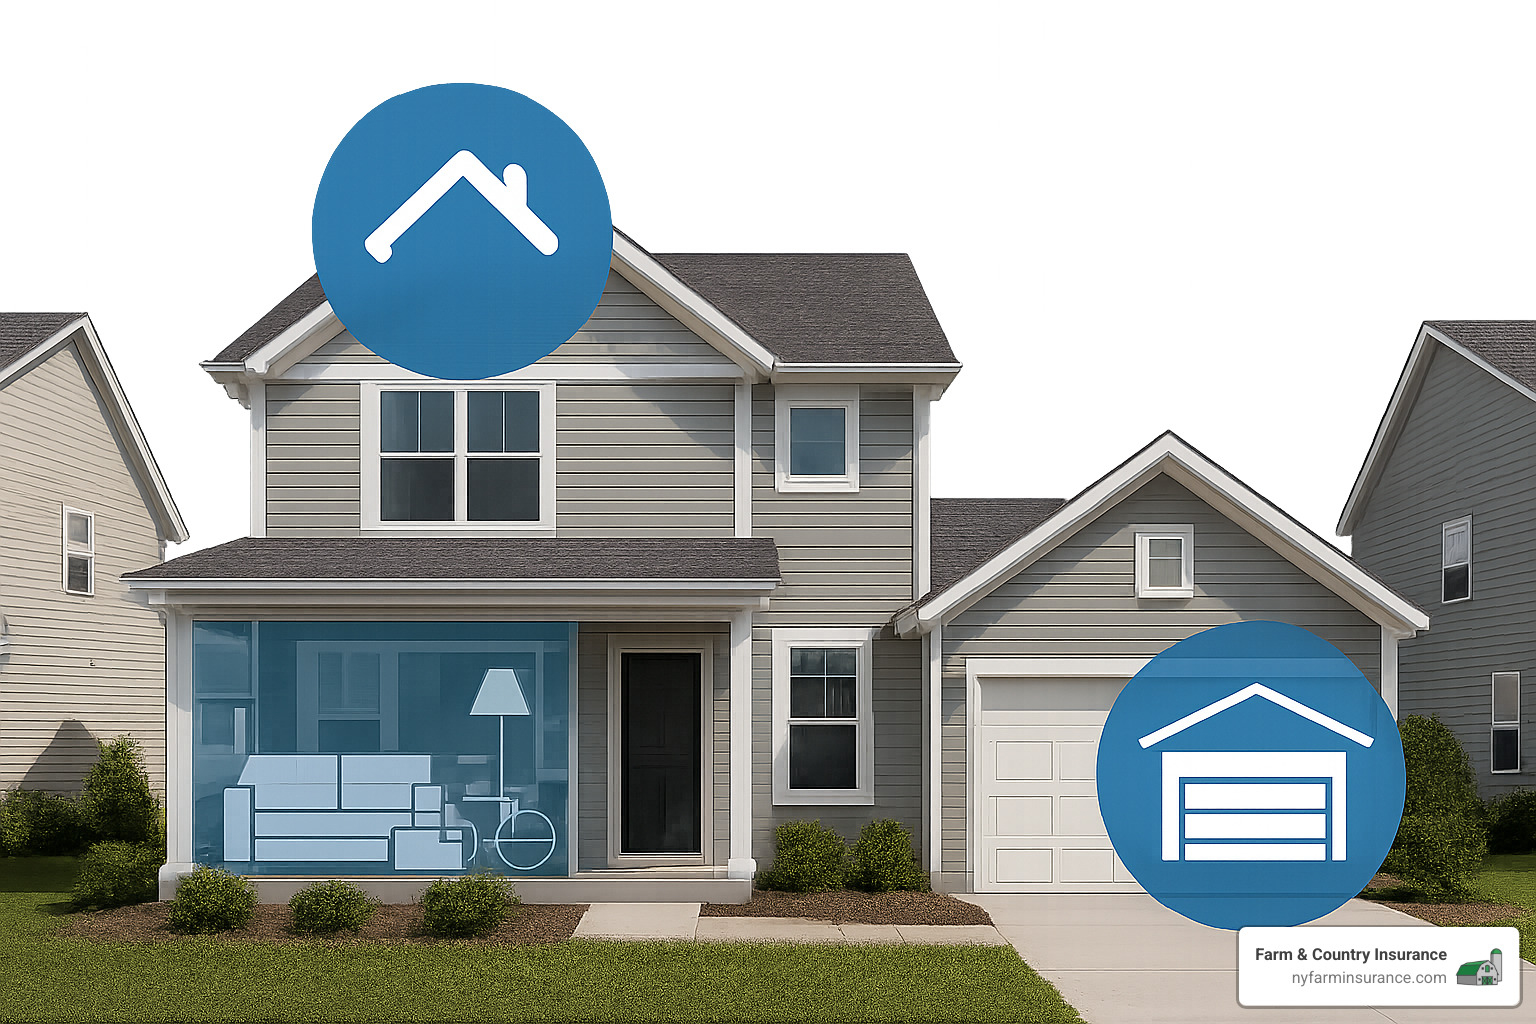
Dwelling Coverage (Coverage A) protects the physical structure of your home, including walls, roof, floors, and built-in appliances. This coverage is based on your home’s replacement cost, not its market value. For rural properties in areas like Auburn, Moravia, or Sterling, this might include coverage for unique features like wood-burning stoves or specialized heating systems.
Personal Property Coverage (Coverage C) protects your belongings inside the home. This includes furniture, clothing, electronics, and other personal items. The coverage typically ranges from 50-70% of your dwelling coverage amount. For farming families, this might include coverage for personal items stored in your home office or equipment used for hobby farming activities.
Liability Protection (Coverage E) is crucial and often overlooked. This coverage protects you if someone is injured on your property or if you accidentally damage someone else’s property. It can even cover incidents that occur away from your home. With coverage limits typically starting at $100,000 and going up to $500,000 or more, this protection is essential for rural property owners who may have visitors or workers on their land.
Additional Living Expenses (Coverage D) covers reasonable living expenses if your home becomes uninhabitable due to a covered loss. This includes hotel costs, restaurant meals, and other expenses above your normal living costs while your home is being repaired or rebuilt.
Other Structures Coverage (Coverage B) protects detached structures on your property like garages, sheds, fences, and gazebos. This coverage is particularly important for rural properties that often have multiple outbuildings.
For more detailed information about coverage for rural properties, you can learn more about what’s covered for rural homes.
Common Covered Perils vs. Exclusions
Understanding what your policy covers and what it doesn’t is crucial for making informed decisions about your coverage. Most homeowners policies cover damage from these common perils:
Commonly Covered Events:
- Fire and smoke damage
- Theft and vandalism
- Lightning strikes
- Windstorms and hail
- Explosions
- Falling objects
- Weight of snow or ice
- Sudden and accidental water damage (like a burst pipe)
Common Exclusions:
- Flooding from external sources
- Earthquake damage
- Normal wear and tear
- Pest infestations (termites, rodents, etc.)
- Intentional damage
- War and nuclear hazards
- Sewer backup (unless added as an endorsement)
The most significant exclusion for many homeowners is flood damage. Standard homeowners policies don’t cover flooding from external sources like rivers, lakes, or storm surge. If you live in a flood-prone area, you’ll need separate flood insurance, which you can learn more about through FEMA’s flood insurance information.
These exclusions exist because some perils are either predictable (like wear and tear), require specialized coverage (like floods), or are considered maintenance issues rather than sudden accidents.
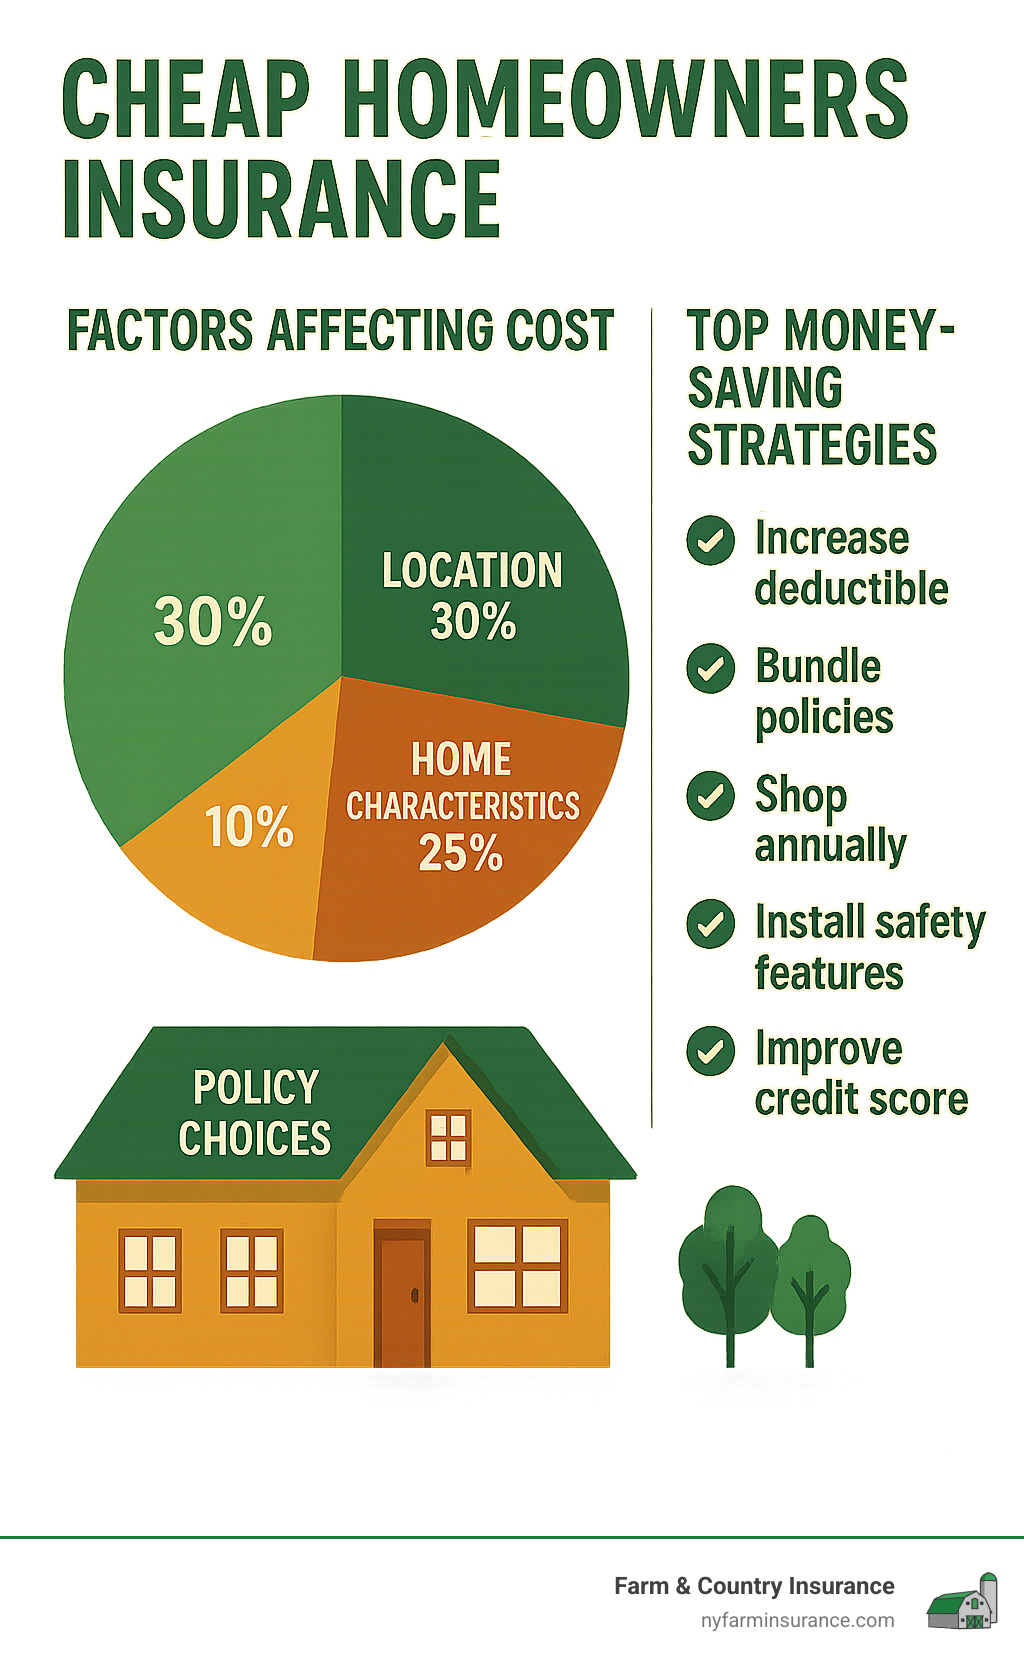
What’s Behind the Price? Factors That Influence Your Premium
Ever wonder why your neighbor pays less for homeowners insurance than you do, even though your houses look similar? The truth is, insurance companies use dozens of factors to calculate your premium, and understanding these can help you find cheap homeowners insurance that still provides solid protection.
The insurance landscape has gotten more expensive for everyone lately. Personal property insurance premiums have jumped 25% since early 2021, with year-over-year increases of nearly 11% in recent quarters. This isn’t just insurance companies being greedy – it’s a perfect storm of rising construction costs, labor shortages, and more frequent severe weather events.
Here in New York, we’ve seen our share of challenges. Severe weather caused over $3.1 billion in insured damages in 2023 alone, and home replacement costs have more than doubled since 2002. These trends affect everyone’s premiums, which makes finding ways to reduce your costs even more important.
Your Home’s Characteristics
Your house tells a story to insurance companies, and they’re very good at reading between the lines. Every detail about your property influences how much risk you represent.
Location is king when it comes to insurance pricing. If you live in an area prone to flooding, high winds, or frequent break-ins, you’ll pay more. Distance from fire stations matters too – homes more than five miles from the nearest fire department often face higher premiums. Rural properties around Auburn or Moravia might be further from emergency services, which insurers factor into their calculations.
Your home’s age and how it’s built make a huge difference. Newer homes generally cost less to insure because they meet current building codes and have less wear on critical systems. A home built in 2010 will typically cost less to insure than one from 1970, even if they’re identical in size and features.
Roof condition is something insurers pay close attention to. A newer roof, especially one made with impact-resistant materials, can earn you discounts. On the flip side, an aging roof might bump up your premium or even require replacement before an insurer will cover you.
Your electrical and plumbing systems get scrutinized too. Older systems increase fire and water damage risks, which translates to higher premiums. Upgrading these systems can lead to meaningful savings on your insurance costs.
Special features like wood-burning stoves, pools, or even certain dog breeds can affect your rates. For rural properties, things like private wells, septic systems, or outbuildings all factor into the equation.
For homes with unique features or rural properties, you might want to explore our detailed guide on house and farm insurance.
Your Personal Profile
Insurance companies have learned that certain personal characteristics correlate with claim frequency. It might seem invasive, but these factors have proven predictive over decades of data.
Your claims history carries the most weight. Even one claim can impact your rates for three to five years. Insurance companies view past claims as a predictor of future ones, so homeowners with recent claims typically pay significantly more.
Credit score plays a surprisingly large role in most states, including New York. Research shows a correlation between poor credit and higher claim frequency. The difference can be substantial – homeowners with poor credit sometimes pay thousands more annually than those with excellent credit.
Marital status might seem irrelevant, but married couples often receive lower premiums because statistical data shows they file fewer claims. Pet ownership can affect liability coverage, especially if you own breeds that insurers consider higher risk.
Home-based businesses require special attention. Standard homeowners policies provide limited coverage for business activities, so you might need additional endorsements or separate coverage, which affects your overall insurance costs.
Your Policy Choices
The coverage decisions you make have a direct impact on what you pay. Understanding these choices helps you balance cost with protection.
Coverage limits determine how much your insurer will pay for covered losses. Higher limits mean higher premiums, but they also provide better protection when you need it most. The key is insuring your home for its full replacement cost, not its market value.
Your deductible amount has an inverse relationship with your premium. Choosing a higher deductible can significantly lower your premium because you’re taking on more financial responsibility for smaller claims. Just make sure you can comfortably afford your deductible if you need to file a claim.
Endorsements and add-ons increase your premium but can provide valuable protection for specific risks. Things like sewer backup coverage or scheduled personal property coverage for valuables might be worth the extra cost depending on your situation.
Policy type affects your cost too. Comprehensive policies cost more than basic named-perils policies, but they provide much broader protection against unexpected events.
At Farm & Country Insurance, we help homeowners understand these factors and find ways to reduce their premiums without sacrificing essential protection. The goal is finding that sweet spot where you get cheap homeowners insurance that still covers what matters most to your family.
Your Ultimate Guide to Finding Cheap Homeowners Insurance
Most homeowners can lower their costs simply by being proactive. Because insurers weigh risks differently, the company that’s pricey for your neighbor might be perfect for you.
Smart Strategies for Cheap Homeowners Insurance
| Deductible | Annual Premium | Monthly | Est. Savings |
|---|---|---|---|
| $500 | $1,200 | $100 | — |
| $1,000 | $1,080 | $90 | $120 |
| $2,500 | $960 | $80 | $240 |
Only pick a deductible you can comfortably cover.
Other high-impact tactics:
- Bundle home and auto for 10–15% off.
- Add security devices—monitored alarms, smart water-shutoff valves, smoke detectors.
- Build your credit—better scores lead to better rates.
- Skip minor claims when repairs cost only a bit more than your deductible.
- Review annually so your policy keeps pace with life changes.
How to Get a Quote and Shop Efficiently
- Gather details: square footage, roof age, updates, prior claims.
- Use multiple sources: comparison sites, direct calls, and independent agents like Farm & Country Insurance.
- Compare coverage first, price second: limits, exclusions, customer service ratings.
- Read the fine print to spot missing protections or hidden fees.
- For Cayuga County residents, you can get a quote for your Auburn home.
Switching Policies & The Impact of Claims
You can change insurers anytime—just align start and end dates to avoid gaps. Each claim may raise your premium for up to five years; consider claim-forgiveness programs if you’re in a high-risk area.
Finding cheap homeowners insurance is really about balance: cut costs where you can, keep the protection you need.
Smart Shopping: How to Choose the Right Policy and Provider
When shopping for cheap homeowners insurance, price matters, but it shouldn’t be your only consideration. Think of it this way: the cheapest policy is only a good deal if it actually protects you when you need it most. A company that saves you $200 annually but makes filing a claim a nightmare isn’t really saving you money in the long run.
Evaluate Financial Stability first and foremost. You want an insurer that will still be around—and financially capable—when disaster strikes. Look for companies with strong financial ratings from agencies like AM Best, Moody’s, or Standard & Poor’s. An A+ rating or higher indicates the company has the financial strength to pay claims, even during widespread disasters that affect thousands of homeowners simultaneously.
Research Customer Service ratings, particularly for claims handling. This is where you’ll really see the difference between insurers. Companies with excellent customer service will handle your claim efficiently and empathetically during what’s likely one of the most stressful times in your life. Look for insurers that offer 24/7 claims reporting, mobile apps for submitting claims, and fast settlement processes.
Consider the Claims Process carefully. Some companies make filing claims straightforward with online portals and dedicated claim representatives. Others may have more cumbersome procedures that delay your claim resolution and add frustration to an already difficult situation. Reading customer reviews about actual claim experiences can be incredibly revealing.
Types of Home Insurance Policies
Understanding different policy types helps you choose the right coverage level for your situation and budget:
Basic (Named Perils) Policies only cover specifically listed perils like fire, theft, and windstorms. They’re the cheapest option but provide limited protection. These policies work for homeowners who want minimal coverage and are comfortable accepting more risk to save money.
Broad Form Policies cover more perils than basic policies but still use a named-perils approach. They offer a middle ground between cost and coverage, adding protection for things like falling objects and water damage from plumbing issues.
Comprehensive (All-Risk) Policies cover all perils except those specifically excluded. They’re more expensive but provide the broadest protection. Most homeowners choose this type of policy because it eliminates the guesswork about whether a specific peril is covered.
No-Frills Policies are stripped-down policies with minimal coverage designed to meet mortgage requirements at the lowest possible cost. While they might seem attractive for finding cheap homeowners insurance, these policies often have significant limitations and aren’t suitable for most homeowners who actually want meaningful protection.
Optional Coverages and Endorsements
Standard policies don’t cover everything, and that’s where endorsements become valuable. Think of them as insurance add-ons that customize your policy to your specific needs.
Sewer Backup Coverage protects against damage from sewer or drain backups, which can be particularly important for older homes or properties in areas with aging infrastructure. This coverage is especially relevant in rural areas where septic systems or older drainage systems might be more prone to problems.
Overland Water Damage covers flooding from surface water, which isn’t covered by standard policies. While it’s less comprehensive than full flood insurance, it provides protection against water damage from sources like heavy rainfall or snowmelt.
Identity Theft Protection helps with expenses related to identity theft, including legal fees and lost wages from time off work to resolve issues. In our increasingly digital world, this coverage is becoming more valuable.
Scheduled Personal Property provides broader coverage for valuable items like jewelry, art, or collectibles. It typically covers more perils than standard personal property coverage and doesn’t require a deductible, making it worthwhile for items you truly value.
For property owners with unique situations, you can learn about coverage options for hobby farms to see how specialized coverage might apply to your property.
Ensuring Full Coverage for Rebuilding Costs
One of the biggest mistakes homeowners make is confusing their home’s market value with its replacement cost. Your insurance should cover the cost to rebuild your home, not what you could sell it for. These are often very different numbers.
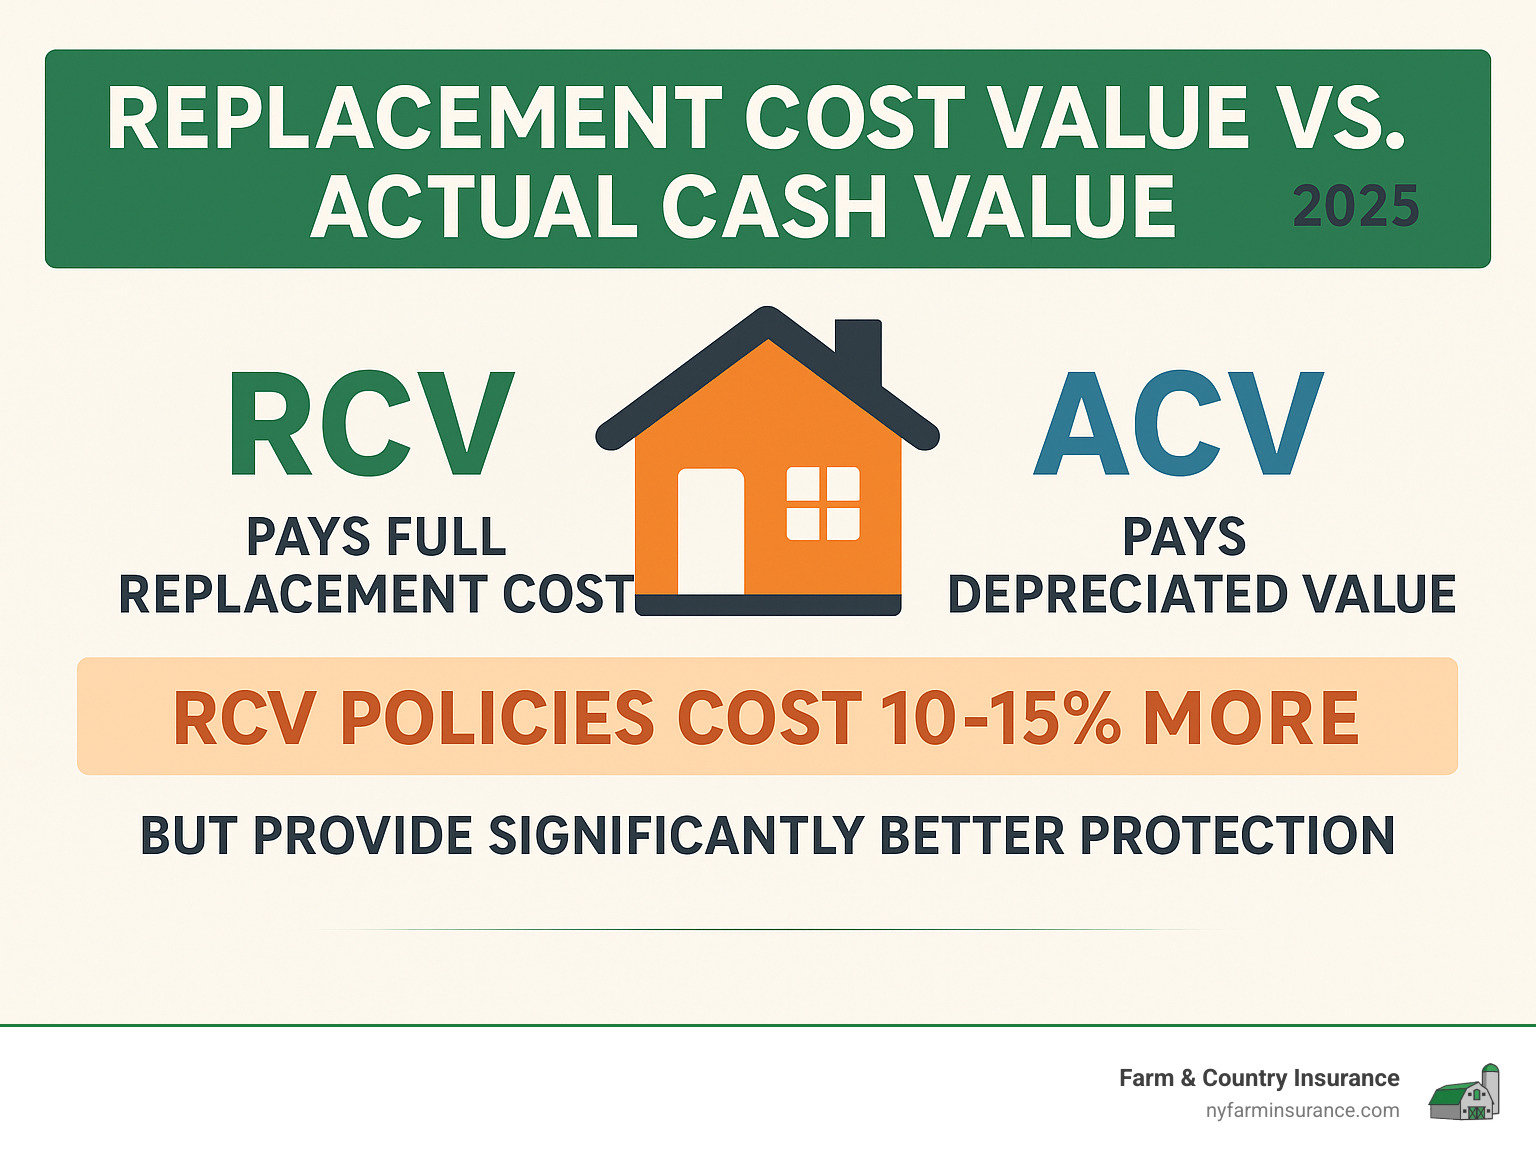
Replacement Cost Value (RCV) vs. Actual Cash Value (ACV) represents a crucial choice in your policy. RCV policies pay to rebuild or replace damaged property with new materials of similar quality. ACV policies pay the depreciated value of damaged property. While RCV policies cost 10-15% more upfront, they provide much better protection when you actually need to rebuild.
Guaranteed Replacement Cost coverage goes even further, paying to rebuild your home even if costs exceed your policy limits. This protection is valuable against inflation and unexpected construction cost increases. Given how construction costs have more than doubled since 2002, this coverage provides important peace of mind.
The 80% Rule is a coinsurance clause that most policies include, requiring you to insure your home for at least 80% of its replacement value to receive full coverage for partial losses. If you’re underinsured, the insurer will only pay a proportional amount of your claim. This can be financially devastating if you’re significantly underinsured.
Avoiding Underinsurance requires regularly reassessing your dwelling coverage, especially after renovations or when construction costs increase in your area. Consider getting a professional appraisal to ensure adequate coverage, particularly if you haven’t updated your coverage limits in several years.
At Farm & Country Insurance, we’ve seen too many homeowners find they’re underinsured only after filing a claim. For more information about this critical issue, read about avoiding underinsurance.
Conclusion
Finding cheap homeowners insurance doesn’t mean sacrificing protection – it means being strategic about how you shop, what coverage you choose, and how you manage risk. The key strategies we’ve discussed can save you hundreds or even thousands of dollars annually while ensuring you have adequate protection for your most valuable asset.
Remember these essential points:
- Shop around annually and compare quotes from multiple providers
- Increase your deductible to a level you can afford
- Bundle policies when it makes financial sense
- Install safety and security devices to qualify for discounts
- Maintain good credit to access better rates
- Choose replacement cost coverage over actual cash value
- Work with financially stable insurers with good customer service ratings
At Farm & Country Insurance, we understand that every homeowner’s situation is unique, especially for those with rural properties or specialized needs. Since 1984, we’ve helped New York homeowners in areas like Auburn, Moravia, Sterling, and throughout Cayuga County find the right balance between affordability and comprehensive protection.
For properties with unique risks or specialized needs, expert guidance becomes even more crucial. Whether you’re dealing with a rural property, hobby farm, or standard homeowner situation, the right insurance professional can help you steer the complexities and find coverage that protects your investment without overpaying.
The insurance market will continue to evolve, but the fundamental principles of finding affordable coverage remain constant: be proactive, shop regularly, understand your risks, and choose coverage that matches your needs and budget. Your home is likely your largest investment – protecting it properly while managing costs is not just smart financial planning, it’s essential for your long-term financial security.
For specialized guidance on farm and rural property insurance needs, explore our comprehensive guide to farm homeowners insurance to ensure you have the protection you need at a price you can afford.