
Commercial Agribusiness Insurance 101
Why Agricultural Business Insurance Is Essential for New York Farmers
Agricultural business insurance is a specialized type of coverage designed to protect farms and agribusinesses from the financial losses that come with farming’s unique risks. Here’s a quick overview of what it typically covers:
| Coverage Type | What It Protects |
|---|---|
| Property insurance | Barns, silos, equipment, dwellings |
| General liability | Injuries to guests, customers, or third parties |
| Crop insurance | Yield losses from weather, pests, or disease |
| Livestock coverage | Mortality, disease outbreaks, loss of income |
| Workers’ compensation | Employee injuries on the farm |
| Business interruption | Lost income during forced shutdowns |
| Environmental liability | Pesticide runoff, manure contamination |
Farming has always been hard work. But in New York State, dairy farmers, crop growers, and mixed operations face a uniquely demanding combination of risks — unpredictable weather, rising equipment costs, livestock health threats, and an increasingly complex regulatory environment.
The gap between a manageable setback and a financial disaster is often a single bad season, one equipment fire, or one injured visitor.
Standard business or homeowner’s insurance simply wasn’t built for this reality. Farm operations blur the line between home and business, between employee and family member, between local market and regulated food supplier. That’s why agricultural businesses need coverage that’s purpose-built for the way farms actually work.
I’m Casey Love, the founder of Farm & Country Insurance, an independent agency based in Honeoye Falls, NY that specializes exclusively in agricultural business insurance. Raised in a farming community and working daily with New York farmers of all sizes, I’ve seen what’s at stake when coverage falls short — and what’s possible when it’s done right.
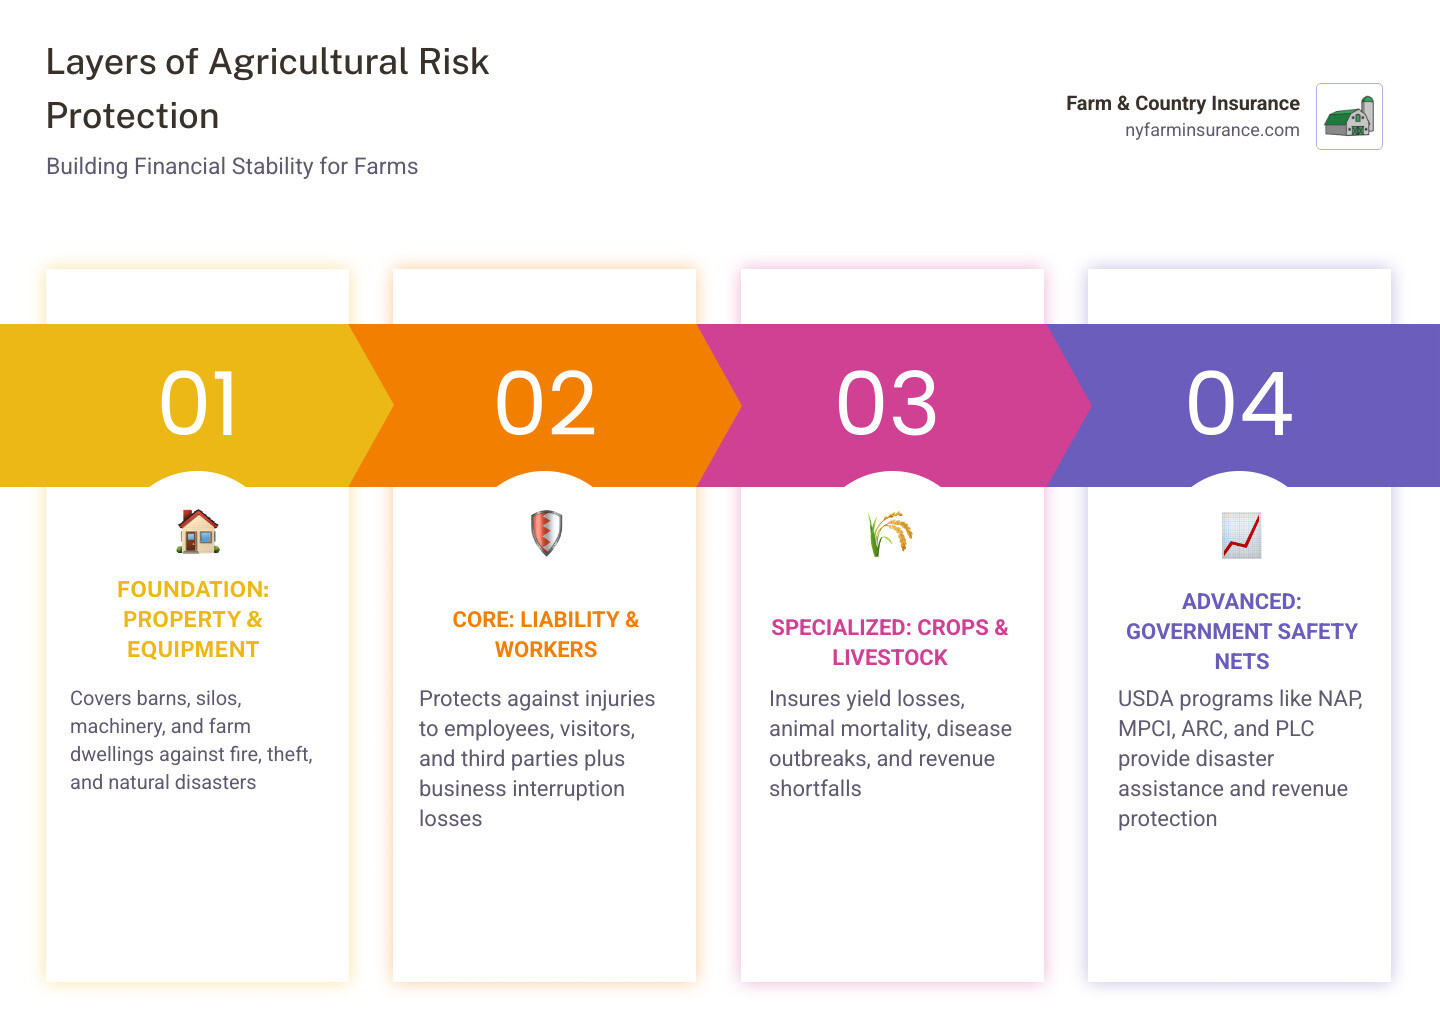
Quick Agricultural business insurance terms:
Essential Types of Agricultural Business Insurance
When we sit down with a producer in Auburn or Owasco, the first thing we explain is that Agricultural Business Insurance isn’t just one policy; it’s a toolkit. Each tool is designed to fix a specific problem that could otherwise sink your operation.


General Liability
This is your first line of defense. It protects you if someone—a delivery driver, a customer at your farm stand, or even a trespasser—gets hurt on your property. It also covers property damage you might accidentally cause to others. For example, if a stray cow wanders onto a neighbor’s property in Sennett and destroys their landscaping, your liability coverage is what keeps that neighborly dispute from becoming a financial nightmare.
Business Insurance for Farms
Beyond simple liability, Business Insurance for Farms addresses the commercial nature of your work. If you are processing milk, bagging grain, or running a u-pick apple orchard in Sterling, your needs shift from “hobby” to “enterprise.” This coverage ensures that your specific business activities are recognized and protected.
Property Coverage
Your farm is likely your biggest asset. This covers your “unscheduled” and “scheduled” property. Unscheduled property might include smaller tools and supplies, while scheduled property refers to high-value items like your combine or your primary residence. We recommend insuring dwellings for between 80 and 100 percent of their reconstruction value to ensure you can actually rebuild after a total loss.
Workers’ Compensation
In New York, protecting your people is both a moral and legal obligation. Farming is statistically one of the most dangerous jobs in the country. Even if you run a safe operation, accidents happen. Workers’ comp covers medical bills and lost wages for employees injured on the job. We often see “gray areas” with CSA labor or seasonal harvesters; our advice is always to carry coverage for anyone performing work on your behalf to avoid massive personal liability.
Business Interruption and Inland Marine
If a fire levels your milking parlor, you don’t just lose the building; you lose the daily income from your herd. Business interruption insurance helps cover lost profits and fixed expenses like taxes and loan payments while you get back on your feet. Meanwhile, Insurance for Farm Business often includes “Inland Marine” coverage—a fancy term for protecting equipment and cargo while it’s in transit. If you’re hauling a load of hay through Throop and the trailer flips, Inland Marine has your back.
Specialized Coverage for Livestock and Crops
For many of our clients, the real value of the farm isn’t in the dirt or the tractor—it’s in what they grow. Agribusiness thrives on the health of its biological assets.
- Mortality Insurance: This is essentially life insurance for high-value animals. Whether you have a prize bull or a high-producing dairy herd, mortality insurance protects you against the death of livestock due to accidents, fire, or even lightning strikes.
- Yield and Revenue Protection: These are the two pillars of crop insurance. Yield protection covers you if weather (like a late frost in Cayuga County) kills your crop. Revenue coverage goes a step further, protecting you if the market price for your grain or fruit drops significantly, even if your harvest was decent.
- Disease Outbreaks: A single case of avian flu or a localized livestock pandemic can lead to a forced cull. Specialized endorsements can help bridge the gap when your entire “inventory” is lost to disease.
Protecting Farm Infrastructure and Vehicles
Your barns, silos, and outbuildings are the backbone of your workflow. Farm Business Insurance needs to account for the fact that a 100-year-old bank barn is harder to replace than a modern pole barn. We look at “Functional Replacement Cost,” which allows you to replace an older, obsolete structure with a modern equivalent that serves the same purpose.
Don’t forget the fleet. Whether it’s a heavy-duty pickup used for farm chores or a fleet of delivery trucks, commercial auto insurance is vital. Standard personal auto policies often exclude coverage if the vehicle was being used for “business purposes” at the time of an accident.
Assessing Risks: From Weather Events to AgTech
Risk assessment is the process of looking at your farm and asking, “What’s the worst that could happen?” In New York, we deal with everything from Lake Ontario-effect snow crushing barn roofs to mid-summer droughts.
Climate Volatility and Commodity Fluctuations
We’ve seen weather patterns become increasingly erratic. A “hundred-year flood” seems to happen every five years now. Agribusiness Insurance must be flexible enough to handle these shifts. Simultaneously, global trade policies can cause commodity prices to swing wildly. We help farmers use insurance as a hedge against these market forces.
The Rise of AgTech
Modern farming is high-tech. From smart tractors and GPS-guided harvesters to drones surveying orchards in Venice, technology is everywhere. But with Agricultural Business Insurance, new tech brings new risks:
- Data Inaccuracies: If a sensor fails and applies the wrong amount of fertilizer, who is liable for the ruined crop?
- Collisions: A smart tractor losing its GPS signal could collide with a fence, another vehicle, or even livestock.
- Cyber Liability: If your farm management software is hacked and your operational data is held for ransom, do you have the coverage to recover?
Environmental and Product Liability
Environmental stewardship is a huge part of being a New York farmer. However, accidents like manure lagoon leaks or pesticide runoff into a local creek can lead to massive fines and cleanup costs. Small Farm Business Insurance should include environmental liability to cover these “pollution” events.
If you sell directly to consumers—whether at a farmers market in Auburn or through a CSA—product liability is non-negotiable. If a customer gets sick from a foodborne illness linked to your produce, the legal fees alone could bankrupt a small farm. Product recall insurance is also becoming a requirement for many wholesalers, covering the cost of pulling your products off shelves if a contamination issue is suspected.
Government Programs and Risk Management Support
While private insurance is crucial, the USDA Risk Management Agency provides a federal safety net that every farmer should understand. These programs are often administered by private agents like us, but they are subsidized by the government to keep premiums affordable.
Comparing Federal Support Programs
Managing risk often involves a combination of private policies and USDA programs. Here is how the main options stack up:
| Program | Best For | Key Feature |
|---|---|---|
| NAP | Non-insurable crops | Provides basic coverage for crops where MPCI isn’t available. |
| ARC | Price & Yield protection | Triggers payments when actual crop revenue falls below a guaranteed level. |
| PLC | Price protection | Triggers payments when the effective price of a crop falls below a reference price. |
| DMC | Dairy producers | Offers protection when the margin between milk prices and feed costs narrows. |
The USDA Farm Service Agency also offers the Noninsured Crop Disaster Assistance Program (NAP). For a basic administrative fee of about $300 per crop, you can get a “catastrophic” level of coverage. While it won’t make you rich, it provides enough of a floor to help you survive a total loss. You can find more details in the Fact sheets on USDA FSA programs.
Financial Safety Nets for New York Producers
New York producers can also access the Advance Payments Program, which provides low-interest cash advances of up to $1 million to help with cash flow during the growing season.
For diversified farms that grow a little bit of everything—common in the Finger Lakes region—Whole-Farm Revenue Protection (WFRP) is a game-changer. Instead of insuring every single tomato and ear of corn separately, WFRP insures the total revenue of the entire farm. This is one of the most important Farm Insurance Basics for modern, diversified operations.
Customizing Your Policy: Valuation and Limits
One of the biggest mistakes we see is “set it and forget it” insurance. A policy written in 1994 isn’t going to cover the cost of a modern milking parlor in 2024.
Understanding Valuation Methods
How your property is valued determines how much you get paid after a claim:
- Replacement Cost Value (RCV): Pays the cost to replace the item with a new one of similar quality.
- Actual Cash Value (ACV): Pays the replacement cost minus depreciation. If your 20-year-old tractor burns, ACV only pays what that old tractor was worth the day before the fire.
- Functional Replacement Cost (FRC): As mentioned, this is great for older barns. It pays to build a functional modern building rather than trying to replicate 19th-century timber framing.
Determining Proper Coverage Limits
Determining your limits requires a deep dive into your books. We look at:
- Reconstruction Costs: What would it cost to rebuild your primary structures today?
- Payroll Audits: Your workers’ comp premiums are based on your payroll. If you hire more seasonal help this year, you need to adjust your limits.
- Inventory Fluctuations: A grain bin is worth a lot more when it’s full in October than when it’s empty in July. Your Agricultural Business Insurance should account for these seasonal peaks.
Adding an Umbrella Liability policy is often the most cost-effective way to get extra protection. It sits on top of your general liability and auto policies, providing an extra $1 million or more of coverage for a relatively small premium.
Frequently Asked Questions about Agricultural Business Insurance
How does farm insurance differ from standard commercial property insurance?
Farm insurance is a “hybrid.” A standard commercial policy assumes you go to an office and then go home. On a farm, your “office” is 50 feet from your bedroom. Farm insurance combines personal residential coverage with commercial business coverage into one seamless package. It also includes specialized endorsements for things like “custom farming” (doing work for others) that a standard business policy would exclude.
What is the recommended coverage for Agricultural business insurance?
There is no one-size-fits-all answer, but every farm should have at least:
- $1 million in General Liability.
- Property coverage at RCV for essential buildings.
- Workers’ comp (if you have any employees).
- Crop or Revenue insurance (USDA programs). The best way to determine your specific needs is through a professional Small Farm Business Insurance risk assessment.
Why is product liability vital for Agricultural business insurance?
In today’s litigious world, one bad batch of cider or a contaminated bag of salad greens can lead to a massive lawsuit. Product liability doesn’t just pay the settlement; it pays for your legal defense. Even if the claim is frivolous, the cost of proving you did nothing wrong can be devastating without insurance.
Conclusion: Protecting the Future of New York Agriculture
At the end of the day, agricultural business insurance isn’t just about protecting buildings and tractors; it’s about protecting your legacy. Whether you are a multi-generational dairy operation in Cayuga County or a new organic vegetable starter in Seneca Falls, the risks are real, but they are manageable.
Since 1984, Farm & Country Insurance has been more than just a provider; we’ve been a partner to the New York farming community. We understand the smell of the barn, the stress of the harvest, and the pride of a job well done. Our specialized New York expertise ensures that your coverage is as hardworking as you are.
Don’t wait for a “hundred-year storm” to find out if your policy is up to par. Let’s sit down and look at your operation from every angle to ensure your farm remains viable for the next generation.
Contact a farm insurance specialist at Farm & Country Insurance today for a comprehensive risk assessment.