
Why Smart Farmers Don’t Let Weather Decide Their Future
Crop damage insurance protects farmers against financial losses from natural disasters, adverse weather conditions, and other unavoidable perils that can destroy crops and devastate farm income. Here’s what you need to know:
• Federal Crop Insurance Program (FCIP) covers 494 million acres across the U.S., protecting 81% of eligible farmland
• Multiple coverage types including Multi-Peril Crop Insurance (MPCI), crop-hail, and revenue protection plans
• Premium subsidies from the federal government make coverage affordable, with farmers paying only a portion of actual costs
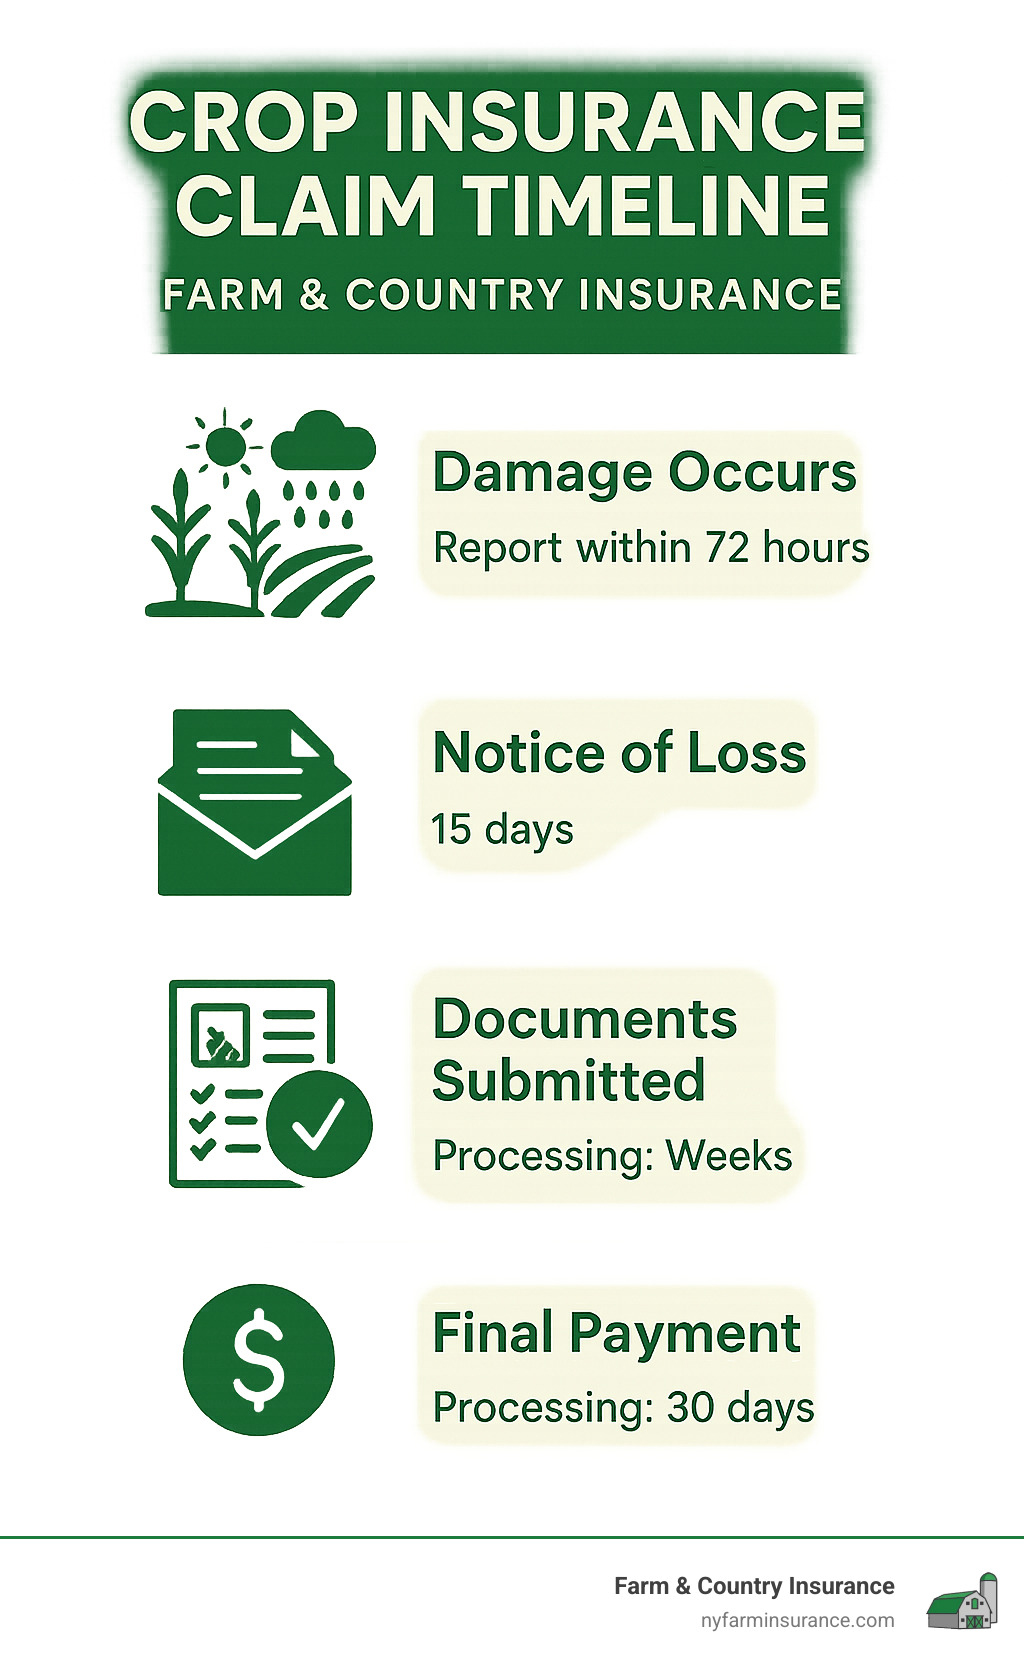
• Claims process requires reporting damage within 72 hours and written follow-up within 15 days
• Indemnity payments compensate for yield losses when actual production falls below guaranteed levels
Farming has always been unpredictable. But today’s farmers face more extreme weather patterns, rising input costs, and volatile commodity prices that can wipe out an entire season’s work in hours. As one North Carolina farmer put it after Hurricane Helene: “Many farmers lost an entire season’s worth of income when flood waters inundated fields.”
The numbers tell the story. Since 2000, drought and high temperatures have caused 43.7% of all crop insurance claims, while excess moisture accounts for another 25.6%. With annual indemnity payments increasing by 19.6% per year, smart farmers know they can’t afford to gamble with Mother Nature.
More than 90% of farmers who buy crop insurance choose Multi-Peril Crop Insurance, which covers over 120 different crops against everything from hail and drought to disease and wildlife damage. But understanding which coverage fits your operation — and how to file claims correctly — can mean the difference between surviving a bad year and losing your farm.
I’m Casey Love, owner of Farm & Country Insurance, and I’ve spent decades helping New York farmers steer crop damage insurance options that protect their livelihoods. Having grown up in a farming community, I understand that the right coverage isn’t just about compliance — it’s about keeping your operation viable when disaster strikes.

Key crop damage insurance vocabulary:
– agricultural equipment insurance
– agricultural land insurance
– farm fire insurance

Understanding Crop Damage Insurance
Think of crop damage insurance as a partnership between you, your insurance provider, and Uncle Sam. The Federal Crop Insurance Program (FCIP) creates this unique three-way relationship where the government backs the program, private companies like Farm & Country Insurance handle your day-to-day needs, and you get the protection your operation deserves.
Here’s what makes this system work so well: the Federal Crop Insurance Corporation (FCIC) provides the financial backing, which means your coverage is rock-solid. Meanwhile, approved insurance providers deliver the personal service and local expertise you need when disaster strikes. It’s the best of both worlds — government stability with private sector responsiveness.
The program operates on a contract basis with one important rule: you must insure all eligible acres of each crop you grow in a county. This might seem restrictive, but it actually keeps costs down for everyone by preventing farmers from only insuring their riskiest fields. Premium subsidies are the real game-changer here — in 2022, the government covered $11.98 billion in premium costs, making quality protection affordable whether you farm 50 acres or 5,000.
What Is Crop Damage Insurance?
Crop damage insurance is your financial safety net when Mother Nature doesn’t cooperate. The indemnity concept is beautifully simple: when covered disasters reduce your actual yield or revenue below what’s guaranteed, you get paid to help offset that loss. No complex formulas to decode — just straightforward protection when you need it most.
The covered perils read like a farmer’s worry list: drought, excess moisture, hail, wind, frost, fire, and plant diseases top the charts. But the coverage goes deeper, protecting against insect damage, wildlife raids on your crops, and even irrigation equipment failures. What sets this apart from regular insurance is that it’s built specifically around agricultural risks — the kinds of problems that can devastate a harvest despite your best management practices.
How Does Crop Damage Insurance Work?
Your journey starts with choosing a coverage level, typically anywhere from 50% to 85% of your expected yield or revenue. Think of it as choosing how much of a safety net you want — higher coverage means higher premiums, but also better protection when disaster strikes. You’ll also select your price election, which sets the dollar value used to calculate both your guarantee and any payments you might receive.
Unit structure might sound technical, but it’s really about how your losses get calculated. With basic units, all your acreage of the same crop in a county gets lumped together. Optional units let you separate different fields, which can boost your chances of receiving payments since losses are figured separately for each unit. Enterprise units combine all your acreage across multiple counties — you’ll pay lower premiums but face higher deductibles.
Policy deadlines are absolutely critical and unforgiving. For most crops, you must buy coverage before you start planting. Miss that deadline, and you’re essentially farming without a safety net until next season. More info about how coverage works can help you understand exactly when you need to act for your specific crops and location.
Types of Policies & When to Use Them
Finding the right crop damage insurance policy can feel like navigating a maze. After nearly four decades helping New York farmers, I’ve learned that the “best” policy is simply the one that matches your specific operation. Let me walk you through your options so you can make the choice that keeps your farm protected.
The beauty of today’s crop insurance landscape is that you don’t have to settle for one-size-fits-all coverage. Whether you’re growing 500 acres of corn or running a diversified vegetable operation, there’s likely a policy designed for your situation.
| Policy Type | Best For | Coverage | Premium Cost | Purchase Window |
|---|---|---|---|---|
| MPCI | Most farmers | Yield losses from multiple perils | Moderate (subsidized) | Before planting |
| Crop-Hail | Hail-prone areas | Hail damage only | Low | Anytime during season |
| Revenue Protection | Price-sensitive crops | Yield and price losses | Higher (subsidized) | Before planting |
Multi-Peril Crop Damage Insurance (MPCI)
Think of MPCI as your farm’s all-weather jacket — it’s the foundation that most farmers build their risk management around. This federally backed program protects over 120 different crops against everything Mother Nature throws at them, from drought and hail to disease and wildlife damage.
What really sets MPCI apart is its comprehensive approach. If early-season damage forces you to replant, the policy often includes replant incentives to help cover those unexpected costs. I’ve seen this feature save farmers thousands when late frosts or heavy rains wipe out newly planted fields.
The program uses your Actual Production History to set yield guarantees based on your farm’s track record. New farmers don’t get left out in the cold — if you don’t have enough history, the program provides transitional yields based on what other farms in your county typically produce.
More info about MPCI explains how this cornerstone coverage works. For most New York operations growing corn, soybeans, hay, or specialty crops, MPCI delivers the most bang for your premium buck.
Supplemental Crop Damage Insurance: Crop-Hail & Endorsements
Here’s where things get interesting. While MPCI covers hail damage, crop-hail insurance fills gaps that can make a real difference to your bottom line. These private policies typically carry low or no deductibles and can be purchased anytime during the growing season — talk about flexibility.
The timing advantage is huge. If weather patterns turn nasty mid-season, you can add hail protection immediately rather than crossing your fingers and hoping for the best. I’ve had farmers call me in June when storm systems start building, knowing they can still protect their investment.
Crop-hail insurance also pays on smaller losses that might not trigger MPCI thresholds. Even moderate hail damage can hurt quality and marketability, especially for specialty crops where appearance matters.
Many smart farmers use crop-hail strategically — buying coverage when forecasts show increased storm activity, then letting it lapse during calmer periods. It’s like having an umbrella you can pull out when clouds gather.
Revenue Protection & Margin Products
Sometimes good yields don’t translate to good income, especially when market prices take a nosedive right at harvest. Revenue protection policies guard against both yield losses and price declines, giving you dual protection when volatility threatens your farm’s financial health.
These policies establish a revenue guarantee based on your production history and projected prices set before planting. If harvest prices climb higher than projected prices, many policies include a harvest price option that uses the better price to calculate your guarantee.
This feature proves invaluable when national bumper crops depress prices just as your local yields suffer from weather problems. You’re protected from the double whammy of poor yields and poor prices.
Margin protection products take this concept even further by factoring in production costs. These area-based policies trigger payments when the gap between commodity prices and input costs shrinks below profitable levels, regardless of what happens on your specific farm.
Whole-Farm & Micro Farm Options
If you’re running a diversified operation, traditional crop damage insurance can feel like trying to fit a square peg in a round hole. Whole-Farm Revenue Protection solves this puzzle by insuring your entire operation’s revenue under one umbrella policy.
This approach works beautifully for farms mixing crops, livestock, direct sales, and even agritourism. Instead of juggling multiple commodity-specific policies, you get one policy that covers everything from your field crops to your farm stand sales.
WFRP handles operations with revenue up to $17 million, while the Micro Farm option serves smaller operations with revenue up to $350,000. Both calculate guarantees based on your whole-farm revenue history, providing flexibility that traditional policies simply can’t match.
For New York’s incredibly diverse agricultural landscape — from Finger Lakes grape growers to Hudson Valley vegetable farms — whole-farm coverage often provides better protection than trying to piece together a patchwork of individual policies. At Farm & Country Insurance, we’ve helped many diversified operations find that this simpler approach actually gives them more comprehensive protection.
Coverage, Costs & Eligibility Explained
When Mother Nature throws her worst at your crops, crop damage insurance steps in to cover losses from natural disasters you simply can’t prevent through good farming alone. But understanding exactly what’s covered — and what isn’t — can save you from costly surprises when filing a claim.
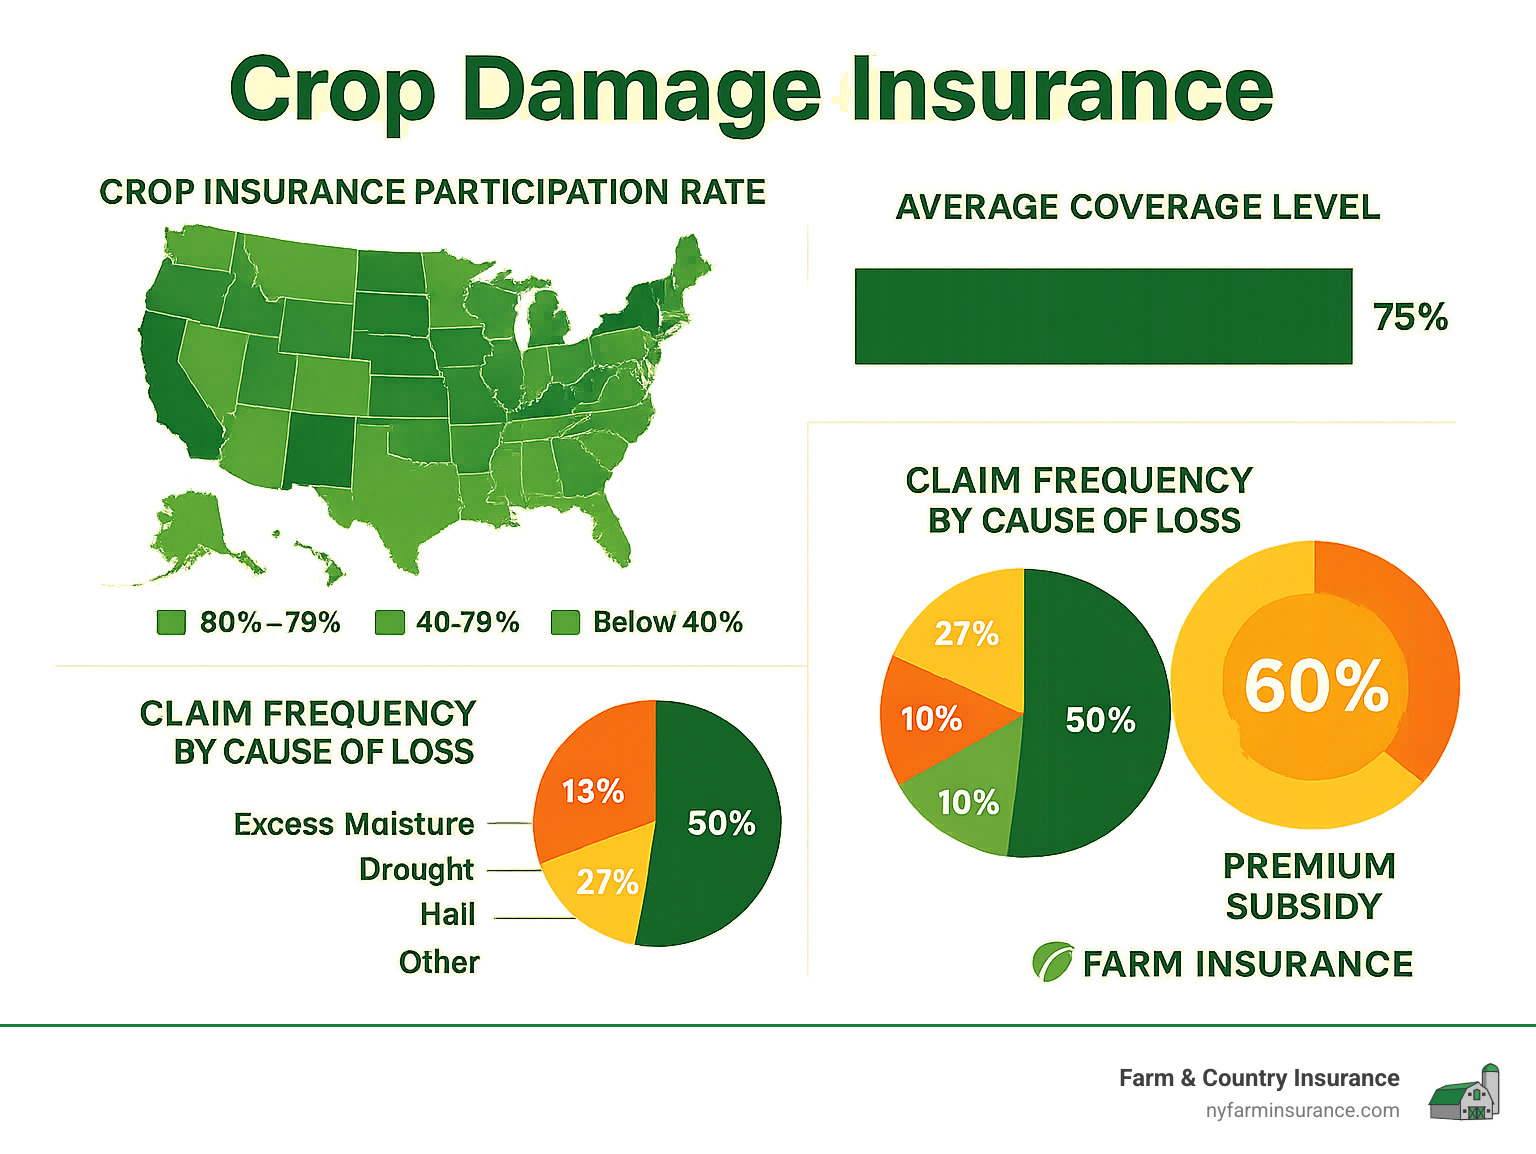
The statistics tell a sobering story. Drought has caused 43.7% of all crop insurance claims since 2000, while excess moisture accounts for another 25.6%. It’s a reminder that farming means dealing with too little water, too much water, and rarely just the right amount. Other covered perils include freeze damage, hail, wind, fire, plant diseases, insect infestations, and wildlife destruction.
Catastrophic (CAT) coverage provides a basic safety net at 50% of your average yield and 55% of the commodity price. Farmers pay only a $655 administrative fee per crop per county for this protection. While CAT coverage won’t make you whole after a major loss, it prevents total financial disaster.
Higher coverage levels require premium payments but offer substantially better protection. With Scientific research on climate impacts showing increasingly volatile weather patterns, many farmers find the extra premium cost worthwhile for the peace of mind.
At Farm & Country Insurance, we’ve seen how climate change affects New York agriculture. The farmers who sleep best at night are those with coverage levels that match their risk tolerance and financial situation. Crop Insurance: What You Need to Know breaks down these decisions in practical terms.
Who Can Buy Crop Damage Insurance?
Any farmer with an insurable interest in their crops can purchase crop damage insurance. That means you’ll suffer financially if the crop gets damaged — whether you own, rent, or sharecrop the land. The program welcomes everyone from weekend market gardeners to large commercial operations.
Conservation compliance requirements apply to all participants. You must protect wetlands and follow conservation practices on highly erodible land according to USDA standards. These rules might seem like red tape, but they help preserve the farmland that feeds us all.
Beginning farmers get special treatment under the program. The government recognizes that new farmers face enough challenges without being penalized for lacking production history. Beginning farmers often receive transitional yields that exceed county averages, plus additional premium subsidies to help get their operations established.
Organic producers can insure their crops at organic price levels, reflecting the premium markets they serve. This recognition of organic farming’s unique economics helps sustainable operations access appropriate protection.
The program does require you to insure all eligible acreage of each crop in a county. You can’t just insure your riskiest bottom ground while leaving your productive hilltop fields unprotected. This all-or-nothing approach keeps the program actuarially sound and prevents cherry-picking that would drive up costs for everyone.
How Premiums Are Calculated
Premium calculations start with your Actual Production History (APH), which establishes what the insurance company expects your fields to yield. The Risk Management Agency uses sophisticated actuarial models to set base premium rates for each crop, county, and coverage level based on historical loss data.
Your individual premium gets adjusted through a continuous rating formula that considers your farm’s loss history. Farms with fewer claims pay lower rates, while those with more frequent losses pay higher premiums. This system rewards good farming practices and appropriate risk management — something we always appreciate seeing.
Coverage level selection dramatically affects your premium costs. Jumping from 65% to 75% coverage might increase your premium by 50% or more, but it also significantly improves your protection against losses. The key is finding the sweet spot that provides adequate protection without breaking your budget.
Premium subsidies make the program accessible to farmers of all sizes. The federal government pays 38% to 80% of total premiums depending on your coverage level. Higher coverage levels receive lower subsidy percentages, but the dollar amounts can still be substantial.
Actuarial fairness means premiums should reflect actual risk over time. Areas with higher loss frequencies pay higher base rates, while lower-risk regions enjoy more affordable coverage. This geographic rating ensures the program remains financially sustainable while providing protection where farmers need it most.
What Isn’t Covered?
Crop damage insurance won’t bail you out from losses you could have prevented through proper farming practices. Poor seed quality, inadequate pest control, insufficient fertility, or planting at the wrong time won’t trigger coverage. The program protects against acts of nature, not management mistakes.
Preventable losses include damage from failure to follow generally accepted farming practices for your area. If everyone else in your county sprays for a particular pest and you skip the treatment, resulting losses likely won’t be covered. The adjuster will investigate whether reasonable farming practices could have prevented the damage.
Market speculation doesn’t qualify for insurance protection. If you plant hoping for $7 corn and prices drop to $4, that’s a business risk, not an insurable loss. The program protects your ability to produce crops, not your ability to predict commodity markets.
Uninsurable practices can void your entire policy. Using experimental varieties without approval, planting way outside recommended dates, or ignoring university extension recommendations creates problems. We always recommend discussing your farming practices with your agent before making major changes to ensure they align with policy requirements.
The bottom line? Crop damage insurance covers what you can’t control but won’t pay for what you should have managed better. That’s fair — and it keeps the program focused on protecting farmers from genuine natural disasters rather than poor decision-making.
Claims, Documentation & Farmer Responsibilities
When Mother Nature delivers her worst punch, filing your crop damage insurance claim correctly becomes your lifeline back to financial stability. I’ve watched farmers lose thousands simply because they missed a deadline or forgot to document damage properly. The good news? Following the right steps ensures you get every dollar you deserve.
The 72-hour notification rule isn’t negotiable. From the moment you find damage — whether it’s hail-shredded corn or drought-stressed soybeans — you have exactly 72 hours to contact Farm & Country Insurance. This clock starts ticking when you first see the damage, not when the weather event happened. Miss this window, and you could jeopardize your entire claim.
After Hurricane Helene devastated farms across the Southeast, we saw how proper claims handling made all the difference. Farmers who followed correct procedures, as outlined in Emergency Procedures for Crops Damaged by Hurricane Helene, received faster settlements and full compensation. Those who didn’t? They faced months of delays and reduced payments.
The 15-day written follow-up requirement gives you time to assess damage more thoroughly. But don’t wait — start gathering documentation immediately. Your adjuster will need representative samples of damaged crops, detailed planting records, and clear photographs showing both damaged and healthy areas for comparison.
Step-by-Step Claim Filing
Your first call should always be to Farm & Country Insurance, not your neighbor or the coffee shop crowd. We’ll walk you through completing the Notice of Loss (NOL) form and coordinate the adjuster inspection to fit your schedule. Don’t try to handle this alone — our experience helps ensure nothing falls through the cracks.
When the adjuster arrives, be there in person. They need to understand your specific farming practices and how the covered event disrupted normal operations. Point out affected areas, explain your typical yields, and share any unusual circumstances that might affect their assessment.
Never destroy, disk, or replant damaged crops without written authorization from your adjuster. I’ve seen eager farmers lose claim eligibility by cleaning up fields too quickly. The adjuster needs to see the actual damage, and representative samples must remain intact until final settlement.
Recordkeeping & Evidence You’ll Need
Smart farmers start building their claim file on planting day, not after disaster strikes. Your planting records should include seed variety, planting dates, and purchase receipts. These documents prove what you planted and when, establishing the foundation for your claim.
Digital photographs tell the story your words can’t. Take pictures throughout the growing season showing normal crop development, then capture extensive damage photos from multiple angles. Cloud storage protects these critical images from the same storms that damage your crops.
Input receipts for fertilizer, seed, and chemicals demonstrate your investment in the crop. Combined with your Schedule F tax records, this documentation paints a complete picture of your operation for the adjuster. The more thorough your records, the smoother your claim process becomes.
Indemnity Calculation & Payout Timing
Understanding how your payment gets calculated takes the mystery out of claim settlements. For yield-based policies, the indemnity formula is straightforward: your guaranteed yield minus actual production, multiplied by your elected price. Revenue policies add complexity by considering harvest price options that might increase your final payment.
Most indemnity payments arrive within 30 days of settlement, though complex claims requiring additional documentation may take longer. We track every payment and stay on top of any delays to ensure you receive your money as quickly as possible.
Small losses below your deductible won’t trigger payments, but they still affect your loss history for future premium calculations. A Quick Start Guide to Crop Insurance Options helps you understand when filing claims makes financial sense for your long-term risk management strategy.
The claims process doesn’t have to be overwhelming. With proper preparation and Farm & Country Insurance guiding you through each step, you can focus on getting your operation back on track while we handle the paperwork.
Strategic Risk Management & Future Trends
The landscape of crop damage insurance is changing faster than a summer thunderstorm. Climate change brings more extreme weather events, while new technologies like precision agriculture generate data that could completely transform how we assess and price farm risks. At Farm & Country Insurance, we’ve watched these trends develop over nearly four decades, and we know farmers need to stay ahead of the curve.
One trend we can’t ignore is the mental health impact of crop losses. Losing an entire season’s work to weather doesn’t just hit your bank account — it hits your heart. The stress of dealing with insurance claims while watching months of hard work wash away or wither in the field affects farming families for years. Resources like the North Carolina Farm Help Line at 1-844-325-3276 provide 24/7 support for farmers dealing with crop loss trauma and insurance stress.
Looking beyond our borders, other countries handle agricultural risk differently than the U.S. While we emphasize individual farm coverage with hefty premium subsidies, places like Canada focus more on area-based insurance products and whole-farm approaches. These differences show there’s more than one way to protect farmers — and some of these international ideas are starting to influence American programs.
Integrating Crop Damage Insurance Into Whole-Farm Strategy
Crop damage insurance shouldn’t stand alone in your risk management toolbox. Think of it as the foundation of a house — essential, but you need walls and a roof too. Diversification across different crops, markets, and income sources reduces your overall farm risk and can actually lower your insurance costs through better loss experience.
Conservation practices like cover crops and buffer strips do double duty. They protect your soil and water while potentially reducing your crop insurance premiums through good farming practice discounts. We’ve seen farmers cut their premiums by 5-10% just by implementing proven conservation methods that also improve their long-term productivity.
Marketing contracts add another layer of protection by locking in prices before harvest. When you combine guaranteed prices with crop insurance that protects your yields, you create a revenue floor that helps ensure profitability even when Mother Nature throws her worst at you. Many successful farmers forward contract a portion of their expected production while maintaining full crop insurance coverage.
Don’t forget about the financial planning side. Building cash reserves to cover insurance deductibles ensures you can keep operating while waiting for claim settlements. Some farmers use specialized operating loans designed to bridge the gap between when losses occur and when insurance payments arrive. This planning prevents a cash crunch during already stressful times.
International Perspective: U.S. vs Canadian Programs
Our neighbors to the north handle agricultural insurance quite differently. Canada’s AgriInsurance system involves more direct government administration, with provincial governments sharing both premium costs and administrative duties with the federal government. Their coverage levels range from 50% to 90% of probable yields — similar to our options but delivered through a different structure.
Canadian programs often emphasize whole-farm approaches and include more livestock integration than our system. Their Sustainable Canadian Agricultural Partnership framework coordinates multiple risk management tools under one umbrella, potentially providing more seamless coverage for diversified operations like many New York farms.
These international differences highlight that there’s no single “right” way to structure agricultural risk management. While our system emphasizes private delivery with public backing, other models show alternative approaches that could influence future program evolution. Understanding these differences helps farmers appreciate the strengths of our current system while staying informed about potential improvements.
Frequently Asked Questions about Crop Damage Insurance
These are the questions I hear most often from farmers considering crop damage insurance or dealing with their first claim. After nearly four decades in the business, I’ve learned that getting straight answers upfront saves time and stress when you need your coverage most.
How soon must I report crop damage?
The clock starts ticking the moment you find damage — you have 72 hours to notify your insurance provider from when you first find it, not from when the damage actually occurred. This distinction matters more than you might think.
Let’s say a hailstorm hits your corn on Friday night, but you don’t check that field until Monday morning. Your 72-hour window starts Monday morning when you find the damage, giving you until Thursday morning to make that crucial phone call. Don’t wait to assess the full extent of the damage — call immediately when you find any covered loss.
The 15-day written follow-up requirement kicks in after your initial phone call. This written notice keeps your claim officially active in the system. Missing either deadline can jeopardize your entire claim, so we always recommend calling your Farm & Country Insurance agent the same day you find damage.
What documents secure the fastest claim approval?
Organization makes all the difference when filing claims. Complete planting records top the list — seed purchase receipts, planting dates, variety information, and seeding rates. These documents establish what you planted and when, forming the foundation of your claim.
Input invoices for fertilizer, pesticides, and other production expenses prove your investment in the crop. Clear photos of damage from multiple angles help adjusters understand the loss extent. Take pictures showing both damaged and undamaged areas for comparison — this visual evidence often proves more valuable than lengthy written descriptions.
Your Schedule F tax records and any field operation logs provide additional verification of your farming practices and historical production. Having these documents organized and easily accessible can cut weeks off your claim settlement time. We recommend keeping digital copies in cloud storage so weather disasters don’t destroy your documentation along with your crops.
Can I change coverage levels next season?
Absolutely — and you should review your coverage annually. You can adjust coverage levels, unit structure, and policy options each year during the enrollment period. Your farming operation evolves, and your insurance should evolve with it.
However, timing matters. Changes must be made before the sales closing date for each crop, which varies by commodity and location. Missing these deadlines means you’re stuck with current coverage for another full year, regardless of how your situation changes.
Your Farm & Country Insurance agent can review your current coverage each fall and recommend adjustments based on your operation’s growth, new crops you’re considering, or changes in your risk tolerance. Maybe you’ve expanded acreage and need higher coverage levels, or perhaps you’re nearing retirement and want to reduce premiums by lowering coverage. These annual reviews ensure your crop damage insurance stays aligned with your farming goals.
Conclusion

When you watch the sun rise over your fields each morning, you’re looking at more than just crops — you’re seeing your family’s future, your retirement plan, and years of hard work taking root. Crop damage insurance protects all of that from the weather extremes that can wipe out a season’s income in a single afternoon.
The reality is simple: farming without crop insurance is like driving without a seatbelt. You might be fine for years, but when disaster strikes, the consequences can end everything you’ve built. With drought causing nearly half of all crop losses and extreme weather events becoming more frequent, smart farmers know that hoping for good weather isn’t a business strategy.
We’ve walked through the basics of Multi-Peril Crop Insurance, explored supplemental options like crop-hail coverage, and explained how revenue protection shields you from both yield losses and price crashes. Whether you’re running a diversified vegetable operation that needs whole-farm coverage or growing traditional crops that fit standard MPCI policies, the right protection exists for your situation.
The claims process doesn’t have to be overwhelming when you understand the 72-hour reporting rule and keep proper documentation throughout the growing season. Your insurance agent is your advocate — we’re here to guide you through both policy selection and claims filing when Mother Nature doesn’t cooperate.
At Farm & Country Insurance, we’ve been helping New York farmers sleep better at night since 1984. We’ve seen operations saved by proper coverage and others devastated by gaps in protection. Our job isn’t just selling policies — it’s making sure you have custom coverage that fits your crops, your budget, and your peace of mind.
Federal premium subsidies make quality protection surprisingly affordable, often covering 60% to 80% of your actual premium costs. When you consider that crop insurance can mean the difference between surviving a bad year and losing your farm, it’s one of the smartest investments you’ll ever make.
Don’t let your profits wilt when you have options. More info about protecting your farm is just a phone call away. Farm & Country Insurance can help safeguard your harvest and keep your operation growing, no matter what challenges lie ahead.
The most expensive insurance you can have is the coverage you need but don’t carry. Let’s make sure that never happens to your farm.