
Securing Your Livelihood with Agricultural Insurance
Crop and livestock insurance is a critical financial safety net protecting farmers from losses due to natural disasters, market volatility, and other uncontrollable risks. Here’s a brief overview:
Key Agricultural Insurance Types:
- Crop Insurance: Protects against yield and revenue losses from weather, pests, and disease.
- Livestock Risk Protection (LRP): Guards against livestock price declines.
- Livestock Gross Margin (LGM): Protects against margin decreases from falling prices or rising feed costs.
- Dairy Revenue Protection (DRP): Offers quarterly revenue protection for milk producers.
How It Works:
- Policies are sold by approved providers in a public-private partnership.
- The federal government subsidizes a significant portion of the premiums.
- Coverage is available for over 100 crops nationwide.
- Claims are paid when losses exceed your chosen coverage level.
Farming in New York involves unpredictable weather and market swings. Whether you’re growing corn in the Finger Lakes or running a dairy in the North Country, crop and livestock insurance provides the peace of mind that your livelihood is protected.
At Farm & Country Insurance, we specialize in helping New York farmers steer the complexities of agricultural insurance. Our experience means we understand the unique challenges you face and can guide you to the right protection for your farm.
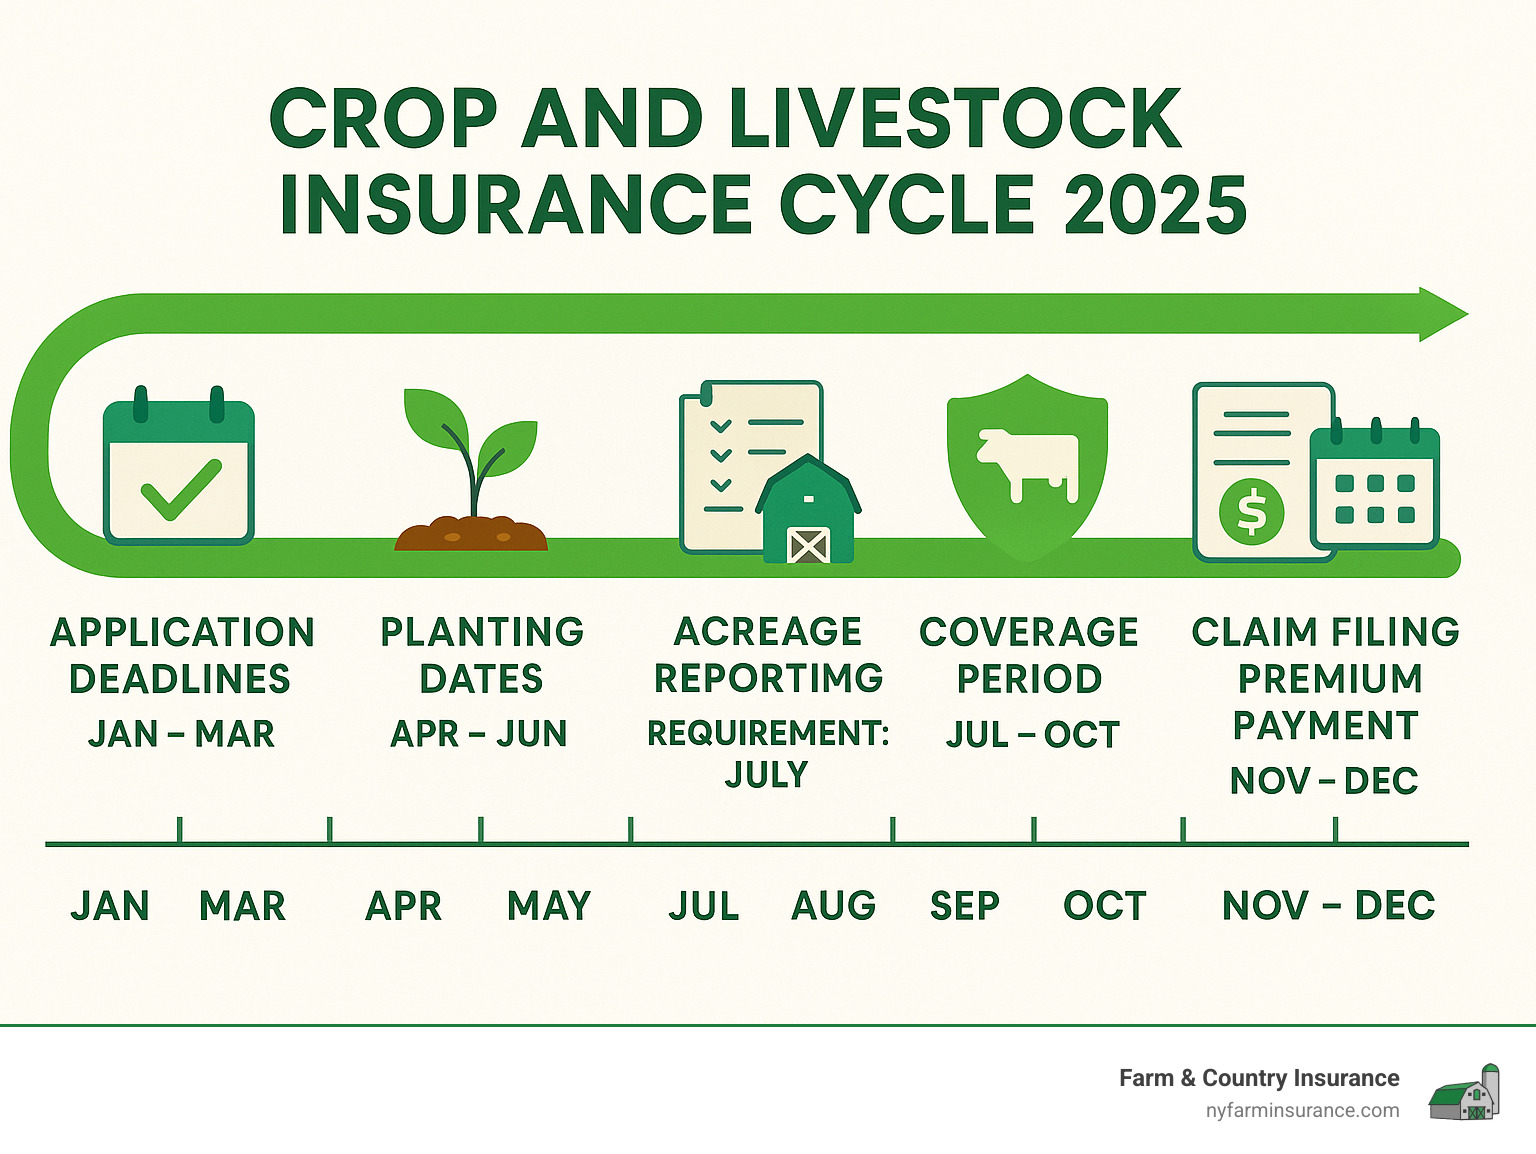
Key terms for crop and livestock insurance:
Understanding Crop Insurance: From Yields to Revenue
Unpredictable weather, pests, and diseases can devastate a season’s work. Crop insurance is a crucial risk management tool designed to protect your livelihood. The Federal Crop Insurance Program is a public-private partnership managed by the USDA’s Risk Management Agency (RMA). The government sets rules, backs policies, and subsidizes premiums, while Approved Insurance Providers (AIPs) like Farm & Country Insurance sell and service the policies. This structure ensures policies are custom to local needs with federal financial backing. With coverage available for over 100 different crops, it’s a vital economic backstop for producers nationwide, including farmers here in New York.

Key Types of Crop Insurance Policies
Crop insurance is not a one-size-fits-all solution. Several policy types address different risks.
Multi-Peril Crop Insurance (MPCI): The most common federal policy, MPCI offers broad coverage for losses from natural causes like adverse weather, fire, insects, disease, wildlife, and price declines (in revenue-based plans). Policies are federally subsidized and reinsured.
Federal Crop Insurance details.Crop-Hail Insurance: This is a private product, separate from the federal program. It specifically covers damage from hail and/or fire, often with lower deductibles and more flexible options than MPCI. It can supplement an MPCI policy.
Whole-Farm Revenue Protection (WFRP): This plan is for diversified farms, protecting your entire farm’s revenue against decline from natural disasters or market changes, rather than insuring individual crops.
Micro Farm Policies: A simplified version of WFRP, this policy is custom for smaller, diversified farms, including specialty crop, organic, and direct-market producers, making revenue protection more accessible.
Fruit and Vegetable Insurance.Catastrophic (CAT) Coverage: A minimal-risk policy with federally subsidized premiums (an administrative fee is required). CAT pays when losses exceed 50% of your normal yield, compensated at 55% of the market price.
Buy-Up Coverage: This allows you to increase your coverage beyond the basic CAT level, typically from 50% up to 85% of your approved yield or revenue. Premiums increase with coverage, but federal subsidies still apply.
How Coverage Works: Yield Protection vs. Revenue Protection
Understanding the difference between yield and revenue protection is key to choosing the right policy.
Yield Protection (YP): This policy insures against a loss in the quantity of your crop. Your coverage is based on your farm’s historical average yield (Actual Production History or APH). If your harvest falls below your guaranteed yield, you receive a payment. It protects against production loss but not price declines.
Revenue Protection (RP): This policy protects against lost revenue from declines in yield, price, or both. Your revenue guarantee is based on your APH and an expected market price. If your actual revenue falls below this guarantee, you receive a payment. It offers a more comprehensive safety net against both production and market risks.
Here’s a quick comparison:
| Feature | Yield Protection (YP) | Revenue Protection (RP) |
|---|---|---|
| What it insures | Loss in quantity (yield) | Loss in total revenue (yield and/or price) |
| Trigger | Actual yield falls below guarantee | Actual revenue falls below guarantee |
| Price basis | Commodity market prices | Commodity market prices OR individual farm’s historic prices |
| Primary benefit | Protects against production shortfalls | Protects against both production and price declines |
| Ideal for | Commodity growers, focus on production risk | Diversified farms, direct-to-consumer, revenue stability |
Benefits for Beginning Farmers and Ranchers
The federal crop insurance program offers special benefits to help new producers. A beginning farmer is one who has not operated a farm for more than 5 years (or 10 for WFRP/Micro Farm). If you qualify, you may be eligible for:
- Lower Insurance Costs: Receive higher premium subsidies.
- Waived Administrative Fees: CAT and buy-up policy fees may be waived.
- Use of Previous Producer’s History: You may be able to use the farm’s existing production history to establish your APH, potentially allowing for higher coverage sooner.
- Increased Yield Adjustments: You may qualify for a higher substitute yield, which can increase your APH and coverage guarantee.
These benefits help the next generation of farmers manage risk and build resilience. We at Farm & Country Insurance are dedicated to helping beginning farmers in New York access these valuable programs.
A Guide to Livestock Insurance Plans
Just like crops, your livestock faces unique risks, from disease outbreaks to unpredictable market prices. Livestock insurance is designed to be a protective shield for your animal assets, offering a crucial financial safety net. Whether you run a dairy, raise cattle, or care for other livestock in New York, these plans guard against falling market prices or unexpected drops in profit margins, providing vital tools for managing uncertainty.
What Does Livestock Insurance Cover?.
Understanding Livestock Risk Protection (LRP) and Gross Margin (LGM)
Two key federal programs are Livestock Risk Protection (LRP) and Livestock Gross Margin (LGM).
Livestock Risk Protection (LRP) shields you from falling market prices. You select a coverage price and an insurance period. If the actual market price drops below your chosen coverage price by the end of the period, you receive a payment. It’s purely price protection, allowing you to benefit from price increases while guarding against declines.
Learn more about Livestock Risk Protection.
Livestock Gross Margin (LGM) protects your gross margin—the market value of your livestock or milk minus key feed costs. If your actual gross margin falls below the guarantee on your policy, you receive a payment. This is helpful if livestock prices dip or feed costs unexpectedly rise, squeezing your profits.
For 2026, the USDA is streamlining these programs and expanding LRP coverage to include unborn calves and cull cows, offering more flexibility for producers.
Dairy Revenue Protection (DRP) for Milk Producers
For dairy producers, Dairy Revenue Protection (DRP) is a specialized program that protects against a drop in quarterly milk revenue. This decline can be caused by lower milk prices, decreased milk production, or a combination of both.
You choose a coverage level and a protection factor to customize the policy. The program uses futures prices to establish an expected revenue. If your actual revenue falls below the insured level, you receive a payment, creating an important safety net for dairy farms sensitive to price and production shifts.
Find more about Dairy Farm Risk Management.
Like LRP and LGM, the DRP program is also being improved for the 2026 crop year with modified dates and more flexibility related to animal disease impacts. These continuous updates show a commitment to providing farmers with effective risk management tools. At Farm & Country Insurance, we stay on top of all changes to ensure our clients receive the most current and beneficial coverage available.
Stay updated with USDA news on livestock programs.
The Essential Guide to Crop and Livestock Insurance Processes
Navigating crop and livestock insurance can seem complex, but understanding the key dates, information requirements, and claims process makes it manageable. At Farm & Country Insurance, our specialists are here to guide you every step of the way.
Our crop insurance specialists.
The Application Process and Key Deadlines for Crop and Livestock Insurance
Applying for crop and livestock insurance involves meeting strict deadlines set by the USDA’s Risk Management Agency (RMA). Missing these dates can impact your coverage.
When applying, you’ll need to provide farm details, including past yield data (Actual Production History, or APH), acreage information, and planting plans. It is critical that this information is accurate and matches records on file with other agencies like the Farm Service Agency (FSA).
During the application, you will select a coverage level (the percentage of your expected yield or revenue to insure) and a unit structure, which is how your crops are grouped for insurance. Common unit structures include:
- Basic Units: All of one crop in a county with the same ownership share.
- Optional Units: Separates production by specific areas, potentially leading to more localized claim payouts.
- Enterprise Units: Combines all acreage of one crop in a county, often resulting in lower premiums.
- Whole-Farm Units: Groups all insured crops in a county into one unit, used for WFRP policies.
The crop insurance calendar has several key dates:
- Sales Closing Date: The deadline to apply for or change a policy.
- Final Planting Date: The last day to plant for full coverage.
- Acreage Reporting Date: The deadline to report how many acres you’ve planted.
- Premium Billing Date: When your insurance bill is due.
- End of Insurance Date: When coverage for the crop year ends.
- Termination Date: The final day of the policy; it will end if the premium is unpaid.
We work closely with our clients across New York, from Cayuga County to Auburn and Moravia, to ensure applications are complete and deadlines are met.
How to File a Claim for Crop and Livestock Insurance
If your crops or livestock suffer a covered loss, taking prompt action is vital for a smooth claims process.
- Notify Us Immediately: Contact your Farm & Country Insurance agent as soon as you find the damage. There are strict time limits for reporting a loss.
- Preserve the Evidence: Do not destroy damaged crops or dispose of animals without authorization from a claims adjuster. An adjuster must inspect the damage first.
- Work with the Adjuster: An approved adjuster will visit your farm to assess the loss. Cooperate fully and provide any requested records, such as production history, sales receipts, or veterinary reports.
- Maintain Good Records: Detailed records of planting, harvesting, yields, animal health, and sales can significantly speed up your claim.
- Receive Your Payment: Once the claim is approved, you will receive an indemnity payment based on your policy terms and coverage level.
Our team is here to guide you through the entire claims process, from the first call to the final payment.
Finding an Agent and Additional Resources
Choosing the right crop and livestock insurance agent is as important as selecting the right policy. Your agent is a trusted partner in managing farm risks, bringing expertise, local insight, and personal service. At Farm & Country Insurance, we build lasting relationships by taking the time to understand your farm and offer custom solutions.
How to Find and Choose a Crop Insurance Agent
When looking for an agent, consider these key factors:
- Agricultural Expertise: An agent who specializes in crop and livestock insurance will understand federal programs, policy types, and recent changes that can benefit your farm.
- Understanding of Your Operation: A good agent learns about your specific crops, livestock, location, and risk tolerance to provide recommendations that truly match your needs.
- Local Knowledge: An agent familiar with local weather patterns, soil types, and common risks in upstate New York can offer superior advice.
- Service and Support: Since the USDA RMA sets the prices for identical policies, an agent’s true value is in their knowledge, service, and ability to help you make smart choices. Ask other farmers for recommendations.
We invite you to connect with the team at Farm & Country Insurance. Our brokers are committed to helping you find the best risk management solutions for your farm.
Find a local agent with the USDA.
Our farm insurance brokers.
Valuable Tools and Resources for Farmers
In addition to a knowledgeable agent, several resources from the USDA’s Risk Management Agency (RMA) can help you manage risk.
The USDA RMA Website (rma.usda.gov) is the primary source for federal crop and livestock insurance information, including policy basics, fact sheets, and official guidelines.
Other useful tools include:
- Cost Estimator: An online tool to estimate premiums for different crops and coverage levels in your county.
Cost Estimator tool. - RMA Information Browser: Provides access to historical data like yields, prices, and premium rates.
RMA Information Browser. - Agent Locator: A USDA tool to find approved agents in your area.
These tools, combined with expert guidance from your Farm & Country Insurance agent, empower you to make informed decisions and build a more secure future for your farm.
Conclusion: Building a Resilient Future for Your Farm
Farming is a labor of love, but it comes with many unknowns. From market shifts to unpredictable weather, many factors are out of your control. This is why proactive risk management is essential for building a strong and stable farm for years to come.
Crop and livestock insurance is your farm’s financial safety net, designed to protect you when unexpected challenges arise. Whether it’s a harsh New York winter or a dip in market prices, the right insurance ensures your hard work and investments are protected, offering peace of mind to focus on what you do best.
Since 1984, Farm & Country Insurance has been a trusted partner to New York’s agricultural community. We have worked alongside farmers in dairy, grain, fruit, and vegetable operations across the state, from Cayuga County to Auburn and Moravia. Our team’s deep understanding of farming allows us to provide comprehensive coverage and custom risk management solutions.
Let Farm & Country Insurance help you steer crop and livestock insurance. We are here to ensure you have the financial security to weather any storm and thrive for generations to come.