
The Farm Truck Insurance Essentials
Do farm trucks need insurance? The answer depends on how and where you use your farm truck:
| Farm Truck Usage | Insurance Requirement |
|---|---|
| Driven on public roads | Yes, liability insurance is legally required |
| Used only on private property | Not legally required, but still recommended |
| Used for commercial purposes | Commercial auto insurance is required |
| Farm-tagged vehicles | Minimum liability coverage required in most states |
If your farm truck travels on public roads, even occasionally, you need at least liability insurance coverage. This isn’t just good advice—it’s the law in most states. While trucks used exclusively on private property may be exempt from legal requirements, leaving them uninsured exposes your farming operation to significant financial risk.
Farm trucks are the workhorses of agricultural operations, hauling everything from feed and livestock to equipment and produce. When these essential vehicles are damaged or involved in accidents, the costs can quickly mount, potentially threatening your farm’s financial stability.
I’m Casey Love, owner of Farm & Country Insurance, and I’ve spent years helping farmers steer the complex world of do farm trucks need insurance questions with custom coverage solutions that protect their operations and assets. At Farm & Country Insurance, we understand that your farm vehicles represent both significant investments and critical operational tools that deserve proper protection.
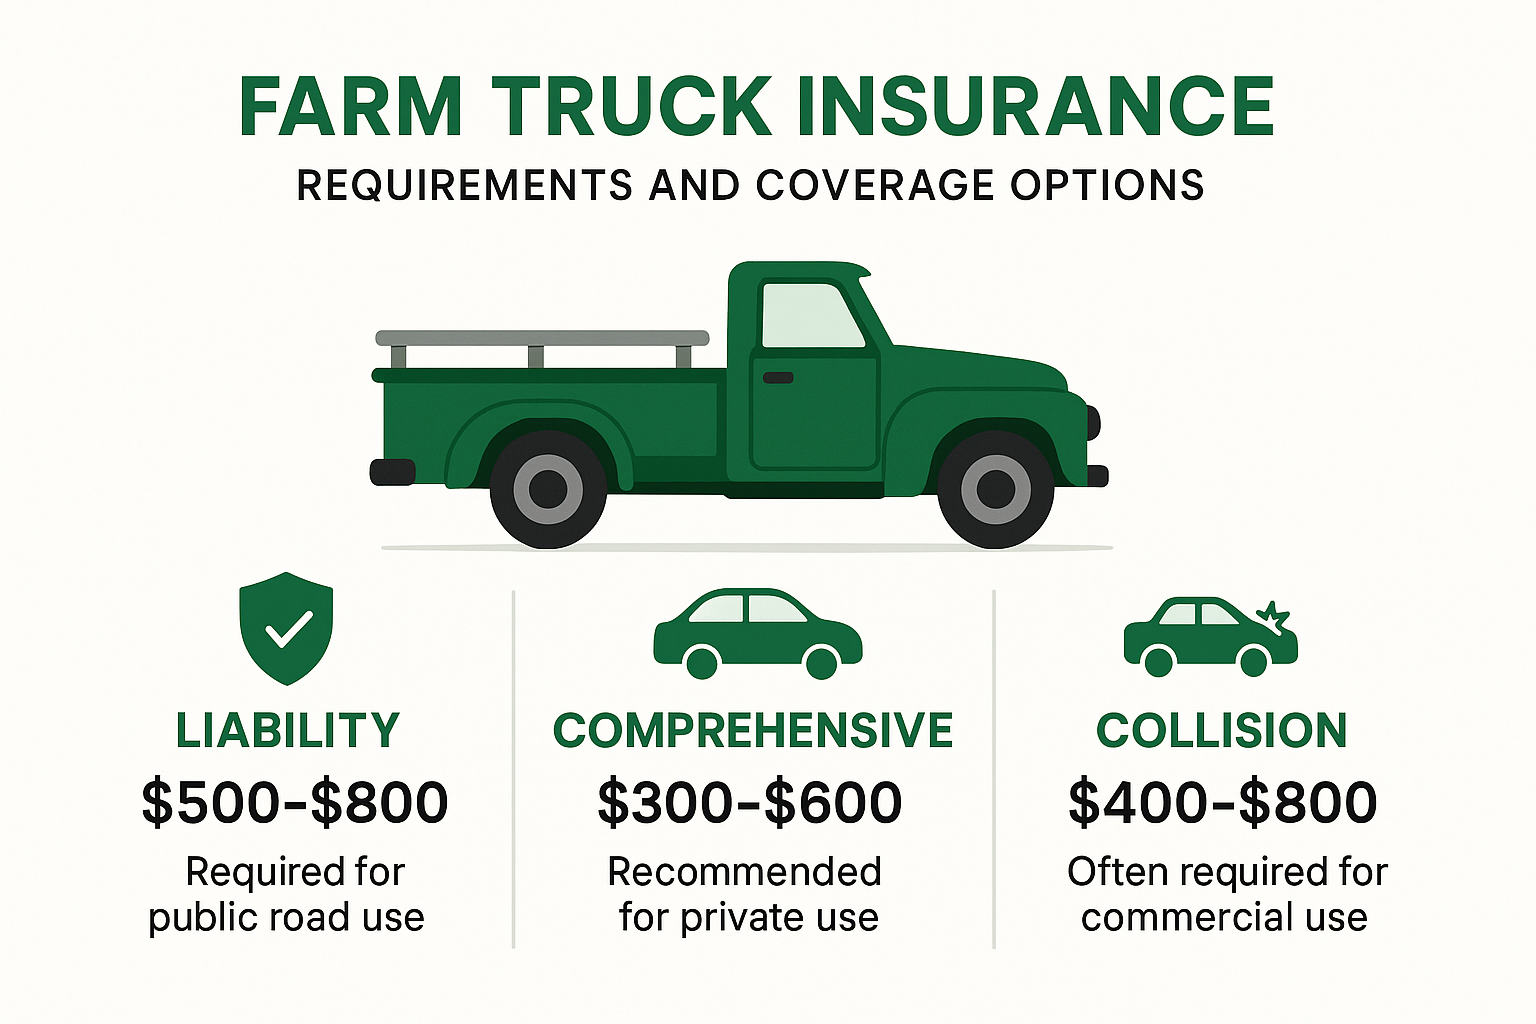
Do Farm Trucks Need Insurance?
The question “do farm trucks need insurance?” comes up often in my conversations with farmers across New York State. The straightforward answer is yes—most farm trucks need insurance, especially if they ever venture beyond your property line.
Any farm truck that travels on public roads requires auto insurance coverage, just like your family car. This requirement stands whether you’re driving that truck to town once a day or once a month, and even if you’re just crossing the road to reach another field.
At minimum, you’ll need liability coverage for farm vehicles on public roads. This protection is crucial—it shields you financially when you’re at fault in an accident causing injury or property damage to others. Given the size and weight of many farm vehicles, we typically recommend at least $1,000,000 in coverage, as the potential for significant damage is much higher than with passenger vehicles.

“Your farm vehicles are essential to your operation; let’s protect them together,” is something I often tell clients at Farm & Country Insurance. I’ve witnessed how proper coverage has saved farms from financial catastrophe after accidents.
Take this real situation: A farmer from Cayuga County was transporting produce to the local farmers market in his pickup when he collided with another vehicle. Because he had adequate liability coverage, his insurance covered the $45,000 in damages to the other party—protecting his farm’s financial stability when it could have been seriously compromised.
Legal Requirements in New York State
New York’s Department of Motor Vehicles has specific guidelines for farm vehicles. According to the About Agricultural and Farm Vehicles resource, vehicles used for farming purposes typically receive an ‘Agricultural’ classification, which differs from the standard ‘Farm’ class.
New York law mandates that any vehicle on public roads must carry minimum liability insurance including:
- Bodily Injury Liability: $25,000 per person/$50,000 per accident minimum
- Property Damage Liability: $10,000 per accident minimum
These minimums, however, rarely provide adequate protection for farm operations. At Farm & Country Insurance, we generally recommend significantly higher coverage limits to properly safeguard your farm assets and livelihood.
New York also offers the Covered Farm Vehicle (CFV) designation. By completing a CFV-1 form, certain farm vehicles can receive exemptions from some commercial driving requirements—though insurance remains mandatory for public road use.
Exemptions and Special Considerations
While insurance is generally necessary for farm trucks, several important exemptions and considerations exist:
Farm trucks used exclusively on private property don’t legally require insurance. That said, I still strongly recommend coverage—I’ve seen too many uninsured farm trucks damaged by fire, theft, or on-farm accidents, leaving farmers to bear the full replacement costs.
The Covered Farm Vehicle (CFV) designation in New York can exempt vehicles from certain commercial requirements when they’re operated by the farm owner, employee, or family member; transport agricultural commodities or supplies; aren’t used for hire; and don’t carry hazardous materials requiring placarding.
New York also allows for Unlicensed Farm Trucks (ULFT) with specific restrictions on usage, such as time of day and distance traveled from the farm. Even with limited use, these vehicles still require insurance on public roads.
Weight and distance factors also affect requirements. In New York, trucks with a Gross Combined Vehicle Weight over 26,000 lbs face additional regulations and insurance considerations.
A farmer from Aurelius once told me: “I thought my old farm truck was exempt because I only drove it a few miles on back roads between fields. After talking with Farm & Country Insurance, I finded even this limited public road use required liability coverage. Thank goodness I got proper insurance—a month later, I had a minor accident that would have cost thousands out of pocket.”
The bottom line? When asking “do farm trucks need insurance,” remember that protecting your farm’s essential vehicles isn’t just about meeting legal requirements—it’s about safeguarding your operation’s future.
Types of Farm Vehicles That Require Insurance
When it comes to protecting your agricultural operation, understanding which farm vehicles need insurance is essential. From the workhorse pickup to specialized equipment, each vehicle plays a unique role—and faces different risks.
| Vehicle Type | Public Road Use | Insurance Requirement | Recommended Coverage |
|---|---|---|---|
| Farm Pickup Trucks | Yes | Liability (mandatory) | Liability, Comprehensive, Collision |
| Semi-Trucks/Grain Haulers | Yes | Commercial Auto/Liability | Liability, Physical Damage, Cargo |
| Tractors | Limited | Liability when on roads | Liability, Comprehensive |
| ATVs/UTVs | Limited/No | Varies by use | Liability, Comprehensive |
| Farm Trailers | When towed | Usually covered by towing vehicle | Separate coverage recommended for high-value trailers |
| Specialty Vehicles (sprayers, etc.) | Limited | Liability when on roads | Specialized Farm Equipment coverage |
At Farm & Country Insurance, we’ve seen how different vehicles create different insurance challenges for farmers across Cayuga County. That trusty pickup that hauls feed one day and takes the family to town the next requires a different approach than the combine that rarely leaves your fields.
Understanding Coverage for Different Farm Vehicles
Your farm pickup trucks often wear multiple hats—hauling supplies in the morning and taking the kids to baseball practice in the evening. This dual-purpose nature creates unique insurance considerations. If your truck is titled in your name and primarily serves farm operations with occasional personal use, you might qualify for a personal auto policy with special farm endorsements. However, trucks titled to your farm business or primarily used commercially will need commercial auto coverage.
I remember helping a farmer in Skaneateles who was surprised to learn his personal auto policy wouldn’t cover his pickup after an accident because he was using it to deliver produce to local restaurants. A proper farm vehicle policy would have prevented his headache.
Those semi-trucks and grain haulers represent significant investments and carry substantial liability risks due to their size and road presence. At Farm & Country Insurance, we typically see semi-truck liability coverage running about $950 to $1,050 annually for $1 million in coverage, while a standard pickup might cost $200 to $400 for the same protection. If you’re hauling goods for others, don’t forget about cargo insurance—it’s often overlooked until it’s too late.
Tractors and implements might be the heart of your operation, with modern machines often representing investments of hundreds of thousands of dollars. While insurance isn’t legally required when they stay on your property, their immense value makes coverage a wise choice. One of our clients from Genoa learned this lesson the expensive way when his uninsured tractor caused $8,000 in damage to a neighbor’s fence during a brief trip on a public road—a cost he had to cover entirely out-of-pocket.
The humble ATVs and UTVs have become indispensable farm tools, zipping around properties for quick tasks and inspections. While they may not legally need insurance when used solely on private property, their susceptibility to theft, rollover accidents, and damage makes coverage worth considering. Do farm trucks need insurance? The answer might be yes legally, but for these smaller vehicles, it’s often a matter of smart risk management rather than legal requirement.
When it comes to farm trailers, many farmers don’t realize these aren’t automatically covered under their towing vehicle’s policy, especially high-value trailers. And those specialty vehicles like sprayers or harvesters? Their unique designs and functions often require specialized farm equipment coverage that standard policies don’t provide.
At Farm & Country Insurance, we don’t just sell policies—we help you understand exactly what protection your operation needs, custom to the specific vehicles that keep your farm running day after day.
Differences Between Farm Truck Insurance and Regular Auto Insurance
When you pull up to the gas station in your farm truck, you might notice curious glances from city folks. It’s not just your vehicle that’s different—the insurance that protects it is unique too. Farm truck insurance is specially designed for the agricultural lifestyle, with coverage options that match how farmers actually use their vehicles.
At Farm & Country Insurance, we’ve spent decades helping farmers understand these differences. Your farm truck isn’t just transportation—it’s a crucial piece of equipment that keeps your operation running.
The most obvious difference is in usage patterns. While regular auto insurance assumes daily commuting and personal trips, farm truck insurance accounts for seasonal use, off-road operation, and the specialized hauling needs of agricultural work. Most farm trucks put on fewer miles annually than personal vehicles but face different hazards like rough terrain and heavy loads.
Coverage territory is another key distinction. Standard auto policies typically focus on public roadways, but farm truck insurance extends protection across your entire operation—including fields, pastures, and other properties you farm. This broader territory reflects the reality that farm trucks spend much of their time away from paved roads.
The rate structure also works in farmers’ favor. Since farm vehicles generally have lower annual mileage and reduced public road exposure, premiums often reflect this reduced risk. A farmer from Scipio told me recently, “I was paying way too much using a standard auto policy for my farm truck until Farm & Country Insurance showed me the difference. My premium dropped by 30% with better coverage!”
Farm truck policies also offer specialized coverage options that regular auto insurance simply doesn’t consider—like protection for implements attached to your vehicle, custom farming equipment, and even specialized coverage for livestock transportation. These options address the unique risks that come with agricultural operations.
Perhaps most beneficial is the policy structure. Rather than treating each vehicle as a separate insurance challenge, farm trucks can often be included in broader farm insurance packages. This integration creates potential cost savings and ensures more comprehensive protection across your entire operation.
Customizing Your Policy for Farm Use
No two farms are identical, which is why cookie-cutter insurance policies rarely provide adequate protection. When it comes to Farm Truck Insurance, customization isn’t just helpful—it’s essential.
The customization process begins with a thorough operational risk assessment. We look at how you use each vehicle, what it typically carries, where it travels, and who operates it. A truck that primarily hauls hay between fields has different risks than one that regularly transports livestock to auction.
“When Farm & Country Insurance reviewed my operation, they noticed I was overinsuring some vehicles and underinsuring others,” shared a crop farmer from Venice. “Their recommendations balanced my coverage with my actual risks, saving me money while improving protection.”
Endorsements and add-ons allow us to tailor your coverage precisely. Non-owned auto coverage protects you when employees use their personal vehicles for farm business—a common scenario during harvest season. Cargo coverage ensures that valuable produce, livestock, or equipment being transported is protected. Equipment breakdown coverage goes beyond typical mechanical failure coverage to address issues specific to farm vehicles.
One of the most valuable add-ons for many farmers is rental reimbursement coverage. When your truck is being repaired after a covered claim, this provision helps cover the cost of a temporary replacement—keeping your operation moving during critical seasons when delays can mean significant losses.
The financial benefits of customization extend beyond just appropriate coverage. By bundling your farm truck insurance with other farm coverages, you can often secure significant discounts. Many of our clients throughout Cayuga County have saved 15-20% by combining their farm vehicle, property, and liability policies under one comprehensive package.
A dairy farmer from Moravia experienced the value of customized coverage firsthand: “My milk transport truck isn’t just transportation—it’s a critical link in my production chain. The specialized coverage Farm & Country Insurance recommended saved me when the refrigeration unit failed, covering not just the repair but also the lost milk.”
Do farm trucks need insurance? Absolutely—but not just any insurance. They need coverage as specialized and hardworking as the vehicles themselves and the farmers who operate them.
Factors Affecting the Cost of Farm Truck Insurance
When farmers ask me, “do farm trucks need insurance?” I often explain that not only is it necessary, but the cost varies widely based on several factors that are unique to each farm operation.
Your truck’s value plays a major role in determining premiums. That shiny new F-350 you just purchased will naturally cost more to insure than the trusty 1998 pickup that’s been part of your operation for decades. Specialized vehicles like livestock transporters or refrigerated produce trucks typically have different premium structures because they face unique risks and often represent larger investments.
How often you use your farm truck significantly impacts your insurance costs too. I remember working with a farmer from Moravia who used his heavy-duty pickup daily for commercial hauling between farms and processing facilities. His premiums were substantially higher than his neighbor who only used a similar truck occasionally to move equipment between fields a few times per month.
The driving history of everyone who operates your farm trucks matters tremendously. At Farm & Country Insurance, we’ve seen premiums vary by as much as 40% between farmers with clean driving records versus those with multiple violations or accidents. This makes sense when you think about it – insurance companies are essentially betting on how likely you are to have a claim.
Your chosen deductible amounts create a direct trade-off between monthly premiums and potential out-of-pocket costs. Many of our more established farm clients opt for higher deductibles of $1,000 or more because they have the financial stability to handle that expense if needed, while saving significantly on premiums throughout the year.
The coverage limits you select naturally affect your costs too. While basic liability might be more affordable, adding comprehensive and collision coverage provides that critical protection when a deer jumps out on a country road or when hail damages your vehicle. Based on our experience at Farm & Country Insurance, comprehensive farm truck insurance typically ranges from $350 to $1,500 annually for a single commercial farm vehicle, depending on all these factors combined.
Your location within New York State matters more than you might think. Insurance costs vary considerably between regions based on accident rates, theft statistics, and even weather risks. Farmers in areas prone to severe winter conditions or flooding might face different premium structures than those in more moderate climates.
The size and nature of your farm operation also influence your insurance costs. Larger farms with multiple vehicles might qualify for fleet discounts, potentially saving 10-15% compared to insuring vehicles individually. However, larger operations with more employees driving those vehicles might also face additional risk factors that insurers consider.
Tips to Save Money on Farm Truck Insurance
After 38 years of helping New York farmers protect their vehicles, I’ve learned a few tricks to help keep those insurance costs manageable without sacrificing necessary protection.
Bundling policies is perhaps the smartest move any farmer can make. By combining your farm truck insurance with other farm policies like property insurance or liability coverage, you can often secure significant discounts. I’ve helped farmers in Niles and Owasco save up to 25% through thoughtful policy bundling.
Strategic deductible increases can make sense if you have the financial capacity to handle a larger out-of-pocket expense. Just be honest with yourself about whether you could comfortably pay that $1,000 or $2,500 deductible if you needed to file a claim tomorrow.
Safety improvements not only protect your operation but can also lower your premiums. Installing anti-theft devices, dashcams, or telematics systems demonstrates to insurance companies that you’re serious about reducing risks. One dairy farmer I work with saved nearly 8% on his premiums after installing dashcams in all his delivery trucks.
Regular policy reviews are absolutely essential as your farm evolves. I recommend sitting down with your agent annually to discuss any changes to your operation. I recently helped a farmer in Scipio find he was paying for coverage on a truck he’d sold months earlier!
Driver training for everyone who operates your farm vehicles can pay dividends both in safety and savings. Many insurance companies offer discounts when farm employees complete defensive driving courses, sometimes reducing premiums by 5-10% while also improving overall farm safety.
Seasonal coverage adjustments make perfect sense for vehicles used only during specific times of year. Why pay full premiums on that specialized harvesting truck that sits idle for nine months? Adjusting coverage during off-seasons can significantly reduce your annual insurance costs.
Annual premium payments rather than monthly installments often come with discounts of 5-7%. If you can manage the cash flow, paying your full premium upfront almost always saves money in the long run.
I recently worked with a grain farmer from Scipio who implemented several of these strategies after our consultation. By bundling policies, increasing deductibles strategically, and installing simple safety features, he reduced his overall farm vehicle insurance costs by almost 30% while actually improving his coverage in critical areas. That’s the kind of win-win solution we love to create at Farm & Country Insurance.
Benefits of Insuring Your Farm Truck
When farmers ask me, “do farm trucks need insurance?” I often share stories that illustrate just how valuable proper coverage can be. Beyond simply checking the legal requirement box, insuring your farm truck provides real, tangible benefits that protect your livelihood.
Think about what happens when your trusty farm truck breaks down during harvest. Without it, operations grind to a halt, and every hour of downtime costs money. That’s where proper insurance becomes your safety net.
Financial protection against accidents isn’t just a nice-to-have—it’s essential. I remember helping a cherry farmer near Skaneateles who was involved in a minor collision while delivering to a farmers market. The repairs came to $4,800, plus $2,200 in damage to the other vehicle. His proper coverage meant he paid just his $500 deductible instead of nearly $7,000 out-of-pocket during his busiest season.
Farm trucks face unique risks beyond just accidents. Comprehensive coverage protects against those middle-of-the-night calls about theft, that sudden hailstorm that damaged your truck’s exterior, or the deer collision on a country road. These events happen with surprising frequency in rural areas.
Perhaps most importantly, proper insurance provides business continuity. When your truck is in the shop, rental coverage can keep your operation moving. One of our dairy farmers in Fleming told me this was a “farm-saver” when his milk transport truck needed repairs during a critical week.
Your farm represents generations of hard work and investment. Asset protection through adequate liability coverage ensures one unfortunate accident doesn’t put your entire operation at risk. Without it, your land, equipment, and even personal assets could be vulnerable in a lawsuit.
There’s also real value in the peace of mind that comes with knowing you’re covered. Farming has enough unpredictability with weather and markets—your insurance shouldn’t add to those worries.
Many farmers don’t realize that proper insurance is often required for loan and contract compliance. If you’ve financed your truck, your lender almost certainly requires comprehensive coverage. Similarly, some contracts with produce buyers or suppliers include insurance requirements that you need to meet.
Consequences of Not Insuring Your Farm Truck
The decision to skip insurance—or to underinsure—can lead to serious consequences that I’ve unfortunately seen affect hardworking farm families across New York.
Legal penalties start with fines but quickly escalate. In New York, driving without insurance can result in penalties up to $1,500, license suspension, and having your vehicle registration revoked. Imagine trying to run your operation with your primary truck impounded and your driver’s license suspended.
The most devastating impact often comes from personal financial liability. Without insurance, you’re personally on the hook for any damages or injuries you cause. I worked with a family farm in Sennett that faced this nightmare scenario—their uninsured grain truck was involved in an accident that injured another driver. The resulting $175,000 in damages and medical bills nearly forced them to sell a 40-acre parcel that had been in their family for generations.
If your truck is financed, lack of required insurance constitutes a loan default. This can trigger immediate repayment demands or even repossession, creating a cascade of financial problems during what’s likely already a difficult time.
The practical reality of operational downtime hits hard too. When an uninsured truck is damaged, repairs might be delayed until you can afford them. I’ve seen farms struggle through weeks or months without critical equipment because they couldn’t immediately fund repairs that insurance would have covered.
Farm trucks represent significant investments that deserve protection. A total loss due to fire, theft, or a severe accident means losing that entire investment if you’re uninsured. For many farms operating on tight margins, that’s simply not a recoverable loss.
So, do farm trucks need insurance? At Farm & Country Insurance, we believe the answer is a clear yes for most farm operations. The protection goes far beyond meeting legal requirements—it safeguards your operation’s financial health, continuity, and future. The relatively small cost of proper coverage is insignificant compared to the potential financial devastation of being uninsured when disaster strikes.
How to Obtain Farm Truck Insurance
Getting the right insurance for your farm trucks doesn’t have to be complicated. As a farmer, you already juggle enough responsibilities—your insurance shouldn’t add unnecessary stress to your plate.
Start by taking stock of your operation. Which trucks do you use? How often are they on public roads? What do they typically haul? These questions might seem basic, but they form the foundation of your coverage needs. At Farm & Country Insurance, we often find farmers are surprised by how their actual usage patterns affect their coverage options.
“Most farmers I work with already have a good sense of their vehicles and how they use them,” says one of our agents. “What they appreciate is having someone translate that information into the right coverage package.”
Before meeting with an insurance provider, gather your vehicle information—makes, models, years, VINs, and estimated values. This preparation saves time and helps ensure nothing falls through the cracks. Having your drivers’ information handy is also helpful, as their driving records will impact your premiums.
When selecting coverages, think beyond the minimum requirements. While liability coverage is legally mandated for vehicles on public roads, comprehensive and collision coverages protect your investment in the vehicles themselves. Optional coverages like rental reimbursement can be lifesavers during busy seasons when a truck breakdown could derail your entire operation.
One of the most common mistakes we see at Farm & Country Insurance is farmers choosing generic auto policies that don’t account for farm-specific risks. A policy designed for commuter vehicles often falls short when applied to farm trucks that might be hauling valuable livestock or produce, operating in muddy fields, or carrying specialized equipment.
Remember to review any policy thoroughly before signing. Pay special attention to exclusions—these are the situations your policy won’t cover. Understanding these limitations upfront prevents unpleasant surprises when you file a claim.
Working with Farm Insurance Specialists

There’s a world of difference between talking to a general insurance agent and consulting with someone who specializes in farm insurance. It’s like the difference between seeing a general physician and a specialist for a specific health concern—both are professionals, but one has deeper expertise in your particular situation.
Farm insurance specialists bring valuable agricultural knowledge to the table. They understand that a truck used for hauling grain faces different risks than one used for transporting livestock. They know that seasonal usage patterns affect coverage needs. And perhaps most importantly, they speak your language—no need to explain what a silage wagon is or why you need coverage for a feed truck.
“When I first called Farm & Country Insurance, I was pleasantly surprised that I didn’t have to explain basic farming concepts,” shared a crop farmer from Genoa. “Their specialist immediately understood my operation and suggested coverages I hadn’t even considered but absolutely needed.”
At Farm & Country Insurance, our specialists have worked with farms across New York for decades. This experience means we’ve likely helped someone with an operation similar to yours and can anticipate your needs based on that experience.
When claims arise, having a specialist in your corner makes a significant difference. They can advocate for you with adjusters who might not understand farm operations, explaining why certain repairs are necessary or why particular replacement options are appropriate.
Beyond just selling policies, farm insurance specialists help with comprehensive risk management. They might suggest simple operational changes that could significantly reduce your premiums or identify emerging risks you haven’t considered.
The Insurance for Farm Vehicles landscape changes regularly, with new coverages becoming available and regulations evolving. A specialist stays current on these changes, ensuring your coverage remains appropriate year after year.
Do farm trucks need insurance? Absolutely—but more importantly, they need the right insurance, custom to your specific operation. Working with specialists who understand the unique needs of agricultural vehicles ensures you get coverage that truly protects your farm’s valuable assets and operations.
When you’re ready to explore your farm truck insurance options, consider reaching out to someone who speaks your language and understands your world. At Farm & Country Insurance, that’s exactly what we offer—farm-focused expertise backed by decades of experience serving New York’s agricultural community.
Frequently Asked Questions about Farm Truck Insurance
Do farm trucks need insurance if driven only on private property?
Technically speaking, farm trucks that never leave your property aren’t legally required to have insurance in New York or most other states. But here’s the thing – just because you can skip insurance doesn’t mean you should.
Think about it: That trusty farm truck represents a significant investment, whether it’s a newer model or that reliable old pickup that’s been with your operation for years. Without insurance, you’re completely exposed to risks like:
A surprise thunderstorm that drops baseball-sized hail on your vehicle
That unexpected fire that starts in the barn where you store your truck
The theft that you never saw coming (farm equipment theft is unfortunately common)
An accident on your property that damages the truck or injures someone
One of our clients at Farm & Country Insurance learned this lesson the hard way when their uninsured farm truck was severely damaged when a tree fell on it during a windstorm. The $14,000 repair bill came straight out of their operating budget – a painful hit that proper comprehensive coverage would have largely protected against.
Even if your truck never touches public roads, we typically recommend at least basic coverage to protect your investment and provide peace of mind.
Can I use my personal auto insurance for my farm truck?
This is one of those “it depends” situations that requires looking at your specific circumstances:
If your truck is titled in your personal name rather than your farm business, you might be able to use a personal policy – but only if the truck is primarily used for personal transportation with just occasional farm use.
When your truck is used primarily for farm operations – hauling feed, transporting livestock, moving equipment – a personal policy likely won’t provide adequate protection, even with your name on the title.
The structure of your farm business matters too. If you’re incorporated or operating as an LLC, vehicles used for farm operations generally need commercial or farm-specific coverage, not personal auto insurance.
I’ve seen too many farmers find the hard way that their personal auto policy excluded “business use” after a claim was denied. One potato farmer from Cato thought he was saving money by keeping his farm truck on his personal policy. When the truck was damaged while hauling produce to market, his claim was denied because the insurer determined it was being used for business purposes.
At Farm & Country Insurance, we can help determine whether your vehicle needs a personal, commercial, or specialized farm policy to ensure you’re properly covered.
What types of coverage are available for farm trucks?
Farm truck insurance isn’t one-size-fits-all. We can customize your coverage based on how you use your vehicles and what risks you face:
Liability Coverage forms the foundation of any farm truck policy. It’s legally required when driving on public roads and protects you if you’re responsible for injuring someone or damaging their property. Given the size and weight of many farm vehicles, we typically recommend limits higher than the state minimums.
Collision Coverage steps in to repair or replace your truck when it’s damaged in an accident, regardless of who’s at fault. For newer, more valuable trucks, this coverage is particularly important.
Comprehensive Coverage protects against pretty much everything else: theft, vandalism, fire, storms, fallen trees, and even deer collisions (a common issue for our farm clients in rural New York).
Medical Payments coverage helps with medical bills for you and your passengers after an accident, regardless of who caused it. This can be especially valuable for family members who help with farm operations.
Uninsured/Underinsured Motorist Coverage protects you when the other driver doesn’t have insurance or doesn’t have enough. Unfortunately, about 13% of New York drivers are uninsured, making this coverage important.
Cargo Coverage is worth considering if you transport valuable items like livestock, produce, or equipment. Standard auto policies typically exclude or severely limit coverage for cargo.
Rental Reimbursement can be a lifesaver during busy seasons, providing a replacement vehicle while yours is being repaired after a covered claim.
A grape farmer from Aurelius shared how valuable cargo coverage proved when his refrigerated truck broke down while transporting harvested grapes. Not only was the truck repair covered, but the cargo coverage protected the value of the grapes that would have otherwise spoiled – saving thousands during a critical harvest period.
At Farm & Country Insurance, we work with farmers throughout Cayuga County and beyond to build customized coverage packages that protect what matters most to your specific operation. We understand that do farm trucks need insurance isn’t a simple yes-or-no question – it’s about finding the right protection for your unique farming operation.
Conclusion

So, do farm trucks need insurance? After everything we’ve covered, the answer is a clear yes for most farming operations. It’s not just about checking a legal box—it’s about protecting the vehicles that keep your farm running day in and day out.
Think about it: your farm trucks haul your harvests to market, transport your livestock safely, and carry the equipment you need to work your land. They’re not just vehicles—they’re vital partners in your agricultural business. Leaving these essential assets unprotected is like planting crops without checking the weather forecast—unnecessarily risky.
I’ve seen how proper insurance has saved farms from financial disaster. Last year, one of our clients in Scipio had his main grain truck severely damaged in an accident just days before harvest. Because he had comprehensive coverage through Farm & Country Insurance, he had a replacement truck within 48 hours. His harvest continued without missing a beat, and his operation avoided what could have been a catastrophic loss.
On the flip side, I remember a heartbreaking conversation with a farmer who thought skipping insurance on his “old reliable” farm truck would save him money. When that truck was involved in an accident that injured another driver, he faced a lawsuit that eventually cost him 40 acres of family land to settle. That’s a steep price to pay for saving a few hundred dollars on premiums.
“Your farm vehicles are essential to your operation; let’s protect them together.” – Farm & Country Insurance
Farm truck insurance isn’t complicated when you work with people who understand farming. At Farm & Country Insurance, we’ve spent nearly four decades walking farm fields, sitting at kitchen tables, and getting to know the unique needs of New York farmers. We speak your language because many of us come from farming backgrounds ourselves.
Whether you’re running a small family operation in Moravia or managing thousands of acres across multiple counties, the right insurance partner makes all the difference. We’ll help you find that sweet spot between comprehensive protection and affordability, ensuring your farm remains resilient when the unexpected happens—because in farming, the unexpected always happens.
I invite you to reach out and have a conversation about your farm truck insurance needs. No pressure, no insurance jargon—just straight talk about protecting what you’ve worked so hard to build. For more detailed information, check out our guide on Insurance for Farm Vehicles or give us a call to chat with someone who understands the unique challenges of farming in New York.
Proper insurance isn’t an expense—it’s an investment in your farm’s future and the peace of mind that comes from knowing you’re protected, no matter what tomorrow brings.