
Gallop Towards Coverage: Your Equine Insurance Options
Why Equine Insurance is a Smart Investment
Equine insurance provides financial protection for horse owners against unexpected veterinary expenses, liability claims, and the loss of their valuable animals. Here’s what you need to know:
Key Types of Coverage:
- Mortality Insurance – Covers death from accident, illness, or theft.
- Major Medical/Surgical – Pays for emergency vet bills and surgeries.
- Liability Insurance – Protects against third-party injury or property damage claims.
- Loss of Use – Compensates when horses can’t perform their intended purpose.
Typical Costs:
- Mortality premiums: 2.5% to 5% of horse’s value annually.
- Major medical coverage: $500 to $2,000+ per year.
- Liability insurance: $300 to $1,000+ annually.
Whether you own a single trail horse or operate a commercial stable in New York, horses represent significant financial investments that face unexpected risks. A single colic surgery can cost thousands, while liability claims from horse-related accidents can be financially devastating. Beyond medical costs, horses can cause property damage or injure third parties, leaving owners vulnerable to costly lawsuits.
We have helped countless New York horse owners protect their investments. Our experience has shown that proper equine insurance isn’t just about covering costs—it’s about preserving your ability to care for your horses when the unexpected happens.

Equine insurance glossary:
Key Types of Equine Insurance Coverage
Equine insurance comes in several forms, each designed to protect against specific risks. Whether you’re caring for a trail horse in the Finger Lakes region or managing a breeding operation in upstate New York, understanding these options helps you build the right protection.
For a deeper understanding of how these coverages work, you might want to explore Understanding horse insurance and More info about Horse Insurance.

Full Mortality and Major Medical/Surgical
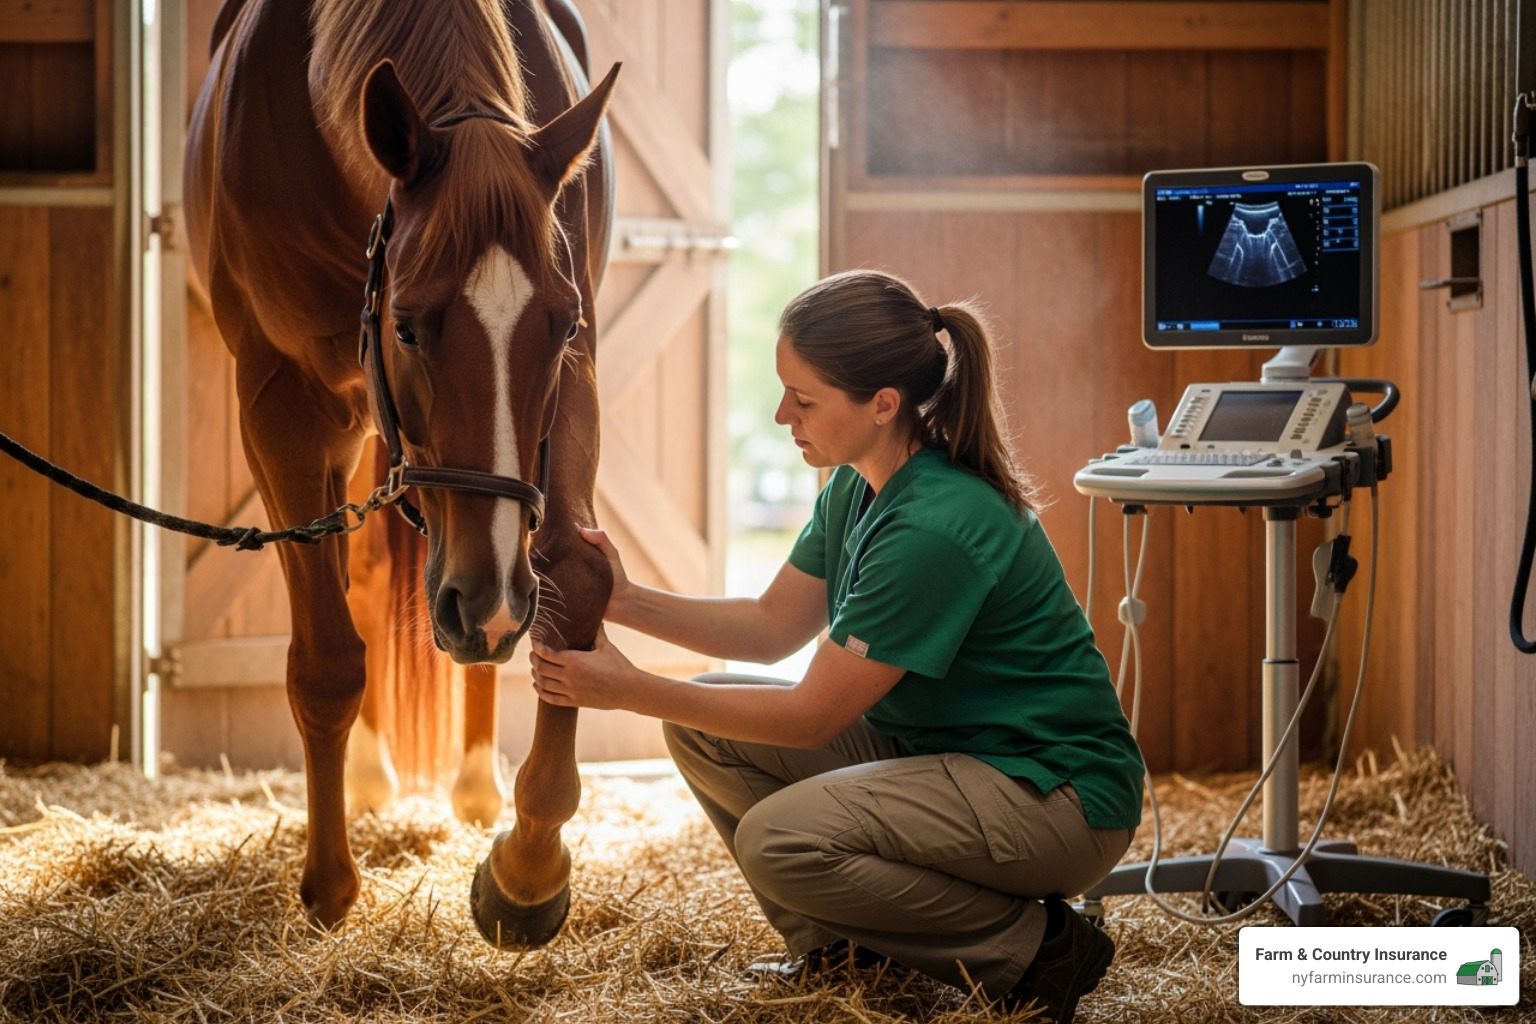
Full Mortality coverage is the foundation of most policies, protecting against loss of your horse due to illness, injury, accidents, fire, lightning, theft, and humane destruction when deemed necessary by a veterinarian. Most insurers cover horses from 30 days to 20 years old. A more budget-friendly option, Named Perils coverage, only covers specific risks listed in the policy, such as fire or transport accidents, but excludes death from most illnesses.
Major Medical and Surgical coverage functions like health insurance for your horse, covering unexpected veterinary expenses. This typically includes diagnostic tests (X-rays, ultrasounds), hospitalization, medical treatments, and emergency surgical procedures, including costly colic surgery. This coverage is for emergencies, not routine care like vaccinations or dental work. Policies usually have deductibles and sometimes co-payments. Most insurers require mortality coverage before adding a major medical policy. For information on other livestock, see our page on Cattle Mortality Insurance.
Personal and Commercial Liability
Liability insurance is a financial lifesaver when a horse causes injury or property damage. Personal liability coverage protects you if your horse injures someone or damages their property, whether on your farm or elsewhere. An Individual Horse Owner’s liability policy can provide significant coverage for a modest annual premium, including legal defense costs.
If you run a horse business in New York—boarding, lessons, training, or breeding—you need Commercial General Liability. This protects against claims from students, boarders, and visitors injured during your business activities. Given the litigious nature of horse-related incidents, liability coverage is essential for financial security. Learn more about protecting your operation with Farm Liability Insurance.
Loss of Use and Other Endorsements
Loss of Use coverage compensates you if a performance horse, breeding stallion, or working animal becomes permanently disabled and can’t fulfill its intended purpose. This helps bridge the financial gap when a valuable animal can no longer perform its specialized job.
Equine insurance can be customized with various endorsements:
- Tack and equipment coverage protects your gear against theft and damage, provided it is secured.
- Theft and straying coverage provides protection if your horse is stolen or goes missing. Microchipping is often required.
- Other endorsements can cover competition withdrawal, extra boarding expenses, and specialized needs for breeding operations.
- For international travel, worldwide exposure and air transit coverage is essential, protecting the horse during flights and quarantine.
The key is to match your coverage to your horse’s use. We can help you build a policy that fits your specific situation and budget. For more insights, see this research on Horse Owner Preferences for Equine Insurance Policies.
What Determines the Cost of Your Policy?
The cost of an equine insurance policy depends on several key factors that create a risk profile for your horse. Insuring a quiet trail horse near Auburn, NY, is different from covering a high-stakes show jumper.
Key factors influencing your premium include:
- Horse’s Value: This is central to mortality coverage calculations. A $5,000 pleasure horse costs less to insure than a $50,000 competition horse. Value includes purchase price, training investments, and performance records.
- Age: Horses between 30 days and 15 years old typically get the best rates. Premiums increase for older horses, with most mortality coverage capped around age 20.
- Breed and Use: A quarter horse used for trail rides has a lower premium than an eventing horse or racehorse, which are considered higher risk.
- Health History: Pre-existing conditions can lead to exclusions or higher rates.
- Coverage Limits: Higher payout limits mean higher premiums.
- Deductibles: A higher deductible (the amount you pay out-of-pocket) will lower your annual premium.
How to Determine Your Horse’s Value for an Equine Insurance Policy
Accurately valuing your horse is critical for equine insurance. If the value is too low, you won’t be adequately protected. If it’s too high, you’ll overpay for coverage.
Your purchase price is the starting point, but training costs, a strong competition record, and breeding value all increase a horse’s worth. For stallions and mares, pedigree and the performance of their offspring are key factors.
To get coverage, you must complete a Justification of Value (JOV), providing documentation like bills of sale, training invoices, and show records. Most equine insurance policies use Agreed Value coverage, where you and the insurer agree on the horse’s worth upfront. This avoids disputes at the time of a claim. Less common Fair Market Value policies pay what the horse was worth at the time of loss, which can lead to complications.
Understanding Premiums and Deductibles
Let’s look at typical costs for equine insurance. Transparency helps horse owners make informed choices.
- Mortality premium rates generally run between 2.5% and 5% of the horse’s insured value annually. For a $20,000 horse, this would be $500 to $1,000 per year.
- Major medical coverage premiums can range from $500 to $2,000 or more, depending on the coverage limits. For example, a policy for an 8-year-old dressage horse insured for $25,000 with $10,000 in major medical might cost around $1,375 annually.
- Liability insurance premiums for individual horse owners are typically between $300 and $1,000 annually. A policy with $1 million in coverage often costs less than $400 per year.
There are ways to manage these costs. Multi-horse discounts can offer significant savings, and choosing a higher deductible will lower your annual premium. The goal is to find the right balance of protection and affordability for your budget.
Navigating Your Policy and Provider
Choosing the right equine insurance policy is like finding the right trainer—you need an expert who understands your needs and has your back. We’ve helped New York horse owners steer these options since 1984. Understanding what to look for in a provider and a policy is key. For more details on our services, see More info about Equine Insurance Broker services.
What to Look for in an Equine Insurance Provider
Not all insurance providers are the same, especially when it comes to horses. Prioritize these qualities:
- Specialization in equine risks: You need a provider who understands that horses are unique assets with specific risks.
- Financial stability: Look for providers with strong financial ratings to ensure they can pay claims when needed.
- Customer service reputation: A provider should be responsive, fair, and helpful, especially during the stress of a claim. Read reviews and ask for references.
- Knowledge of New York regulations: Insurance laws vary by state. Local expertise ensures your policy complies with New York’s specific requirements.
- Licensed agents: Work only with licensed professionals who can clearly explain policy terms and answer your questions.
Common Exclusions and the Claims Process

Understanding what a policy doesn’t cover is as important as what it does. Common exclusions include:
- Pre-existing conditions: Health issues present before the policy begins are typically not covered. It’s best to insure horses when they are young and healthy.
- Routine veterinary care: Major medical policies are for unexpected emergencies, not predictable maintenance like vaccinations, dental work, or deworming.
- High-risk activities: If your horse’s use changes (e.g., from pleasure riding to barrel racing), you must inform your insurer to ensure coverage remains valid.
When filing a claim, follow these steps for a smoother process:
- Notify the insurer quickly: Most policies require notification within 24 to 48 hours of an incident.
- Provide thorough documentation: Keep all receipts, get detailed veterinary reports, and obtain a police report if an accident involves third parties.
- Communicate with your adjuster: Stay in touch during the claim review process. We can help you steer this.
- Know your rights: If a claim is denied, you have the right to appeal the decision. We can assist in providing additional information to build a stronger case.
Specialized Coverage for New York Equine Operations
Running an equine operation in New York, from a small boarding facility in Sempronius to a training center in Montezuma, involves unique risks that standard insurance can’t cover. The right equine insurance can be the difference between a minor setback and a business-ending disaster.
A hobby farm has different needs than a commercial boarding facility, which is why we tailor coverage to your specific operation. For smaller farms, you might also explore More info about Hobby Farm Insurance.
Insurance for Farms, Stables, and Instructors
Equine businesses deal with the unpredictable combination of large animals and people, creating significant liability exposures.
- Commercial General Liability (CGL) is the foundation, covering you if someone is hurt on your property or your operations cause property damage.
- Care, Custody, and Control (CCC) coverage is critical if you board, train, or handle horses you don’t own. Standard CGL policies exclude coverage for non-owned animals in your care, so CCC fills this vital gap, protecting you if a client’s horse is injured or dies due to your negligence.
- Instructor and trainer liability provides specialized protection for the unique risks of teaching riding, whether at your own facility or elsewhere.
If you host clinics, competitions, or special events, discuss them with your insurer beforehand to ensure they are covered under your CGL policy. For more on protecting your facilities, see Barn Insurance New York.
Protecting Riding Clubs and Associations
New York’s riding clubs and associations bring the equine community together but also create liability exposures that require careful management.
- Club liability coverage protects the organization during its activities, such as trail rides, shows, and educational clinics.
- Directors & Officers (D&O) liability is essential for clubs with elected boards, protecting leadership from lawsuits alleging mismanagement or wrongful decisions. This is crucial protection for volunteers.
- Event-specific coverage can be arranged for special occasions like horse shows or fundraisers to ensure adequate protection for all participants.
We help New York equine organizations find affordable coverage that protects their activities and their communities. To understand the broader context, learn more at More info about Farm Business Insurance.
Frequently Asked Questions about Equine Insurance
Horse owners across New York often have similar questions about equine insurance. Here are answers to the most common concerns we hear.
Can I get insurance for an older horse?
Yes, you can often get equine insurance for an older horse, but with some limitations. Mortality coverage is typically available for horses up to 18 or 20 years old, after which it may be unavailable or have higher premiums. Major Medical and Surgical policies may also have age restrictions or exclude pre-existing or age-related conditions like arthritis.
For senior horses that no longer qualify for full mortality, Restricted Perils or Named Perils policies are an option. These provide limited protection for specific events like fire or theft, but not death from illness.
Does my homeowner’s policy cover my horse?
Almost always, the answer is no. Standard homeowner’s policies are designed for houses and domestic pets, and they typically exclude livestock, including horses, from both property and liability coverage. This creates a significant liability gap. If your horse gets loose and causes an accident or injures a visitor, your homeowner’s policy is unlikely to cover the claim. You need a specialized equine insurance policy, such as an Individual Horse Owner’s (IHO) Liability policy or a comprehensive farm package. Learn more at Farm Homeowners Insurance.
What is Care, Custody, and Control (CCC) coverage?
Care, Custody, and Control (CCC) coverage is essential for any business that takes temporary responsibility for horses they don’t own. This includes boarding facilities, trainers, horse transporters, veterinarians, and farriers.
CCC protects you from legal liability if a non-owned horse is injured, becomes sick, or dies while in your care due to your negligence. Your standard Commercial General Liability (CGL) policy will not cover this, as it excludes damage to property (the horse) in your care. CCC fills this critical gap, protecting your business from potentially ruinous claims. We ensure our clients understand these distinctions to operate with complete protection.
Secure Your Peace of Mind with the Right Coverage
Protecting your horses with the right equine insurance means protecting your passion, your investment, and your livelihood. The risks are real, and the potential costs of an accident or illness can be staggering.
Comprehensive protection is key. Mortality coverage safeguards against the ultimate loss, major medical insurance prevents devastating vet bills, and liability protection shields you from claims that could threaten your financial stability.
Equine insurance is not one-size-fits-all; it must be customized to your unique situation. A breeding operation in Fleming has different needs than a riding instructor in Niles. This is why custom policies are essential.
We’ve served the New York horse community since 1984. We understand the local challenges, from harsh winters to the liability risks of running an equine business. Our expertise is in helping you protect what matters most.
Don’t wait for a crisis to find out you’re not covered. It’s time to give your horses—and yourself—the security that comes with a proper equine insurance policy. Let us help you craft a policy that fits your needs and budget, providing reliable protection for the long haul.
For more information about expanding your coverage to other livestock, visit Can you insure livestock?
