
Understanding Farm Building Protection
A farm building insurance policy is specialized coverage designed to protect agricultural structures from damage and liability risks. Unlike standard homeowners insurance, these policies address the unique needs of farm operations.
Key Elements of Farm Building Insurance Policies:
- Covered Structures: Barns, silos, machine sheds, greenhouses, milking parlors
- Protection Against: Fire, windstorm, hail, lightning, theft, vandalism
- Valuation Options: Replacement cost or actual cash value
- Additional Coverage: Equipment breakdown, debris removal, code compliance
Farm building insurance policies typically exclude flood damage, gradual deterioration, and pest infestations. Most policies provide automatic coverage for newly constructed structures (usually up to $50,000-100,000) for 60 days after completion.
Your farm buildings represent some of your largest physical assets and are essential to your daily operations. When a barn, machine shed, or grain storage facility is damaged, the financial impact goes beyond just repair costs—it can disrupt your entire business.
“Your farm is a complex operation that requires specialized insurance protection.” – Markel Insurance
I’m Casey Love, owner of NY Farm Insurance Company, and I’ve helped hundreds of New York farmers develop customized farm building insurance policies that protect their operations without breaking their budget. My experience with farm building insurance policy selection has taught me that proper valuation and peril selection are critical to avoiding devastating coverage gaps.

What Makes a Farm Building Insurance Policy Different?
A farm building insurance policy is unique because it bridges two worlds – your home life and your farm business. Unlike standard homeowners coverage, these specialized policies understand that your property serves dual purposes. At Farm & Country Insurance, we’ve seen how this distinction matters to New York farmers.

Think of farm building insurance as the Swiss Army knife of property coverage. It handles both your residential needs and the commercial realities of agricultural operations. This matters because standard homeowners policies typically place strict limits on—or completely exclude—structures used for farming, creating dangerous protection gaps.
I remember working with a dairy farmer from Cayuga County who called us after a severe windstorm. He was devastated to learn his homeowners policy wouldn’t cover $75,000 in damage to his milking parlor. The reason? His policy excluded structures primarily used for business purposes. This is a common and costly mistake.
A proper farm building insurance policy addresses your unique farming exposures by covering both your home and agricultural buildings, providing higher limits for outbuildings, including coinsurance provisions for adequate coverage, extending liability protection to farm operations, and covering specialized equipment and fixtures built into your farm structures.
Farm Building Insurance Policy vs Homeowners Insurance
The differences between these policies matter tremendously, even for smaller operations:
| Feature | Farm Building Insurance | Standard Homeowners |
|---|---|---|
| Dwelling Coverage | Similar limits available | Similar limits available |
| Outbuildings | Higher limits, farm use covered | Limited coverage, farm use excluded |
| Equipment | Farm machinery included | Farm machinery excluded |
| Liability | Covers farm operations | Limited to personal activities |
| Coinsurance | Typically 80% requirement | Not commonly required |
A hobby farmer in Moravia learned this distinction the hard way when winter snow collapsed his greenhouse and small barn. His homeowners policy capped outbuilding coverage at just $5,000 for structures not used for residential purposes. The actual damage? Over $30,000.
“Farm policies combine home insurance and business insurance to cover a home, farm structures and personal farming property in one package.” – American Family Insurance
More info about Farm Homeowners Insurance
Core Components of a Farm Building Insurance Policy
A comprehensive farm building insurance policy from Farm & Country Insurance typically includes these essential protections:
Dwelling Coverage protects your farmhouse, attached structures, and built-in appliances against covered perils. This works much like standard home insurance but recognizes the farm context.
Outbuilding Coverage insures your barns, silos, machine sheds, and other agricultural structures. This can be structured as scheduled coverage (with itemized values for each building), blanket coverage (with one aggregate limit), or a combination approach depending on your farm’s needs.
Personal Property Coverage handles your household items and personal belongings, with appropriate sub-limits for high-value items like jewelry or collectibles.
Farm Personal Property coverage protects machinery, equipment, supplies, stored grain, and livestock – the items that make your farm function.
Liability Protection covers bodily injury or property damage claims arising from your farm operations, not just personal activities.
Additional Living Expense coverage pays for temporary housing if your farm dwelling becomes uninhabitable after a covered loss.
Debris Removal covers clearing damaged farm structures after a loss, typically up to 25% of the damaged property’s limit – a significant help when rebuilding.
One of our vegetable farmers in Scipio benefited tremendously from comprehensive coverage when fire destroyed his main storage barn. His policy not only rebuilt the structure but covered debris removal and provided temporary housing while repairs to the attached living quarters were completed. Without proper farm coverage, he would have faced significant out-of-pocket expenses during an already difficult time.
Covered Buildings, Perils, and Exclusions
Understanding what’s protected under your farm building insurance policy is crucial to ensuring you have adequate coverage for your operation. At Farm & Country Insurance, we work with New York farmers to identify all insurable structures and explain exactly which perils are covered and which are excluded.
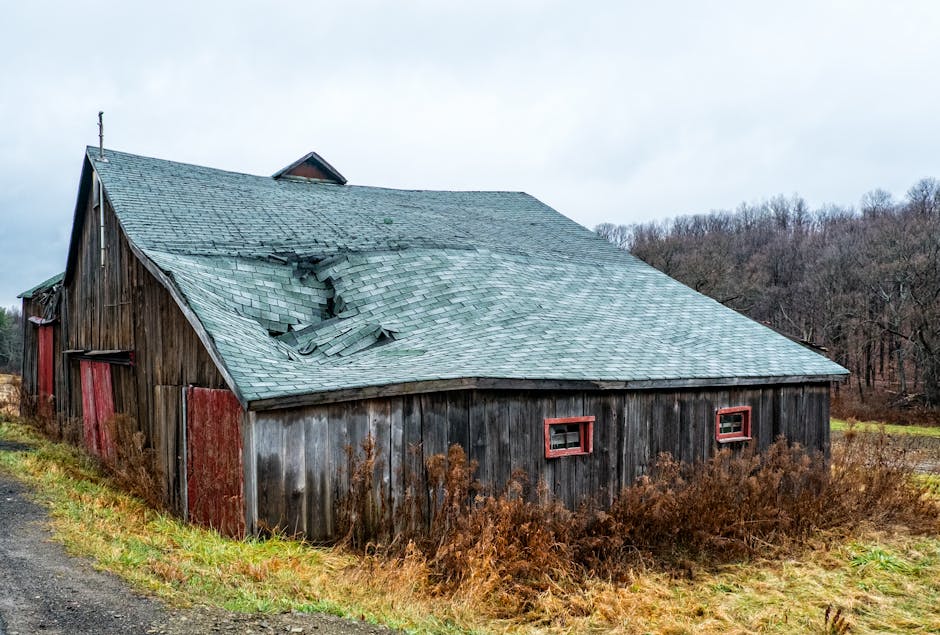
Structures Typically Covered
When I visit farms across Central New York, I often find that many farmers aren’t aware of all the structures that can be covered under their policy. Your farm building insurance policy isn’t just for that big red barn – it’s designed to protect the full range of buildings that keep your operation running.
From the dairy barns that house your herd to the silos storing your grain harvest, we make sure everything’s protected. Your machine sheds, workshops, and equipment buildings deserve coverage too – after all, they shelter some of your most valuable investments. And don’t forget about those specialty structures like greenhouses and hydroponic systems that might be critical to your diversified farm income.
Many of our Cayuga County dairy farmers have invested heavily in modern milking parlors with expensive built-in equipment. These specialized structures need particular attention in your policy to ensure both the building and its integrated systems are fully covered.
Even smaller structures matter – your fences, corrals, well houses, and portable shelters all play important roles in your farm’s daily operations. Employee housing and utility buildings round out the comprehensive protection that a proper farm policy provides.
More info about Barn Insurance New York
Perils Commonly Insured
“What exactly am I protected against?” That’s a question I hear almost daily from farmers across New York. Your farm building insurance policy typically offers protection against a range of dangers, with options to match your specific needs and budget.
The most basic coverage protects against fundamental threats like fire and lightning – dangers as old as farming itself. Windstorms and hail protection is particularly valuable in our region, where severe weather can strike with little warning. Your policy also guards against explosion damage, riot and civil commotion, aircraft and vehicle damage, and smoke damage.
For broader protection, many of our clients choose coverage that adds falling objects, weight of ice and snow (a real concern during our harsh New York winters), water damage from plumbing issues, and electrical surge damage. I remember when a grain farmer in Brutus called me after an electrical surge damaged his grain drying facility. Because he had comprehensive coverage, the $15,000 in repairs was fully covered, and his harvest continued without missing a beat.
The most thorough option is special form coverage, which flips the script by covering all perils except those specifically excluded. This approach provides the most comprehensive protection for your farm buildings and often makes the most sense for high-value or critical structures.
Common Exclusions & Limitations
Being upfront about what isn’t covered is just as important as explaining what is. At Farm & Country Insurance, we believe in transparency, so you never face surprises when you need your coverage most.
Even the most comprehensive farm building insurance policy won’t cover flood damage – that requires separate flood insurance. I learned how critical this distinction is when helping a fruit farmer in Ledyard who finded groundwater seepage damage to his cold storage facility wasn’t covered. We promptly added flood insurance to prevent future losses.
Your policy also typically excludes earth movement (like earthquakes and sinkholes), gradual damage from wear and tear, pest damage, and mold issues. Mechanical breakdowns usually aren’t covered unless you’ve added equipment breakdown coverage – something I strongly recommend for farms with significant mechanical systems.
War and nuclear hazards, intentional damage, and increased costs from building code compliance are standard exclusions in all policies. Most farm policies also include coinsurance requirements (typically requiring you to insure at least 80% of replacement value), special deductibles for certain perils like wind and hail, and sub-limits on certain types of property like hay stored in the open.

Valuation, Customization, and Cost Factors
When structuring a farm building insurance policy, understanding valuation methods is crucial to ensuring you’re adequately protected without overpaying for coverage. At Farm & Country Insurance, we help New York farmers steer these complex decisions.
Determining Replacement Cost vs Actual Cash Value
The valuation method you choose significantly impacts how much you’ll receive if a farm building is damaged or destroyed:
Replacement Cost Coverage:
– Pays to rebuild or repair the structure with materials of like kind and quality
– Does not deduct for depreciation
– Typically requires insuring to at least 80% of the full replacement cost
– Higher premium but more complete protection
Actual Cash Value Coverage:
– Pays replacement cost minus depreciation
– Takes into account the age and condition of the structure
– Generally less expensive but provides less complete protection
– May leave you with significant out-of-pocket expenses
A dairy farmer in Fleming experienced the benefit of replacement cost coverage when his 30-year-old barn was destroyed by fire. Despite the building’s age, his policy paid the full $275,000 needed to rebuild a comparable structure, without deduction for depreciation.
To determine accurate replacement costs, we recommend:
– Getting professional contractor estimates
– Using agricultural building cost calculators
– Considering regional construction costs
– Accounting for specialized features (e.g., milking equipment, ventilation systems)
“Insure dwellings to at least 80% of replacement cost to include replacement cost coverage.” – Markel Insurance
More info about Farm Policy Insurance
Insuring New or Renovated Buildings
When you’re constructing new farm buildings or renovating existing ones, special considerations apply to your farm building insurance policy:
Automatic Coverage Provision:
Most farm policies provide automatic coverage for newly constructed buildings, typically:
– Up to $50,000-$100,000 per structure
– For 60 days after completion
– Until the next policy renewal date
This gives you time to formally add the structure to your policy, but it’s important to notify your agent promptly about new construction to ensure adequate protection.
A grain farmer in Conquest took advantage of this provision when he completed a new equipment shed mid-policy term. The automatic coverage protected his $85,000 investment until the next renewal, when we added it to his scheduled buildings.
Construction Materials Considerations:
– Frame construction typically has higher premiums than metal or masonry
– Fire-resistant materials may qualify for lower rates
– Building code upgrades may require additional coverage
Coinsurance Compliance:
When adding new buildings, ensure your total coverage still meets the coinsurance requirement (typically 80% of replacement value) to avoid penalties on claims.
Optional Endorsements & Discounts
Customizing your farm building insurance policy with endorsements and taking advantage of available discounts can optimize your protection and reduce costs:
Popular Endorsements:
1. Equipment Breakdown Coverage: Protects built-in equipment like milking systems, grain dryers, and ventilation systems
2. Ordinance or Law Coverage: Pays for increased costs to comply with current building codes during repairs
3. Peak Season Coverage: Temporarily increases limits during harvest or other high-value periods
4. Green Rebuild Option: Covers the cost of environmentally friendly materials and systems
5. Weight of Ice and Snow Coverage: Specifically addresses collapse from winter weather events
6. Business Income Coverage: Replaces lost income if operations are interrupted due to building damage
A vegetable farmer in Genoa added business income coverage to his policy, which proved invaluable when a fire in his packing shed disrupted operations for three months. The coverage replaced his lost income while repairs were completed.
Common Discounts:
– Multi-policy discount (bundling farm with auto or umbrella coverage)
– Protective device credits (fire alarms, sprinkler systems, security systems)
– Claims-free discount
– Farm safety program participation
– Modern electrical and heating systems
– Professional farm management practices
At Farm & Country Insurance, we help farmers in New York maximize available discounts. One dairy operation in Owasco reduced their premium by 18% by installing fire detection systems and implementing a comprehensive safety program.
Named one of America’s Best Insurance Companies by Forbes
Claims, Reviews, and FAQs about Farm Building Insurance Policy
Even with the best protection in place, farm building claims happen to the most prepared farmers. Understanding the claims process and regularly reviewing your farm building insurance policy are essential parts of protecting your agricultural investment.

Filing a Claim Step-by-Step
When the unexpected happens to your farm buildings, having a clear roadmap for the claims process makes a stressful situation more manageable.
First, contact Farm & Country Insurance immediately after finding damage. The sooner we know, the faster we can help. We’ll gather basic information and provide you with a claim number that you’ll use throughout the process.
Document everything thoroughly before you begin cleanup. Take plenty of photos and videos showing the damage from multiple angles. One dairy farmer in Cato told me, “Those pictures I took right after the windstorm were worth their weight in gold when discussing the extent of damage with the adjuster.” His quick documentation helped secure a $42,000 settlement within two weeks.
While waiting for the adjuster, take reasonable steps to prevent further damage. Cover roof openings with tarps, board up broken windows, or move equipment to dry areas. Keep all receipts for these emergency expenses—they’re typically reimbursable under your policy.
When the claims adjuster visits your farm, they’ll want to see all damaged areas. Have your documentation ready, including your inventory of damaged items. Don’t be shy about asking questions during this visit—understanding the timeline and next steps will give you peace of mind.
Carefully review any settlement offer you receive. Verify that all damage is accounted for and replacement costs reflect current building prices. Getting independent repair estimates can be helpful, especially for specialized agricultural structures.
During repairs and rebuilding, stay involved in the process. Choose contractors familiar with farm construction and keep your insurer updated on progress. If workers find additional damage during repairs, report it promptly.
“Farmers has been in business for over 90 years. In a large-scale disaster, a Catastrophe Response Team via mobile claims centers may be dispatched.”
When and How to Review Your Policy
Your farm operation isn’t static, and your insurance shouldn’t be either. Regular reviews of your farm building insurance policy ensure your coverage evolves with your farm.
At minimum, schedule an annual policy review before renewal. This is when we’ll help you update building valuations to reflect current replacement costs and discuss any operational changes that might affect your coverage needs. We can also review your deductibles to make sure they still align with your financial situation.
Beyond your annual review, certain events should trigger an additional policy check-up:
Farm expansion is an obvious trigger—adding new buildings or substantially renovating existing ones changes your risk profile. Equipment upgrades, especially built-in systems like milking parlors or grain handling equipment, can significantly increase a building’s value.
Changing farm operations might require different coverage approaches. A fruit grower in Montezuma who added a cider-making facility needed improved coverage for the processing equipment and potential liability.
Don’t underestimate the impact of construction cost inflation. During one annual review, we finded that building costs in central New York had increased by 22% over three years. By updating coverage limits, our client avoided a significant coinsurance penalty when storm damage required extensive repairs the following season.
Revenue growth often means you have more to lose if operations are interrupted. As your farm business grows, consider whether additional business income coverage makes sense for your operation.
Quick Answers: Top 3 Questions
How are premiums calculated for a farm building insurance policy?
Your farm building premium isn’t pulled from thin air—it’s based on specific factors that reflect your actual risk. Construction materials play a major role, with metal buildings typically costing less to insure than wooden structures due to reduced fire risk. The age and condition of your buildings affect rates, as do their total value and your coverage limits.
Your chosen deductible directly impacts your premium—higher deductibles mean lower premiums but more out-of-pocket expense when claims occur. The level of peril coverage you select (basic, broad, or special form) also affects cost.
Location matters too—your farm’s fire protection class considers your proximity to fire departments and water sources. And of course, your claims history and safety features like lightning rods, updated wiring, and fire suppression systems can all influence what you pay.
Will livestock losses affect the building claim on my farm building insurance policy?
Good news—livestock losses and building claims are handled separately under your farm policy, even when they result from the same event. If a fire damages your barn and causes livestock losses, the building claim is processed under farm structures coverage, while livestock losses fall under farm personal property coverage.
Each coverage has its own limit and potentially different deductibles. This separation ensures that a large livestock claim doesn’t reduce the funds available to rebuild your structures, and vice versa. It’s one way your farm building insurance policy is specifically designed to address the unique complexities of agricultural operations.
How often should I update my building values on my farm building insurance policy?
At Farm & Country Insurance, we recommend reviewing and updating building values annually at minimum, during your policy renewal. But don’t wait for renewal if you’ve completed significant renovations or improvements, or when construction costs in your area change substantially.
Many farm policies include an inflation guard that automatically increases coverage limits by 2-4% each year, but this modest adjustment often can’t keep pace with actual construction cost increases, especially in today’s volatile market.
A grain farmer in Throop learned this lesson the hard way. His policy’s 3% inflation guard hadn’t kept pace with the 18% construction cost increase over four years. After working with us to update his values, he had adequate coverage when a fire damaged his grain storage facility the following year. “I’m glad we had that conversation about updating my values,” he told me. “I would have been in serious trouble if we hadn’t.”
More info about dairy-farm coverage
Conclusion
Protecting your farm buildings with a comprehensive farm building insurance policy isn’t just about checking a box for your lender—it’s about safeguarding the very heart of your agricultural operation. From the rolling dairy farms of Cayuga County to the picturesque fruit orchards of Ledyard, proper insurance coverage provides both peace of mind and financial security when the unexpected happens.
As we’ve seen throughout this guide, farm building insurance is a different animal than standard homeowners policies. It offers specialized protection custom to the unique needs of agricultural structures and the perils they face. The foundation of effective coverage rests on three pillars: accurate valuation, appropriate peril selection, and regular policy reviews.
When I visit farms across New York, I often find buildings that are significantly underinsured. One dairy farmer in Scipio was shocked to learn his milking parlor would cost nearly twice his insured amount to rebuild with today’s construction costs. After updating his coverage, he slept better knowing his operation was properly protected.
Remember these five essential points as you evaluate your coverage:
Accurate Valuation: Always insure buildings to at least 80% of replacement cost to avoid coinsurance penalties. That 30-year-old barn might not look like much, but rebuilding it with today’s prices could break the bank if you’re underinsured.
Comprehensive Coverage: Consider special form coverage that protects against all perils except those specifically excluded. The small premium difference often pays for itself many times over when unusual claims arise.
Customization: Don’t settle for one-size-fits-all protection. Add endorsements like equipment breakdown coverage to protect those sophisticated milking systems, or ordinance or law coverage to handle building code complications during rebuilding.
Regular Reviews: Your farm isn’t static, and neither should your insurance be. Schedule annual policy reviews and update coverage after adding buildings, making renovations, or changing operations.
Risk Mitigation: Simple steps like installing fire detection systems, maintaining electrical systems, and implementing safety protocols not only protect your assets but can also lower your premiums.
At Farm & Country Insurance, we’ve been protecting New York farms since 1984. We understand that your barns, silos, and equipment sheds aren’t just buildings—they’re the backbone of your livelihood. Our experience with farms of all types and sizes allows us to create protection that’s as unique as your operation.
Don’t wait for disaster to strike before finding gaps in your coverage. Give us a call today to schedule a friendly, no-obligation review of your farm building insurance policy. We’ll help make sure your farm is properly protected today, tomorrow, and for generations to come.