Protecting Your Agricultural Legacy: Why Farm Fire Insurance Matters
Farm fire insurance is specialized coverage that protects farm structures, equipment, livestock, and crops from fire damage. It differs from standard homeowners insurance by specifically addressing agricultural operations and assets.
Quick Farm Fire Insurance Facts:
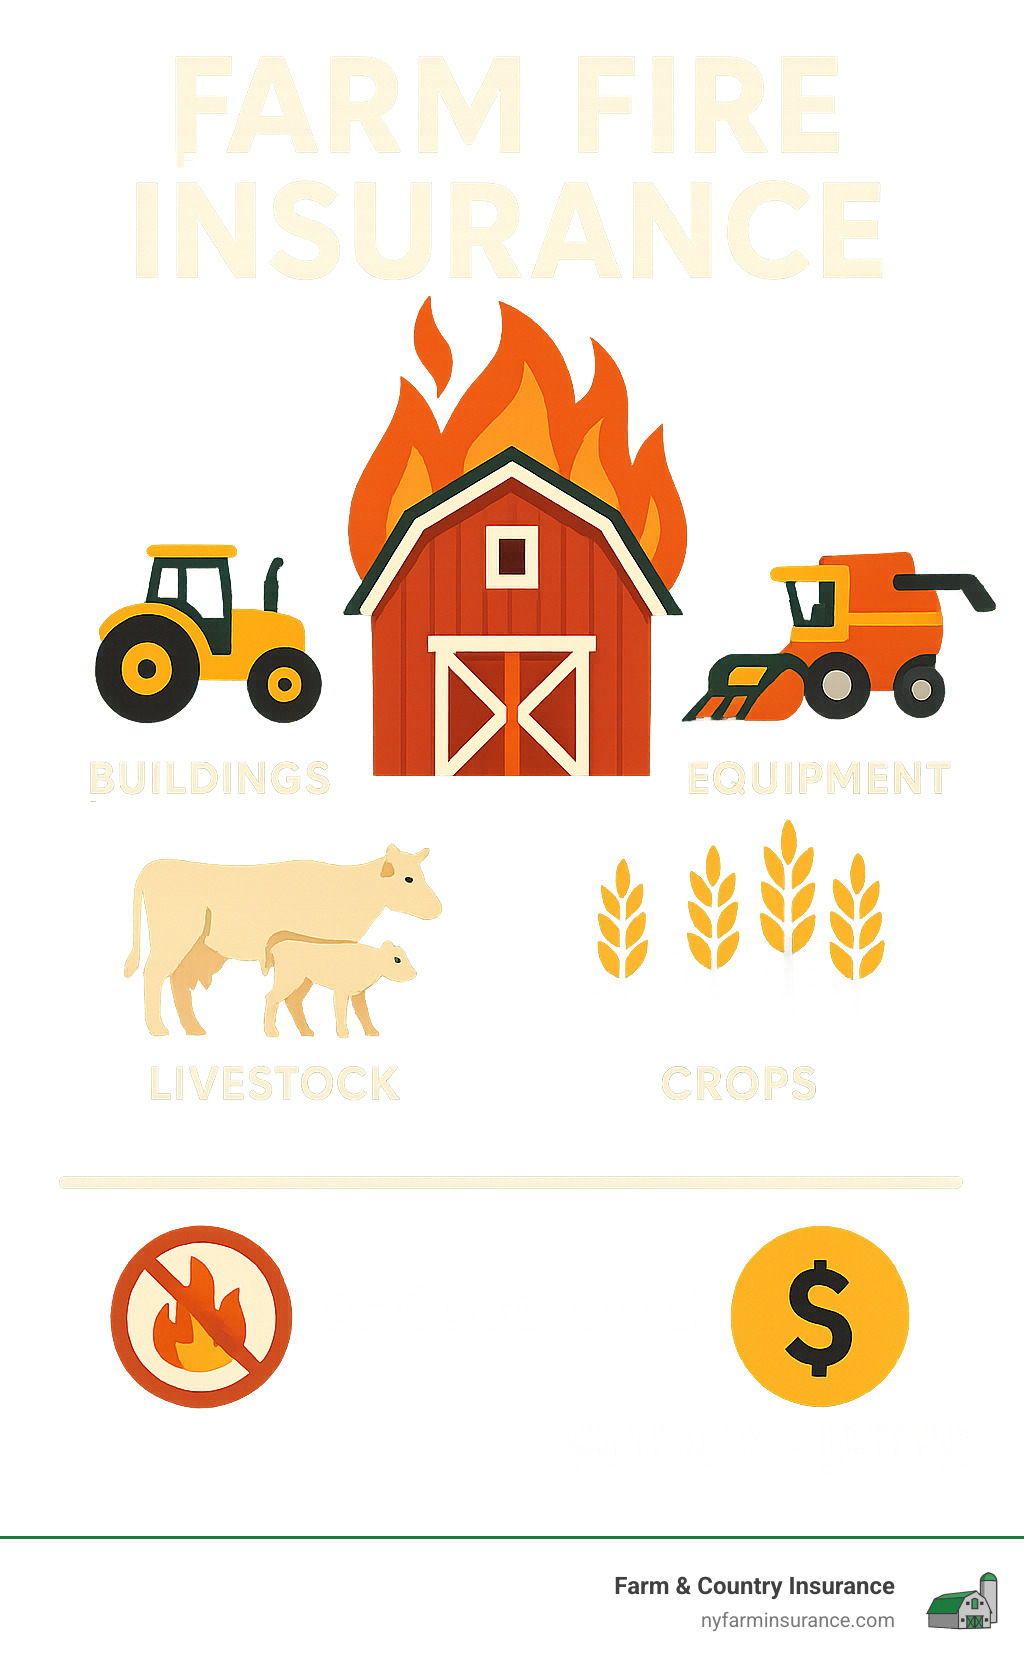
– Covers: Barns, equipment, livestock, harvested crops, and farm dwellings
– Average cost: Starting at $1,500 annually for small farms, varies by operation size
– Key features: Debris removal, temporary housing, replacement cost options
– Not typically covered: Crop fires started by non-weather events on neighboring properties
– Best practice: Review policy annually and after adding new buildings or equipment
The stakes couldn’t be higher for today’s farmers. According to data from the Food and Agriculture Organization, disasters now happen three times more frequently than in the 1970s and 1980s, with farmers bearing 63% of the costs of these catastrophic events. A single barn fire can devastate years of hard work in minutes, threatening not just buildings but your entire livelihood.
“Just do it. No matter if you think you will ever need it, always be prepared for the worst,” advises one Montana farmer who credits comprehensive coverage with keeping their operation afloat after a major fire loss.
I’m Casey Love, owner of Farm & Country Insurance, with over 15 years of experience helping New York farmers secure proper farm fire insurance protection custom to their unique operations. My background in agricultural risk management allows me to identify coverage gaps that standard agents might miss.
Understanding Farm Fire Insurance Basics
When flames engulf a barn or equipment shed, having the right protection can mean the difference between a setback and a catastrophe. Let’s dig into what farm fire insurance really means for your agricultural operation.
What Is Farm Fire Insurance?
Farm fire insurance is your financial shield against fire-related losses on your farm. Unlike city-focused insurance products, this specialized coverage is designed with the unique challenges and assets of farm life in mind.

At its heart, farm fire insurance protects everything from your barns and silos to your tractors and combines when fire strikes. It covers your livestock if they’re lost to flames and provides compensation for harvested crops stored in your buildings. After the disaster, it helps with the cleanup phase too.
“Farm fire insurance is one of our original core policies,” notes an agricultural insurer with roots dating back to 1845. “The unique needs of farmers have been our focus since day one.”
Most policies work as “named-peril” coverage—specifically listing fire, lightning, and explosion as covered events. This is different from “all-risk” policies that cover everything except what’s explicitly excluded.
How It Differs From Homeowners & Standard Farm Policies
Many farmers make a dangerous assumption: that their regular homeowners policy will cover farm operations. This misunderstanding can lead to devastating gaps in protection.
| Coverage Type | Homeowners Policy | Standard Farm Policy | Farm Fire Policy |
|---|---|---|---|
| Farm dwelling | ✓ | ✓ | ✓ |
| Personal belongings | ✓ | ✓ | ✓ |
| Farm structures (barns, silos) | ✗ | ✓ | ✓ |
| Farm equipment | ✗ | ✓ | ✓ |
| Livestock | ✗ | ✓ | ✓ |
| Harvested crops | ✗ | Limited | ✓ |
| Business liability | ✗ | ✓ | Limited |
| Fire department service charges | Limited | ✓ | ✓ |
| Debris removal | Limited | ✓ | ✓ |
As you can see, standard homeowners policies leave crucial farm assets completely unprotected. Your tractor, livestock, barn, and harvested crops simply aren’t covered. Even general farm policies might have limitations when it comes to fire-specific coverage.
“Your homeowners policy does NOT cover damage to farm operations or equipment,” emphasizes one industry expert. “Though they might seem similar at first glance, the differences are critical when disaster strikes.”
Who Needs It? Small, Hobby, and Commercial Operations
You might think farm fire insurance is just for big commercial farms, but the truth is operations of all sizes need this protection:
Small Hobby Farms (2-50 acres) need protection even when farming isn’t the primary income source. With modest livestock operations or orchards generating under $50,000 annually, basic coverage typically starts around $1,500 per year.
Medium-Sized Family Farms (50-500 acres) often represent the family’s main livelihood. Whether focused on crops, dairy, or livestock, these operations require more substantial coverage with premiums that scale accordingly.
Large Commercial Operations (500+ acres) with major production facilities and on-site processing need comprehensive coverage with high limits to protect their significant investments and multiple employees.
Here at Farm & Country Insurance, we’ve seen too many hobby farmers across Cayuga County assume they don’t need specialized farm coverage. Even a small barn housing a couple pieces of equipment represents a significant investment that your standard homeowners policy simply won’t cover if fire strikes.
What Does Farm Fire Insurance Cover—And What It Doesn’t
When you invest your heart and soul into your farm, knowing exactly what your farm fire insurance protects—and what it doesn’t—becomes crucial for safeguarding your agricultural livelihood. Let’s walk through what you can expect from a typical policy.
Covered Assets: Buildings, Equipment, Livestock, Crops
A solid farm fire insurance policy wraps its protective arms around the core elements of your farm:
Your farm buildings stand first in line for protection—those sturdy barns that have weathered generations, equipment sheds housing your valuable machinery, silos storing your harvest, and even your greenhouses nurturing next season’s crops. Most policies also cover milking parlors for dairy operations and those miles of fencing marking your boundaries (though fencing often needs a specific rider, so double-check your policy).
“I never thought we’d face a total loss,” shares one Wayne County farmer. “But when lightning struck our main barn last summer, our farm fire insurance covered not just rebuilding, but also the cleanup costs that would have bankrupted us otherwise.”
Your farm equipment represents a massive investment, and farm fire insurance typically covers tractors, combines, irrigation systems, and workshop tools damaged in a fire. For dairy farmers, this extends to milking equipment and feed distribution systems that keep operations running smoothly.
Livestock protection might be the most emotionally valuable coverage—policies typically cover animals lost directly to fire, those requiring euthanasia due to injuries, and often the veterinary expenses for treating survivors.
Your harvested crops don’t get left out either. That stored grain, feed, hay, seeds, and produce awaiting sale all represent income you’ve already worked for, and farm fire insurance helps ensure one blaze doesn’t erase a season’s worth of labor.
Most policies also include helpful extras like debris removal (typically 10-25% of your building coverage), fire department service charges, and temporary housing if your farmhouse becomes uninhabitable.
Want to learn more about comprehensive farm protection beyond fire coverage? Check out our detailed guide on Farm Policy Insurance.
Common Exclusions & Limitations You Must Check
Just as important as knowing what’s covered is understanding what’s not. Here’s where farmers sometimes face unwelcome surprises:
Farm fire insurance typically won’t cover fires resulting from intentional acts or arson by the policyholder. This makes perfect sense, but other exclusions might catch you off guard. Fires stemming from war or nuclear hazards are universally excluded, as are losses caused by neglected maintenance or code violations.
One exclusion that particularly affects farmers in regions with dry seasons: fires resulting from violation of burn bans or improper burning practices typically aren’t covered. Think twice before burning that brush pile during a drought!
“The most heartbreaking situations I’ve seen,” says Casey Love at Farm & Country Insurance, “are when farmers find too late that their policy contained unexpected limitations. Like the apple grower who found his policy covered fire damage to harvested fruit in storage, but not the specialized crates they were packed in.”
Be particularly watchful for sub-limits on certain categories of property. Your policy might cover hay and feed, but only up to a certain dollar amount that falls far below your actual inventory value. Similarly, check whether your policy provides actual cash value (depreciated) or full replacement cost for damaged items—the difference can be substantial for older buildings and equipment.
Geographic limitations can also create coverage gaps. A fire that jumps from a neighboring property might be excluded under some policies, leaving you exposed despite having insurance.
At Farm & Country Insurance, we’ve helped countless New York farmers steer these complex waters. We remember the vegetable farmer in Scipio who faced significant losses when a neighbor’s brush fire spread to their fields, only to find their policy specifically excluded such scenarios.
The best protection? Read your policy carefully and work with an agent who truly understands agricultural operations. Don’t hesitate to ask questions—your farm’s future may depend on it.
Assessing Your Risk & Setting the Right Coverage Limits
Getting your farm fire insurance coverage limits right isn’t just about checking a box—it’s about truly protecting your livelihood. As we help farmers across New York state, we’ve found that many don’t realize they’re underprotected until it’s too late.
Understanding Valuation Methods
When we sit down with farmers to review their coverage, we always explain the two main ways your property can be valued:
Replacement Cost Value (RCV) gives you the full amount needed to rebuild or replace your property at today’s prices. It doesn’t subtract for depreciation, which means higher premiums but much more complete protection. For that new barn you just built or that specialty tractor you invested in last year, RCV is usually the way to go.
Actual Cash Value (ACV) covers replacement cost minus depreciation—what your property is actually worth today, not what it would cost to replace. While this means lower premiums, it often leaves farmers short when they need to rebuild. I’ve seen farmers devastated to learn their policy will only cover a fraction of what they need after a fire.
“I thought I was saving money with my ACV policy,” one Cayuga County dairy farmer told me after a fire. “But that savings disappeared when I had to come up with an extra $50,000 out-of-pocket to rebuild my milking parlor.”
Location-Based Risk Factors
Your farm’s location plays a huge role in determining your fire risk. When we create policies at Farm & Country Insurance, we look at:
High-Risk Factors like how close you are to wildfire-prone areas, your distance from the nearest fire station (premiums typically jump when you’re over 5 miles away), and whether you have good water access for firefighting. We also consider if you’re in an area prone to drought or frequent lightning strikes.
For our New York farmers, these risks vary significantly by region. A farm in drier Genoa faces different wildfire concerns than operations in more humid areas like Sterling. We know these local differences matter, and they should be reflected in your coverage.
Choosing Appropriate Deductibles
Your deductible is more than just a number—it’s a financial decision that affects both your premiums and your farm’s cash flow after a loss.
With higher deductibles, you’ll enjoy lower premium costs, but you’ll need more cash reserves to cover losses when they happen. This approach often works well for established operations with strong cash positions.
Lower deductibles mean higher premiums but less financial strain right after a loss. For many of the smaller and newer farm operations we work with across New York, this option provides valuable peace of mind.
Avoiding Underinsurance
I’ve sat across the kitchen table from too many farmers who finded they were underinsured only after a fire. According to research from the Food and Agriculture Organization, this is distressingly common.
The most frequent underinsurance problems we see include:
- Not updating coverage after adding new buildings or equipment
- Failing to account for rising construction costs (which have skyrocketed in recent years)
- Overlooking the true value of specialized equipment
- Forgetting to include coverage for debris removal (which can cost tens of thousands of dollars)
- Not planning for temporary operations during rebuilding
“When we built our new hay barn last year, we completely forgot to call our insurance agent,” admitted one farmer from Owasco. “If that lightning strike had happened three months later, we would have lost $200,000 in uninsured property.”
At Farm & Country Insurance, we encourage all our farm clients to do a thorough inventory and valuation check annually, plus any time you make significant purchases or improvements. Is Your Farm Property Underinsured? The answer might surprise you—and knowing could save your operation.
The scientific research on agricultural disaster frequency from the FAO confirms what we’re seeing on the ground—disasters affecting farms are happening three times more frequently than they did in the 1970s and 1980s. Making sure your coverage keeps pace with this changing reality isn’t just smart business—it’s essential for your farm’s survival.
Prevent, Protect, Save: Fire Mitigation Strategies That Lower Premiums
Protecting your farm from fire isn’t just about avoiding disaster—it can also save you money on your farm fire insurance premiums. As a farmer, you already know that an ounce of prevention is worth a pound of cure, especially when it comes to fire safety.
Creating Defensible Space
Nothing creates peace of mind quite like having a buffer zone around your farm buildings. I’ve visited hundreds of farms across New York, and those with proper defensible space consistently fare better when wildfires threaten.
“It’s never too early to prepare,” a fire prevention specialist once told me, and I’ve shared this advice with countless Farm & Country Insurance clients.
The magic number is 30—maintain at least 30 feet of cleared area around farm buildings that are less than 50 feet apart. This means removing or reducing vegetation, keeping flammable materials like hay and fuel at safe distances, and ensuring emergency vehicles have clear access routes to your buildings.

Electrical Safety Measures
I’ve seen too many farm fires start from faulty wiring. Your electrical system deserves regular check-ups just like your tractor.
Schedule annual inspections with a qualified electrician who understands agricultural operations. Those old knob-and-tube systems in barns built in the 1940s? They weren’t designed to handle modern equipment loads. Consider upgrading outdated wiring and installing proper grounding systems.
Don’t forget about those pesky rodents either—they love to chew on wires. Protect your electrical systems from damage by wildlife and livestock. Many Farm & Country Insurance clients have found that investing in arc fault circuit interrupters (AFCIs) provides an extra layer of protection.
Hay and Silage Management
“My neighbor’s hay spontaneously combusted last summer,” a dairy farmer in Cayuga County told me recently. “If they’d been monitoring moisture levels, they might have caught it before it ignited.”
Properly cured hay (with 15-20% moisture content) dramatically reduces fire risk. During those first few weeks after baling, regular temperature checks can alert you to potential problems before they burst into flames. A simple moisture meter and temperature probe are small investments compared to losing your entire hay storage.
Keep your hay storage areas well-ventilated and consider storing hay in smaller, separated stacks rather than one massive pile. This approach limits the spread of fire if one section does ignite.
Strategic Equipment Placement
Hot equipment and combustible materials don’t mix. After a long day of harvesting, it’s tempting to park the combine wherever it’s convenient—but taking a few extra minutes to park away from hay and straw storage could save your farm.
Keep equipment fire-ready by cleaning chaff and debris regularly, maintaining exhaust systems, and keeping fully charged fire extinguishers on tractors and combines. And yes, I know it sounds obvious, but I’ve seen too many close calls—establish designated smoking areas away from barns and equipment.
Premium Credits and Discounts
Here’s where your prevention efforts pay off twice: first in avoided disasters, and second in lower insurance costs. At Farm & Country Insurance, we reward farmers who take fire prevention seriously.
Installation of fire detection systems can earn you significant premium discounts. Other money-saving improvements include on-site water sources for firefighting, lightning protection systems, and upgraded electrical systems.
Many of our clients have saved 15-25% on their farm fire insurance premiums simply by implementing and documenting regular safety inspections and employee fire safety training programs.
We’re happy to conduct on-site risk assessments for farms throughout New York. Our specialists can help identify the most cost-effective improvements for your specific operation that both improve safety and reduce your insurance costs.
Learn more about how to prevent a barn fire and protect your agricultural investment for generations to come. The team at Farm & Country Insurance is always ready to help you develop a fire prevention plan custom to your unique operation.
Filing a Claim & Tapping Additional Support After a Fire
When disaster strikes, knowing how to steer the claims process can make all the difference in your farm’s recovery. Despite our best prevention efforts, fires can still happen—and that’s when your farm fire insurance truly proves its worth.
Step-by-Step Claim Checklist for Farm Fire Insurance
The moments after a farm fire are overwhelming, but following these steps will help smooth your path to recovery:
First and foremost, ensure everyone’s safety. Account for all family members and employees, secure temporary shelter if needed, and keep everyone away from damaged structures until authorities give the all-clear. Your family’s wellbeing always comes first.
Once safety is established, documentation becomes your most powerful tool. Take extensive photos and videos of all damage before cleanup begins—these visual records will be invaluable during the claims process. Create detailed inventories of everything affected: structures, equipment, livestock, and crops. If you have pre-fire photos showing your property’s condition, gather those too. And save every receipt for emergency expenses and temporary repairs—they may be reimbursable.
“The photos I took immediately after our barn fire made all the difference in our claim,” shares one Farm & Country Insurance client from Scipio. “My agent walked me through exactly what the adjuster would need to see.”
Notify your insurer as soon as it’s safe to do so. When you call, provide basic information about the damage extent, ask about emergency funds availability, and clarify what temporary repairs you’re authorized to make. At Farm & Country Insurance, we pride ourselves on responding quickly to these urgent situations, often providing same-day assistance to farmers throughout Cayuga County.
Working effectively with your claims adjuster is crucial. Request someone familiar with agricultural operations—farm claims require specialized knowledge. Accompany the adjuster during property inspections, providing documentation of asset values through purchase receipts or appraisals. Don’t hesitate to ask questions about anything confusing in the process.
While waiting for the full claims process, make reasonable temporary repairs to prevent further damage. Tarp damaged roofs, secure livestock, and take necessary steps to protect what remains—just be sure to document all expenses and save damaged materials until the adjuster has inspected them.
When settlement offers arrive, review them carefully against your policy limits and coverage terms. For large or complex claims, consider consulting with a public adjuster. Understand the difference between actual cash value (depreciated) and replacement cost settlements, and be aware of any deadlines for accepting settlements or filing appeals.
How Insurance Interacts With Federal & State Disaster Programs
Your farm fire insurance is just one piece of the recovery puzzle. Government assistance programs can provide additional support:
The USDA Risk Management Agency (RMA) administers federal crop insurance that may supplement your private coverage for crop losses. Fire damage coverage varies by policy type and fire cause, so understanding how your policies work together is essential. In 2021 alone, the RMA provided over $7 billion in claims covering more than 45 million acres of farmland.
Farm Service Agency (FSA) offers several helpful programs after fire disasters. Their emergency loans can provide crucial rebuilding capital, while specific programs address livestock losses, conservation needs, and assistance for damaged orchards and vineyards.
“After losing our main barn and equipment storage to lightning, we didn’t realize we qualified for both insurance coverage and FSA assistance,” explains a dairy farmer from Moravia. “Our Farm & Country Insurance agent helped us coordinate both claims, which made recovery possible.”
The Small Business Administration (SBA) provides low-interest disaster loans that can cover losses not fully compensated by insurance. These loans are available to farms structured as businesses and can provide additional rebuilding resources when insurance limits are reached.
Don’t overlook potential tax relief options. Fire losses may qualify for casualty loss deductions on federal taxes, and you might be eligible to defer capital gains on insurance proceeds. New York also offers state-specific tax relief programs worth exploring.
At Farm & Country Insurance, we believe our job extends beyond simply processing claims. Our specialists help farmers throughout New York steer the complex interplay between private insurance and government assistance programs, ensuring you access every available recovery resource after a fire loss.
Frequently Asked Questions about Farm Fire Insurance
Does farm fire insurance pay for crop fires started off-property?
This question causes so much confusion among farmers, and with good reason. The answer isn’t straightforward and depends entirely on the specific terms in your policy:
Farm fire insurance policies vary widely in how they handle fires that originate elsewhere. Some comprehensive policies will cover fire damage regardless of where the fire started, while others specifically limit coverage to fires caused by certain sources like lightning strikes.
“I’ve seen too many farmers devastated twice – first by the fire itself, then by finding their policy excluded fires that spread from neighboring properties,” shares one of our clients at Farm & Country Insurance.
Many standard policies actually exclude coverage for fires that spread from adjacent properties unless the original cause was a covered peril like lightning. The good news is that additional endorsements are often available to fill this critical coverage gap.
If you’re unsure about your protection, give us a call at Farm & Country Insurance. We’ll help you review your policy and get written clarification on whether you’re covered for fires that might spread from neighboring land – before you need to file a claim.
How is premium calculated for hobby farms under 50 acres?
For small hobby farms, farm fire insurance pricing considers several key factors that reflect your unique operation:
Your premium will be influenced by the replacement cost of your farm buildings and structures – newer, larger, or specialty buildings typically mean higher premiums. The equipment you store (and its value) plays a major role too.
“When I started my small lavender farm, I was surprised that my specialty harvesting equipment actually impacted my premium more than the small outbuildings,” notes a hobby farmer from Cayuga County.
Other key factors include whether you have livestock (and their value), your annual farm revenue (with many specialized hobby farm policies available for operations under $50,000), and safety considerations like your distance from the nearest fire department and water sources.
Insurers also look at the construction materials and age of your farm buildings, your claims history, and any fire prevention measures you’ve implemented.
The good news for small farm owners? Insurance for hobby farms can start around $1,500 annually, though costs vary based on these factors. At Farm & Country Insurance, we specialize in finding affordable coverage solutions for small-scale agricultural operations throughout New York.
Can I bundle liability and fire coverage in one policy?
Absolutely! Not only is bundling farm liability and fire coverage possible, it’s actually the approach we recommend for most farmers. Here’s why:
Combining these coverages into one comprehensive farm package typically saves you money through multi-coverage discounts – often 10% or more off your premium. Beyond the financial benefits, bundling simplifies your policy management (one renewal date, one payment) and reduces the chance of dangerous coverage gaps that can occur between separate policies.
Farm fire insurance works best when it’s part of a cohesive risk management strategy that addresses all aspects of your operation. With bundled coverage, you’ll also benefit from coordinated claims handling if you ever experience a loss that affects multiple areas of your farm.
“Having everything with one company made all the difference when we had that electrical fire last year,” explains one of our dairy farming clients. “Our adjuster understood both the property damage and the business interruption aspects without us having to explain our operation to multiple people.”
At Farm & Country Insurance, we customize comprehensive farm packages that include both property (fire) and liability coverage custom to your specific operation. This integrated approach ensures you have consistent protection across all aspects of your farm, with one trusted partner handling your entire insurance program.
Conclusion
When your livelihood depends on your land and what you build upon it, farm fire insurance isn’t just another expense—it’s essential protection for your agricultural legacy. From the small hobby farm tucked away in Owasco to the sprawling dairy operation in Sennett, proper fire coverage gives both financial security and much-needed peace of mind.
The hard truth is that the stakes are simply too high to leave to chance. With disasters hitting farms three times more frequently than in decades past—and farmers shouldering a staggering 63% of these costs—comprehensive farm fire insurance has become more crucial than ever before.
As you consider your coverage options, keep these vital points in mind:
That standard homeowners policy sitting in your filing cabinet? It won’t cover your barn, equipment shed, or any farm operations when flames strike. The details within your policy matter tremendously—especially regarding how fires start and where they originate. And those coverage limits need regular updates as your operation grows and changes to prevent devastating underinsurance.
I’ve seen how implementing solid fire prevention measures not only protects your farm but often reduces your premiums significantly. And should the unthinkable happen, documenting everything thoroughly and reporting promptly can make all the difference in your claim.
At Farm & Country Insurance, we’ve been walking alongside New York farmers since 1984, providing specialized insurance solutions built on a deep understanding of what you face every day. Whether you’re managing a dairy herd, harvesting grain, tending fruit orchards, or growing vegetables, we design coverage packages that address your operation’s specific needs and vulnerabilities.
Don’t wait for disaster to strike before finding gaps in your protection. Contact Farm & Country Insurance today to review your current farm fire insurance coverage. Let us help ensure that the agricultural legacy you’re building remains safe for years to come.