
Why Farm Homeowners Insurance Matters for Your Farm
Farm homeowners insurance is a specialized policy designed to protect your family’s home, personal property, and farm structures from typical risks, as well as unique farming activities not covered by standard homeowners policies.
To help you quickly compare and decide, here’s what farm homeowners insurance typically covers:
- Your Home and Belongings: Coverage for your house, furniture, appliances, and personal items.
- Farm Buildings and Structures: Includes barns, sheds, silos, and other outbuildings.
- Farm Equipment and Machinery: Protects expensive gear like tractors, harvesting machines, and tools.
- Livestock and Crops: Coverage for animals and harvested crops against defined perils.
- Farm-Related Liability: If someone gets hurt on your farm, or your farming activities cause property damage.
Standard homeowners insurance usually excludes protection for your farming operations, leaving major gaps in coverage.
I’m Casey Love, founder of NY Farm Insurance Company, where I’ve spent my career helping farmers secure reliable farm homeowners insurance. At Farm & Country Insurance, we specialize exclusively in farm protection, ensuring your farm and home assets stay covered—no matter what comes next.

Relevant articles related to farm homeowners insurance:
– farm bureau business liability insurance
– farm family ins
– small farm business insurance
Understanding Farm Homeowners Insurance
When you run a farm, your home isn’t just a cozy place to rest your head—it’s also the heartbeat of your business. That cozy farmhouse kitchen? Sometimes it’s a boardroom. The old barn out back? Your equipment showroom. Because your home and farm are so closely intertwined, regular homeowners insurance simply won’t cut it.
That’s where farm homeowners insurance steps in. It blends the warmth and security of traditional homeowners coverage with specialized protection designed for farms. It recognizes that your risks go way beyond just your house—covering your barns, sheds, equipment, livestock, crops, and even the unique liabilities that come with running a farm.

“Our very name says we understand farmers and ranchers,” says one of our longtime agents here at Farm & Country Insurance. “Protecting both your home and farm under one policy just makes sense. It gives peace of mind to farm families no matter their size or the type of farming operation they have.”
Here’s a simple breakdown highlighting how farm homeowners insurance differs from the standard homeowners policy you’re probably used to:
| Coverage Aspect | Standard Homeowners Insurance | Farm Homeowners Insurance |
|---|---|---|
| Dwelling Structure | ✓ | ✓ |
| Personal Property | ✓ (limited coverage) | ✓ (higher limits custom for farm families) |
| Outbuildings | Limited (usually garages or small sheds) | ✓ (barns, silos, equipment sheds, and more) |
| Farm Equipment | ✗ | ✓ |
| Livestock | ✗ | ✓ |
| Harvested Crops | ✗ | ✓ |
| Liability from Farm Operations | ✗ | ✓ |
| Business Income Interruption | ✗ | Optional |
| Chemical Drift Liability | ✗ | Optional |
What Is Farm Homeowners Insurance?
Simply put, farm homeowners insurance is a policy designed just for folks who live and work on farms. It’s a smart combo of regular home insurance and farm-specific coverage, all rolled into one. Instead of juggling multiple policies, you get comprehensive protection that’s custom specifically for your farming life.
Because no two farms are exactly alike, farm homeowners policies are fully customizable. Whether you’re running a small hobby farm, a family-owned dairy, or a larger produce operation, you can adjust coverage limits and add endorsements to make sure every aspect of your farm is protected.
At Farm & Country Insurance, we’ve been helping farmers across New York since 1984, crafting policies that fit like your favorite pair of work boots—comfortable, reliable, and perfectly suited to your farm’s unique needs.
An experienced farm insurance expert, Douglas Bolerjack, sums it up well: “One of the biggest mistakes people make is assuming a standard homeowners policy covers all their valuable farm gear and livestock. It doesn’t. That’s why specialized farm coverage is essential.”
How It Differs from Standard Homeowners Insurance
Standard homeowners insurance is made for your typical house in town or suburbia. But let’s be real—on a farm, there’s nothing “typical” about the risks you face every day.
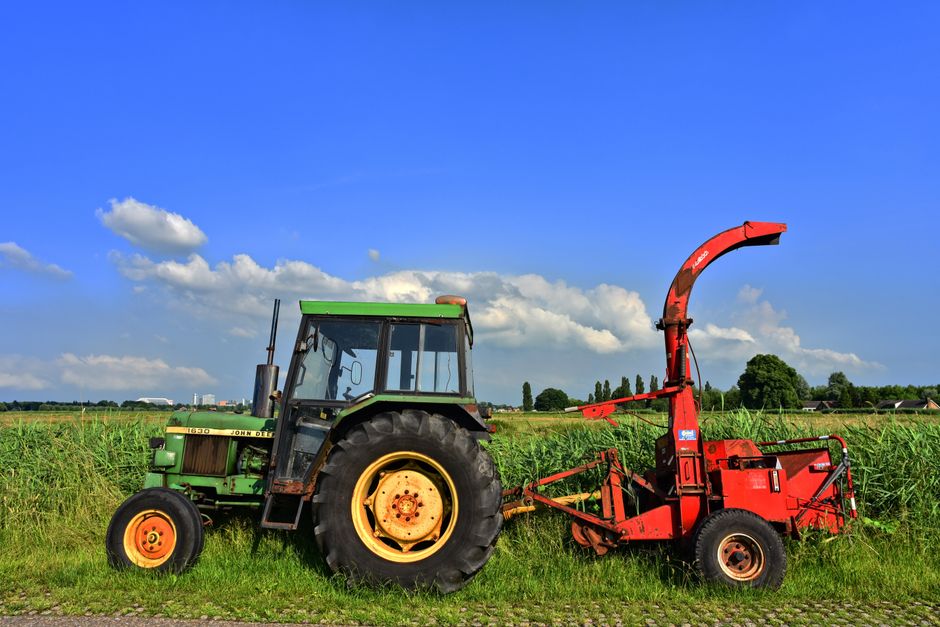
Your farm has specialized equipment, animals, structures, and activities that regular homeowners insurance just wasn’t built to handle. For example:
Farm equipment like tractors, combines, and harvesters are usually excluded under regular home policies—but they’re covered under farm policies.
Livestock coverage protects your valuable animals from accidents, certain illnesses, and natural disasters—risks standard homeowners insurance doesn’t touch.
Outbuildings such as barns, silos, equipment sheds, and even corn cribs are typically left out of regular homeowners policies, which usually only cover small sheds or detached garages. Farm homeowners policies, however, are built to cover all these indispensable farm structures.
Farm liability is another critical gap. On a working farm, unexpected things can happen—visitors may be injured by livestock, equipment could accidentally damage neighboring property, or people could become ill from the produce you sell. Regular homeowners policies won’t cover these liability risks, but farm homeowners coverage will.
And let’s not forget about harvested crops. Standard home policies won’t cover your harvested corn, apples, pumpkins, or other produce. Farm homeowners insurance, on the other hand, can include protection for these valuable assets.
As one insurance expert puts it, “At first glance, farm insurance and homeowners insurance might seem similar. But the deeper you dig, the bigger the differences become—and those differences can be critical for farmers.”
At Farm & Country Insurance, we’re here to help you steer these differences and ensure your farm and home have the comprehensive protection they need. Curious if your farm requires a specialized policy? Take a look at this helpful resource: Does a Farm Need a Different Homeowners Insurance Policy?.
Typical Coverages in Farm Homeowners Insurance Policies
When you’re running a farm, your home isn’t just a place for you and your family to relax after a busy day—it’s at the heart of your livelihood. Because of this unique setup, farm homeowners insurance provides a blend of protections not found in standard homeowners policies. At Farm & Country Insurance, we like to think of it as covering everything from your farmhouse kitchen to your cattle barn—and all the important assets in between.
A comprehensive farm homeowners policy typically includes coverage for your dwelling, personal property, farm equipment, livestock, and liability associated with farm operations. Understanding each piece is crucial in making sure nothing slips through the cracks.
Think of it this way: With the right coverage, you’ll sleep better at night knowing your farm and home assets are protected from life’s unpredictable events—like storms, fires, theft, or the occasional rogue cow (it happens more than you’d think!).
Dwelling and Personal Property Coverage
Like a standard home policy, dwelling coverage is the cornerstone of your farm homeowners insurance, safeguarding your home itself from covered perils like fire, wind, hail, lightning, and more. This protection extends to attached structures, such as garages or porches. If a windstorm sends a tree crashing onto your roof, dwelling coverage steps in to help cover repair costs, getting your home back to normal as quickly as possible.
Alongside this, your policy includes personal property coverage, protecting the belongings inside your home—appliances, furniture, clothing, electronics, even that antique cabinet handed down from grandma. Farm & Country Insurance often suggests opting for “replacement cost coverage” rather than “actual cash value.” Replacement cost coverage ensures you’ll receive enough funds to replace items at today’s prices without deductions for depreciation. Trust us—you’ll appreciate it when replacing your comfy couch or essential kitchen gadgets.
We also recommend keeping an updated home inventory with photos and descriptions of your belongings. It can be a real lifesaver if you ever have to file a claim.
Farm Personal Property and Equipment Coverage
On a farm, your equipment isn’t just expensive—it’s essential. From tractors and harvesters to irrigation systems and portable tools, farm machinery represents a significant investment. A standard homeowners policy typically won’t cover these specialized tools, but your farm homeowners policy from Farm & Country Insurance will.
Coverage includes tractors, harvesting equipment, irrigation setups, portable sheds, tools, supplies, seeds, fertilizer, and even harvested crops stored on-site. Given that a single combine harvester can cost upwards of $300,000, making sure you have the right coverage is critical. You can choose between actual cash value or replacement cost coverage, and we always recommend the latter, since it ensures your policy pays to replace damaged or lost equipment at today’s prices—no depreciation worries here.
Additionally, you might want to consider equipment breakdown coverage. This optional coverage protects you from unexpected mechanical or electrical breakdowns—not typically covered under standard farm policies. For more details about equipment protection, take a look at more info about farm equipment insurance coverage.
As we always remind our clients at Farm & Country Insurance, “Farm equipment isn’t just machinery—it’s your livelihood. Protecting it properly is just good business sense.”
Liability Coverage for Farm Operations
Here’s something you already know well: running a farm means dealing with risks not common to the average homeowner. Let’s face it—cows don’t always respect fences, and not everyone knows how to safely approach farm equipment. Farm liability risks range from visitors getting injured on your property to your livestock causing accidents on nearby roads. That’s why liability protection is a crucial part of a farm homeowners insurance policy.
Farm liability coverage protects you if visitors are injured on your property or if your farming operations cause property damage elsewhere. It can cover premises liability (if someone slips on ice near your barn), operations liability (damage caused by your equipment), and product liability (your farm-grown vegetables cause illness). It can even help cover legal defense fees if someone sues you—because lawsuits, unfortunately, do happen.
For example, imagine your livestock escape through a damaged fence and cause a traffic accident, or a visitor trips on farm equipment and gets hurt. Liability coverage steps in to handle medical bills, legal expenses, and settlements, shielding you from the potentially devastating financial consequences.
At Farm & Country Insurance, we understand that liability risks vary widely depending on your specific farming operations. Dairy farms, fruit orchards, or vegetable operations each face unique scenarios, and we’ll help tailor your liability coverage to match your farm’s needs perfectly.
Livestock and Farm Structures Coverage
Since farm animals and specialized farm structures can be some of your biggest assets, your farm homeowners policy includes protections custom specifically for them. Livestock coverage protects your animals from risks like injury, theft, or death due to covered perils, such as fire, lightning, or certain diseases.
When it comes to farm structures—like barns, silos, sheds, and workshops—these can represent substantial investments. Standard homeowners insurance usually doesn’t cover these or provides minimal coverage at best. Under a farm homeowners insurance policy, these essential structures get the dedicated protection they deserve against storms, fires, theft, and more.
As our team at Farm & Country Insurance always says, “Your outbuildings aren’t just structures—they’re where the magic (and hard work!) happens.” Farm structure coverage means that when disaster strikes, you’ll have the financial help needed to repair or rebuild quickly.
Farm Products and Harvested Crops Coverage
Another area often overlooked by standard policies—but fully understood by Farm & Country Insurance—is coverage for products and harvested crops. This coverage protects feed, seed, harvested grain, vegetables, fruits, and other stored farm products. When unexpected events like fire or severe storms harm these valuable assets, having proper coverage provides you peace of mind and ensures your farm operation can bounce back.
With the right farm homeowners insurance policy, you’re protecting your home, family belongings, and all the unique aspects of your farming operation. At Farm & Country Insurance, we understand farms because farms are our specialty. We’ve been helping New York farmers protect their livelihoods since 1984, offering policies built just for farm families like yours.
Protecting Against Farming-Specific Risks
When you run a farm, you face challenges that city folks just don’t understand. A sudden hailstorm isn’t just inconvenient – it could wipe out your entire crop. A broken tractor during harvest isn’t just annoying – it might threaten your whole year’s income. These unique situations demand protection that goes well beyond what a standard home policy offers.
That’s why farm homeowners insurance exists – to protect against these specialized farming risks. At Farm & Country Insurance, we’ve spent nearly four decades getting to know the specific challenges faced by New York farmers, whether you’re running a dairy operation in Cayuga County or tending apple orchards in the Hudson Valley.
The farming life comes with its own set of worries. Severe weather events can devastate crops and damage buildings in minutes. When equipment breaks down during planting or harvest, every hour of downtime costs you money. Livestock health issues can threaten animals you’ve raised with care. Market fluctuations might slash prices just when you’re ready to sell. And environmental challenges like chemical drift can create liability headaches you never anticipated.
As one of our insurance specialists likes to say, “You chose farming for the love of it. Now, make sure you have the right protection in place for both your home and your farm.”
Examples of Farming Risks Covered
Let me walk you through some real-world situations where farm homeowners insurance provides protection that standard policies simply don’t address:
Barn Fires represent one of the most devastating risks for any farm. The combination of hay storage (which can spontaneously combust under certain conditions), electrical systems, and valuable equipment creates a unique fire hazard. When a barn burns, the losses can be enormous – not just the building itself, but everything inside it.
I remember working with a dairy farmer in Central New York whose historic barn caught fire after a lightning strike. Without proper farm insurance, he would have lost not just the structure but all the equipment and feed stored inside – a financial blow that might have ended his family’s century-old farming tradition.
Livestock Mortality protection is another crucial coverage for many farms. Your animals represent both a significant investment and, for many farmers, a labor of love. Whether it’s prize dairy cows you’ve bred for generations or a flock of specialty poultry, losing animals to disease, accidents, or natural causes can be emotionally and financially devastating.
One Farm & Country Insurance client faced disaster when a severe winter storm caused their barn roof to partially collapse, injuring several of their cattle. Their farm homeowners insurance helped cover both the veterinary costs for the surviving animals and the replacement value of those lost – keeping their operation viable through a difficult time.
Equipment Theft or Damage is a growing concern for many farmers. Modern farm equipment represents a massive investment – a new tractor can easily cost over $100,000, and specialized harvesting equipment even more. When this equipment is damaged, stolen, or destroyed, your farm’s operations can grind to a halt.
We recently helped a vegetable farmer in the Finger Lakes region who had a tractor stolen right from their field during harvest season. Their farm homeowners insurance covered the replacement, allowing them to get back to work quickly during this critical time.
Crop Damage can wipe out months of hard work in minutes. While specialized crop insurance (often tied to federal programs) covers growing crops, many farm policies include protection for harvested crops stored on your property. When a farmer’s grain storage bin was damaged in a windstorm last year, causing moisture damage to the stored corn, their farm policy helped cover the loss – protecting income they’d already earned through successful growing and harvesting.
At Farm & Country Insurance, we understand these farming-specific risks because we’ve been helping New York farmers manage them since 1984. We know that protecting your livelihood requires more than just a standard policy – it demands insurance that’s as specialized and hardworking as you are.
Customizing Your Farm Homeowners Insurance
Farming isn’t a one-size-fits-all business, and your insurance shouldn’t be either. One of the greatest advantages of farm homeowners insurance is its flexibility—you can tailor your coverage to match your unique operation and needs.
At Farm & Country Insurance, we take pride in creating personalized policies for New York farmers. Whether you’re milking cows in Cayuga County, growing tomatoes in Sennett, or tending apple trees in Owasco, we understand that your farm has its own distinct character and challenges.
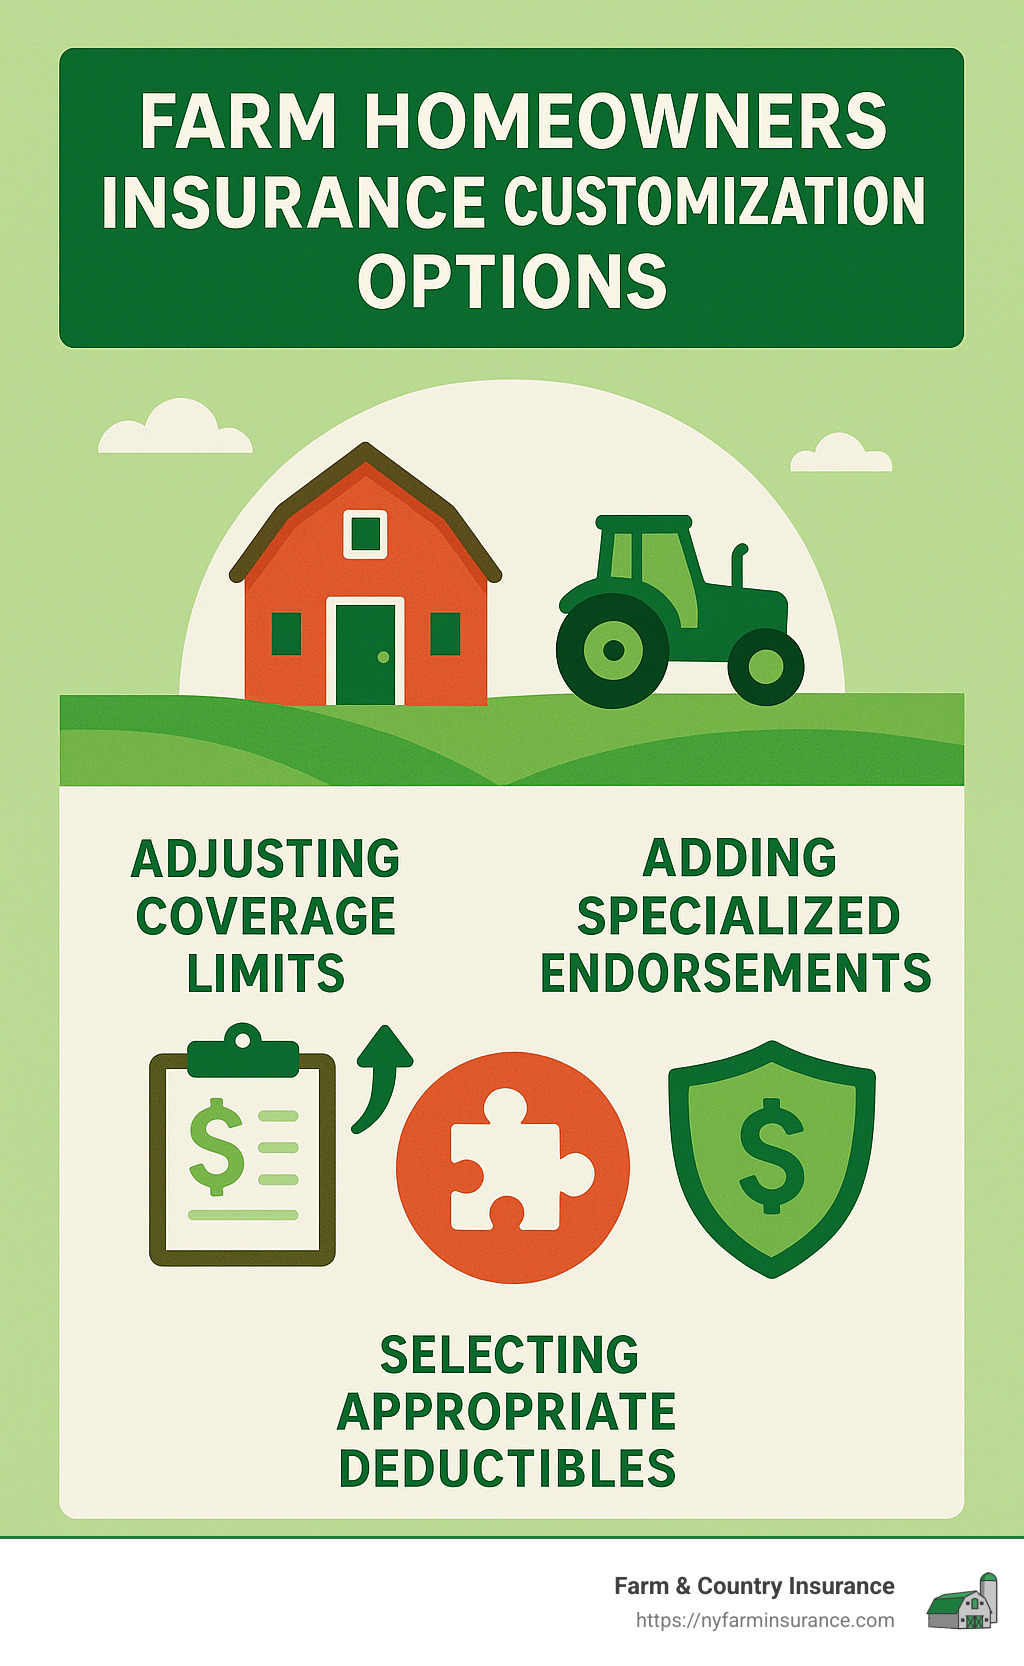
When we sit down with farmers to customize their coverage, we typically look at several key areas. You might need to adjust coverage limits to properly protect that new barn you built or the additional acreage you purchased. We can add specialized endorsements if you’ve branched into farm-to-table dinners or started welcoming school tours. Many farmers benefit from carefully selecting appropriate deductibles that balance monthly costs against what they could comfortably pay out-of-pocket after a loss.
For farms that can’t afford downtime, business interruption coverage provides income replacement if a covered disaster temporarily halts your operation. And with growing environmental concerns, many of our clients add pollution protection to cover cleanup costs or chemical drift liability.
As one farmer told us after customizing his policy, “I sleep better knowing my coverage fits my farm like my favorite work boots—comfortable and ready for whatever comes my way.”
Factors Influencing the Cost of Farm Homeowners Insurance
Understanding what affects your premium can help you make smart coverage choices while potentially finding ways to save. When we calculate farm homeowners insurance costs at Farm & Country Insurance, several key factors come into play.
Your farm’s size and value naturally impact your premium. A 500-acre operation with multiple barns, silos, and a fleet of equipment will generally cost more to insure than a 50-acre farm with minimal structures. This makes sense—more assets mean more potential loss to cover.
The type of farming you do significantly affects your rates. A dairy farm has different risk exposures than a vineyard. If you welcome visitors for hayrides or U-pick berries, your liability concerns increase compared to farms without public access. We’ve seen this with our New York clients who’ve diversified into agritourism—their coverage needs evolve as their business models change.
Your location matters more than you might think. Farms closer to fire stations often qualify for better rates. Regional weather patterns play a role too—areas prone to severe storms or flooding may face higher premiums. Even local building costs affect your rates, since they determine potential rebuilding expenses.
As with most insurance, your coverage limits and deductibles directly impact what you pay. Higher limits mean greater protection but higher premiums. Increasing your deductible from $1,000 to $5,000 typically lowers your premium—but you’ll need to be comfortable covering that larger amount if disaster strikes.
Your claims history tells insurers a lot about your risk level. A farm with multiple claims in recent years will generally pay more than one with a spotless record. This applies to both personal claims and those related to your farming operation.
Finally, farm safety features can earn you discounts. Modern electrical systems, security cameras, fire suppression equipment, and other safety investments not only protect your farm but often reduce your insurance costs too.
Discounts and Ways to Save
Despite the specialized nature of farm homeowners insurance, there are plenty of ways to keep your coverage affordable without cutting corners on protection. At Farm & Country Insurance, we’re committed to helping New York farmers find that sweet spot between comprehensive coverage and manageable costs.
Bundling policies is perhaps the easiest way to save. When you combine your farm policy with auto insurance, personal umbrella coverage, or other policies, the discounts can be substantial. Many of our clients save 10-15% through bundling alone. One dairy farmer in Central New York recently saved over $800 annually by consolidating all his policies with us.
Your farming practices themselves can lead to savings. Strong risk management demonstrates to insurers that you’re a safer bet. Do you have a written safety plan? Regular equipment maintenance schedules? Emergency response procedures? These practices not only protect your farm but can translate to premium discounts.
Smart investments in safety and security often pay for themselves through insurance savings and prevented losses. Updating that old barn wiring might seem expensive, but it reduces fire risk dramatically. Installing security lighting and cameras deters theft. Weather alert systems provide crucial warning time before storms. One apple grower we work with installed a comprehensive lightning protection system and saw his premium drop by 8%.
Loyalty has its rewards in farm insurance. Many of our clients enjoy claim-free and longevity discounts that grow over time. Staying with the same insurer for multiple years and maintaining a clean claims record can lead to significant savings—we’ve seen discounts up to 20% for long-term customers with spotless histories.
Even how you pay your premium can affect your bottom line. Many insurers offer discounts for paying annually instead of monthly, or for setting up automatic payments. While these might only save 2-5%, that’s money that stays in your pocket.
Finally, carefully considering your deductible can lead to substantial savings. By raising your deductible from $1,000 to $2,500 or higher, you might reduce your premium by 15-20%. Just make sure you have enough set aside to cover that higher deductible if needed.
As one of our farm clients likes to say, “Penny-wise and pound-foolish doesn’t work in farming or insurance.” At Farm & Country Insurance, we help you find meaningful savings without compromising the protection your farm needs to weather whatever challenges come your way.
Steps to Ensure Adequate Coverage for Your Farm
Getting the right farm homeowners insurance doesn’t have to be overwhelming—but it does require careful thought and planning. At Farm & Country Insurance, we’ve spent decades helping New York farmers build smart, custom insurance plans. Here’s how we recommend approaching the process to ensure your farm is always protected, no matter what comes your way.
First, it’s important to clearly identify your farm’s unique risks. Sit down and take some time to imagine various scenarios that could affect your operation. Think about natural disasters common to your region—like severe storms, heavy snow, or even flooding. Consider what might happen if your essential farm equipment suddenly broke down right before harvest. Don’t forget to factor in liability risks, like visitors slipping on your property or livestock causing damage off-site.
Once you’ve got a good sense of what might go wrong, the next step is to create a detailed farm inventory. Go beyond just jotting down equipment and livestock numbers. Instead, document everything—including farm structures like barns, sheds, and silos, all your machinery and tools, stored crops and feed, and even your household belongings. Take plenty of pictures, save receipts whenever possible, and estimate current values. This detailed inventory is incredibly useful, both for deciding how much coverage you need and for quickly handling claims down the road.
With your inventory ready, carefully review any farm insurance coverage you already have. Look closely at the details—especially the coverage limits and deductibles. Are your farm buildings and equipment adequately protected? Are there exclusions or limitations you weren’t aware of that could leave you vulnerable? Evaluating your current policies lets you spot gaps and adjust your coverage before an unexpected event occurs.
Next, imagine how your farm would manage after a major loss. Would you need additional living expenses coverage to stay somewhere else while your home is repaired? Would your farm income suffer if you couldn’t operate temporarily? Business interruption coverage can help you maintain cash flow during tough times, while extra expense coverage can cover the additional costs needed to keep your farm running smoothly at another location.
Farms change constantly. You buy new equipment, expand your operations, change the types of crops or livestock you manage, or even offer new agritourism activities. It’s crucial to regularly review and update your farm homeowners insurance policy to reflect these changes. At Farm & Country Insurance, we often remind our clients, as one of our industry friends likes to say:
“Regularly reassess your insurance needs as your farm evolves from a hobby to a business operation.”
We recommend sitting down with your agent at least once a year—or whenever you experience major changes—to ensure your policy keeps pace with your farm’s growth.
Working with an Experienced Agent
Perhaps the single best way to ensure you have the right farm homeowners insurance is to work with an agent who deeply understands farming. At Farm & Country Insurance, our agents don’t just know insurance—they also know farming. From dairy operations in Cayuga County to apple orchards in the Finger Lakes, our team has the experience needed to help New York farmers choose the right coverage.
A good farm insurance agent will take the time to get to know you and your farm. They’ll ask questions that get to the heart of your operation, like what crops or livestock you raise, what kind of equipment you depend on, if you welcome visitors for events or tours, and how you market your products. This thorough approach ensures your coverage truly matches your farm’s unique risks.
Your agent should also clearly explain all your coverage options, breaking down complex terms so you fully understand what’s included (and what’s not). Farm insurance can feel complicated, but a knowledgeable agent can simplify the details and help you choose wisely.
Beyond just selling policies, a great agent provides valuable guidance on reducing risks and preventing problems before they happen. At Farm & Country Insurance, we see ourselves as partners in your success—offering practical advice on farm safety, security improvements, and emergency planning.
And if the unexpected does happen, a knowledgeable farm insurance agent is your strongest advocate. They’re there to guide you through the claims process, making sure that you get fair, prompt coverage. As one of our clients recently said after a windstorm claim:
“Having an agent who’s walked my fields and understands what I do made all the difference. They knew exactly what we needed and helped us get back on our feet quickly.”
Your farm is your livelihood and legacy. Don’t trust your coverage to just anyone. Work with an experienced, caring professional who understands farming—and will stand by you through thick and thin.
For more helpful guidance on insuring your farm, check out our detailed resource on insurance for small farms.
Understanding Liability Issues on a Farm
Running a farm involves more than just growing crops or caring for animals—there are also serious liability risks involved. Compared to typical homeowners, farm owners face unique situations that could lead to liability claims. From visitors slipping in muddy areas, to accidents involving heavy machinery and livestock, farmers must be prepared for a range of scenarios.
That’s where farm homeowners insurance steps in. Unlike standard home insurance, farm-specific coverage helps protect against these farming-related liability exposures, giving you peace of mind to focus on your farm.
On your farm, people come and go frequently. You likely welcome family, friends, employees, delivery people, customers picking up fresh produce, or even families visiting for fun agritourism events. Each type of guest poses different liability considerations. For example, you’re expected to maintain a safe environment for customers and employees, while even trespassers have certain limited protections under the law.
Farm equipment and vehicles add another layer of complexity. Even the most careful farm operators can have accidents. For instance, if your tractor’s load of hay falls onto the road, causing an accident, or your equipment damages a neighbor’s fence, you could be held responsible. Liability coverage in your farm policy helps cover these kinds of unexpected mishaps.
Farm products also come with liability risks. Whether you’re selling milk, fresh vegetables, fruits, or homemade jams, there’s always a chance your products could inadvertently cause illness or injury. Your farm insurance policy provides products liability coverage, protecting you if someone gets sick or hurt after using products from your operation.
Environmental concerns are another area farmers must consider. Farming activities like spraying pesticides, handling manure, fueling equipment, or storing chemicals can lead to accidental pollution incidents. For example, pesticide drifting onto a neighbor’s property or manure runoff contaminating local water sources can trigger costly lawsuits. Farm & Country Insurance can help you add limited pollution liability coverage or suggest additional specialized endorsements if needed.
At Farm & Country Insurance, we’ve been protecting New York farms since 1984—meaning we’ve seen it all (seriously, ask us sometime about the cow-on-the-loose incident). We understand these complex liability concerns and help you identify areas where you might be vulnerable. That way, you can have coverage in place before something happens—not after.
How Farm Homeowners Insurance Addresses Liability
Farm homeowners insurance provides specialized liability coverage designed exclusively for farming operations. It’s different from standard home insurance because it accounts for the specific and diverse scenarios farmers face regularly.
Personal and farm liability coverage forms the backbone of your farm policy. If you’re legally responsible for someone’s injury on your property or accidentally cause damage to someone else’s property, this coverage kicks in. For example, if a delivery driver slips on ice near your barn and gets hurt, farm liability coverage would handle their medical expenses and any legal bills if they decide to sue.
Medical payments coverage complements liability protection by covering smaller medical bills for minor injuries on your property, even if you’re not considered at fault. This coverage can often prevent larger, more complicated claims by quickly addressing the injured person’s immediate medical costs—no lawsuits or blame necessary.
Products liability is another essential part of your farm coverage—especially if you sell directly to consumers or through local markets. Imagine someone claims your farm-fresh milk or strawberries made them sick. Products liability provides protection from claims related to illness or injuries caused by your farm products—ensuring one bad batch doesn’t jeopardize your entire operation.
Limited pollution liability coverage can sometimes be included or added as an endorsement. This coverage helps protect you if a spill or accidental release of chemicals, fuel, or other substances occurs. However, more comprehensive environmental issues often require additional specialized endorsements or separate policies. Be sure to ask your Farm & Country Insurance agent about the best way to protect your farm from environmental liabilities.
One often overlooked but crucial aspect of liability coverage is defense costs. Even if a liability claim against you turns out to be unfounded or exaggerated (and trust us, these happen!), legal fees can quickly pile up. Luckily, your farm insurance includes defense costs—covering attorneys’ fees and court expenses. This ensures you don’t have to empty your savings just to prove you’re not at fault.
For additional liability protection, consider an umbrella liability policy. Umbrella coverage adds an extra layer of protection beyond your standard farm policy. Typically available in increments from $1 million up to $10 million, umbrella coverage is a smart way to ensure a major liability claim doesn’t threaten your family’s financial future.
At Farm & Country Insurance, we know how important it is to protect your farm, your family, and everything you’ve worked hard to achieve. Our agents specialize in farm insurance and understand the unique liability risks of farming in New York. We’ll help you figure out exactly what you need—no more, no less—to keep your farm operation covered safely and affordably.
Common Exclusions in Farm Homeowners Insurance Policies
While farm homeowners insurance provides comprehensive protection custom to your farming lifestyle, it’s important to know that standard policies don’t cover everything. Understanding what’s typically excluded can help prevent unpleasant surprises and allow you to proactively fill any coverage gaps.
For starters, flood damage caused by rising water from external sources isn’t included in standard farm policies. Flooding can quickly damage your home, barns, equipment, stored crops, and livestock. The best solution is a separate flood insurance policy, usually available through the National Flood Insurance Program (NFIP). At Farm & Country Insurance, we often help our clients secure this additional coverage—especially important if your property is near a stream, pond, lake, or low-lying floodplain.
Likewise, earthquake damage typically isn’t covered in standard policies. New York isn’t exactly known for major quakes, but even mild tremors can cause structural damage to barns, silos, and homes. You can add an earthquake endorsement or separate earthquake policy to ensure you’re protected.
It’s also crucial to know what’s naturally not covered because it’s considered part of property ownership responsibilities. This includes normal wear and tear or gradual deterioration of structures and equipment. Regular maintenance might not sound like fun, but it’s necessary—insurance doesn’t cover property that deteriorates simply because it’s gotten older.
Additionally, intentional damage caused deliberately by the policyholder is obviously excluded (no surprises there!). Similarly, damage resulting from war, nuclear incidents, or government seizure is generally not insurable—though fortunately, these scenarios are extremely rare.
Some specialized farm-related business activities may also fall outside standard coverage and require unique endorsements. For example, if you’re offering farm-to-table dinners, hosting weddings, or providing farm stays, you’ll likely need additional coverage custom to these agritourism activities.
Here’s a quick reference table summarizing these common exclusions and how you can address them:
| Common Exclusion | Description | Alternative Coverage Option |
|---|---|---|
| Flood Damage | Damage caused by rising external water sources | Separate flood insurance policy |
| Earthquake Damage | Damage caused by earth movement | Earthquake endorsement or separate policy |
| Normal Wear and Tear | Gradual deterioration and lack of upkeep | Regular maintenance (not insurable) |
| Intentional Damage | Damage deliberately caused by the policyholder | Not insurable |
| Certain Business Activities | Specialized or agritourism activities | Additional business coverage endorsements |
| War and Nuclear Hazards | Damage from war, nuclear accidents, radiation | Generally not insurable |
| Government Action | Official seizure or destruction of property | Limited options available |
At Farm & Country Insurance, we make a point of discussing these exclusions openly and transparently with our clients. Our goal isn’t just to provide you a policy; it’s to ensure you truly understand your coverage and aren’t left vulnerable to unexpected losses.
Additional Coverages to Consider
If some of the above exclusions caught your attention, don’t worry—there are several valuable additional coverages you can explore to fill these gaps. At Farm & Country Insurance, we’ve spent decades working with New York farmers to make sure they’re fully protected.
Flooding can cause costly, widespread damage, so we highly recommend considering flood insurance through the NFIP or private insurers. While many farmers assume flooding isn’t a major risk, all it takes is one heavy storm to prove otherwise. We can guide you through the process of purchasing this important protection.
For earthquake protection, you can add an earthquake endorsement onto your existing policy or buy a separate earthquake insurance plan. The coverage cost is generally reasonable here in New York due to lower earthquake risk, making it a worthwhile consideration.
Given the significant investment in machinery and equipment, specialized equipment coverage can be a lifesaver. Options include equipment breakdown coverage, which protects against mechanical or electrical failures not covered by your main policy; replacement cost coverage, which lets you replace equipment with new items of similar quality; and rental reimbursement, which covers the cost of renting temporary replacement equipment during repairs.
Another popular option is umbrella liability insurance, which is especially valuable if you host farm visitors, sell products commercially, or have significant assets to protect. An umbrella policy adds an extra layer of liability protection—usually from $1 million up to $10 million above and beyond your standard farm liability coverage.
If your farm generates critical income, business interruption coverage might also be worth considering. This coverage helps replace lost income if a covered event temporarily halts your operations. Imagine your barn being severely damaged right before harvest season—business interruption coverage helps you pay ongoing expenses and keep your farm afloat while you rebuild.
If you have employees, don’t forget about workers’ compensation insurance, which is usually required by law. It covers medical bills, lost wages, and rehabilitation for workers injured on the job.
Finally, although not typically part of your farm homeowners policy, crop insurance is an important risk management tool that protects against crop losses from weather, price fluctuations, and other uncontrollable factors. Crop policies are often federally subsidized, and we can help you steer these options as well.
At Farm & Country Insurance, we pride ourselves on understanding the unique needs of New York farms—from dairies in Cayuga County to orchards and vegetable farms across the state. Together, we’ll help you identify and fill any gaps to keep your farm well-protected, come rain or shine.
For more detailed information on farm liability coverage, you can read our dedicated guide: More info about farm liability insurance.
Frequently Asked Questions about Farm Homeowners Insurance
Is Farm Homeowners Insurance Required?
While there’s no legal requirement in New York or most other states to have farm homeowners insurance, there are a few scenarios where it can feel mandatory.
For starters, if you have a mortgage on your farm property, your lender will almost always require you to have an insurance policy in place. They’re protecting their investment, and that means coverage for your dwelling (your home) and the farm structures that secure the loan.
Beyond lender requirements, having farm homeowners insurance is really just common sense. Farming can be unpredictable—think storms, fires, theft, or even a visitor slipping in your barn. Without a solid insurance plan, one incident could literally cost you the farm (and your sanity!).
Here at Farm & Country Insurance, we’ve seen how important custom coverage can be. Our team helps New York farmers protect what they’ve worked so hard to build, ensuring you’re never caught off guard by life’s unexpected curveballs.
Can I Bundle Farm Homeowners Insurance with Other Policies?
Absolutely, you can—and frankly, you probably should! Bundling your farm homeowners insurance with other policies is a smart move for your wallet and your peace of mind.
When you bundle your coverage, you can typically save money—often 10% or more—compared to buying multiple separate policies. It’s a great way to simplify your life: fewer bills, fewer calls, and fewer headaches. Plus, having everything under one roof means fewer gaps in coverage and easier claims handling.
At Farm & Country Insurance, we offer convenient bundling options for farmers across New York. You can combine your farm homeowners policy with other coverage such as auto insurance for your farm and personal vehicles, umbrella liability for extra protection, or specialized coverages like equipment breakdown and crop insurance.
Bundling your coverage can also help build a stronger relationship with your insurance provider. The better we get to know you and your farm, the more personalized our advice and support can be.
How Do I Choose the Right Farm Homeowners Insurance Policy?
Choosing the right farm homeowners insurance policy might feel overwhelming at first, but don’t worry—we’ll walk you through it. The most important thing is to find coverage that fits your unique farm and lifestyle.
To start, take a step back and assess your farm’s specific needs. Consider things like the value of your farmhouse, barns, equipment, and livestock. Think about any specialized activities you offer, such as farm tours or produce sales, and the additional risks they may bring.
Next, reflect on your financial comfort zone. Are you comfortable covering smaller losses yourself (by choosing a higher deductible), or would you prefer lower out-of-pocket costs in exchange for a slightly higher premium?
Finding the right agent makes all the difference. At Farm & Country Insurance, our experienced agents specialize in farming operations throughout the state—from dairy farms in Cayuga County to fruit orchards in the Finger Lakes. We’ll ask the right questions and explain your options clearly, guiding you toward coverage that matches your real-world risks.
When you’re comparing policies, try not to focus solely on price. Instead, look carefully at the coverage itself, including limits, exclusions, deductibles, and the insurer’s reputation for customer service and claims handling. Don’t worry; we’ll help you cut through the jargon to understand exactly what you’re getting.
Finally, before signing the dotted line, carefully review your policy documents. Make sure you’re comfortable with the perils covered, valuation methods (replacement cost vs. actual cash value), and any special restrictions or requirements. If anything isn’t crystal clear—just ask us!
Choosing insurance shouldn’t feel like navigating a corn maze in the dark. Here at Farm & Country Insurance, we’re committed to making the process straightforward, understandable, and maybe even a little fun. After all, you’ve got enough on your plate already, right?
Conclusion
When it comes to farming, your home isn’t just where you hang your hat—it’s the center of your personal life and the heart of your business. That’s why having the right farm homeowners insurance is about more than just ticking boxes. It’s about peace of mind, knowing that your family, your home, and your farming livelihood have solid protection in place.
At Farm & Country Insurance, we’ve been helping New York farmers secure their farms since 1984. Our experience has taught us just how unique each farm can be. Whether you’re running a dairy farm in Cayuga County, growing vegetables in Sennett, or tending orchards in Owasco, we understand your specific challenges. We don’t believe in one-size-fits-all solutions; we customize every policy to match your particular farm’s needs.
Throughout this guide, you’ve learned that farm homeowners insurance isn’t just regular home insurance with a farm label slapped on. It combines the best of both residential and commercial coverages, giving you protection for your home, outbuildings, farm equipment, livestock, crops, and the special risks that come along with farming.
Standard homeowners policies tend to leave big gaps when it comes to farming operations. Without proper farm-specific coverage, you could be left footing an enormous bill if disaster strikes. That’s why tailoring your insurance coverage is absolutely essential.
Farming evolves constantly, and your insurance should too. Regularly reviewing your policy ensures you’re fully covered as your farm grows and changes. As we often remind our customers: “Regularly reassess your insurance needs as your farm evolves.”
Working with an experienced agent isn’t just helpful—it’s crucial. At Farm & Country Insurance, our specialists ask the right questions, help you identify risks, and guide you in choosing the coverage that’s just right for you. Farmers often tell us how much easier it is to work through claims when their agent truly understands farming life. (Let’s face it: describing the loss of your favorite tractor is easier when your agent actually knows what a PTO shaft is!)
One of our long-time customers put it best after a damaging windstorm: “Having the right farm insurance in place gave us peace of mind. We could focus on getting our operation running again, knowing we were covered.”
At Farm & Country Insurance, we understand the pressures and challenges farming families face. That’s why we’ve dedicated our careers to helping protect your way of life. Our friendly team serves farms all across New York—including Auburn, Aurelius, Brutus, Cato, Fleming, Genoa, Moravia, Owasco, Scipio, Sennett, and beyond.
So, don’t leave your farm’s future to chance. Take a proactive step toward ensuring your family’s safety and your business’s stability. Contact Farm & Country Insurance today to schedule a comprehensive review of your current protection and discuss how we can tailor a policy that has your back—rain or shine.
Your farm is your family’s home and livelihood. Make sure it’s protected with customized farm homeowners insurance from Farm & Country Insurance—a partner who truly gets farming.
For more information about our services, visit the Farm & Country Insurance website or reach out to our experienced team today. We’re ready to help you protect everything you’ve grown.