
Why Farm Liability Protection Can Make or Break Your Operation
Farm liability insurance companies provide essential protection against lawsuits, injuries, and property damage claims that could devastate your agricultural business. The right farm liability insurance provider should offer comprehensive coverage with competitive limits and specialized agricultural expertise.
Modern farming operations face unique liability risks that standard business insurance simply can’t handle. From escaped livestock damaging neighbor property to visitors injured during agritourism activities, one uninsured incident can sink decades of hard work.
As Casey Love, owner of NY Farm Insurance Company in Honeoye Falls, I’ve spent years helping farmers steer the complex world of farm liability insurance companies to find coverage that truly protects their operations. My background serving the agricultural community has shown me how the right liability protection can mean the difference between a manageable setback and financial ruin.
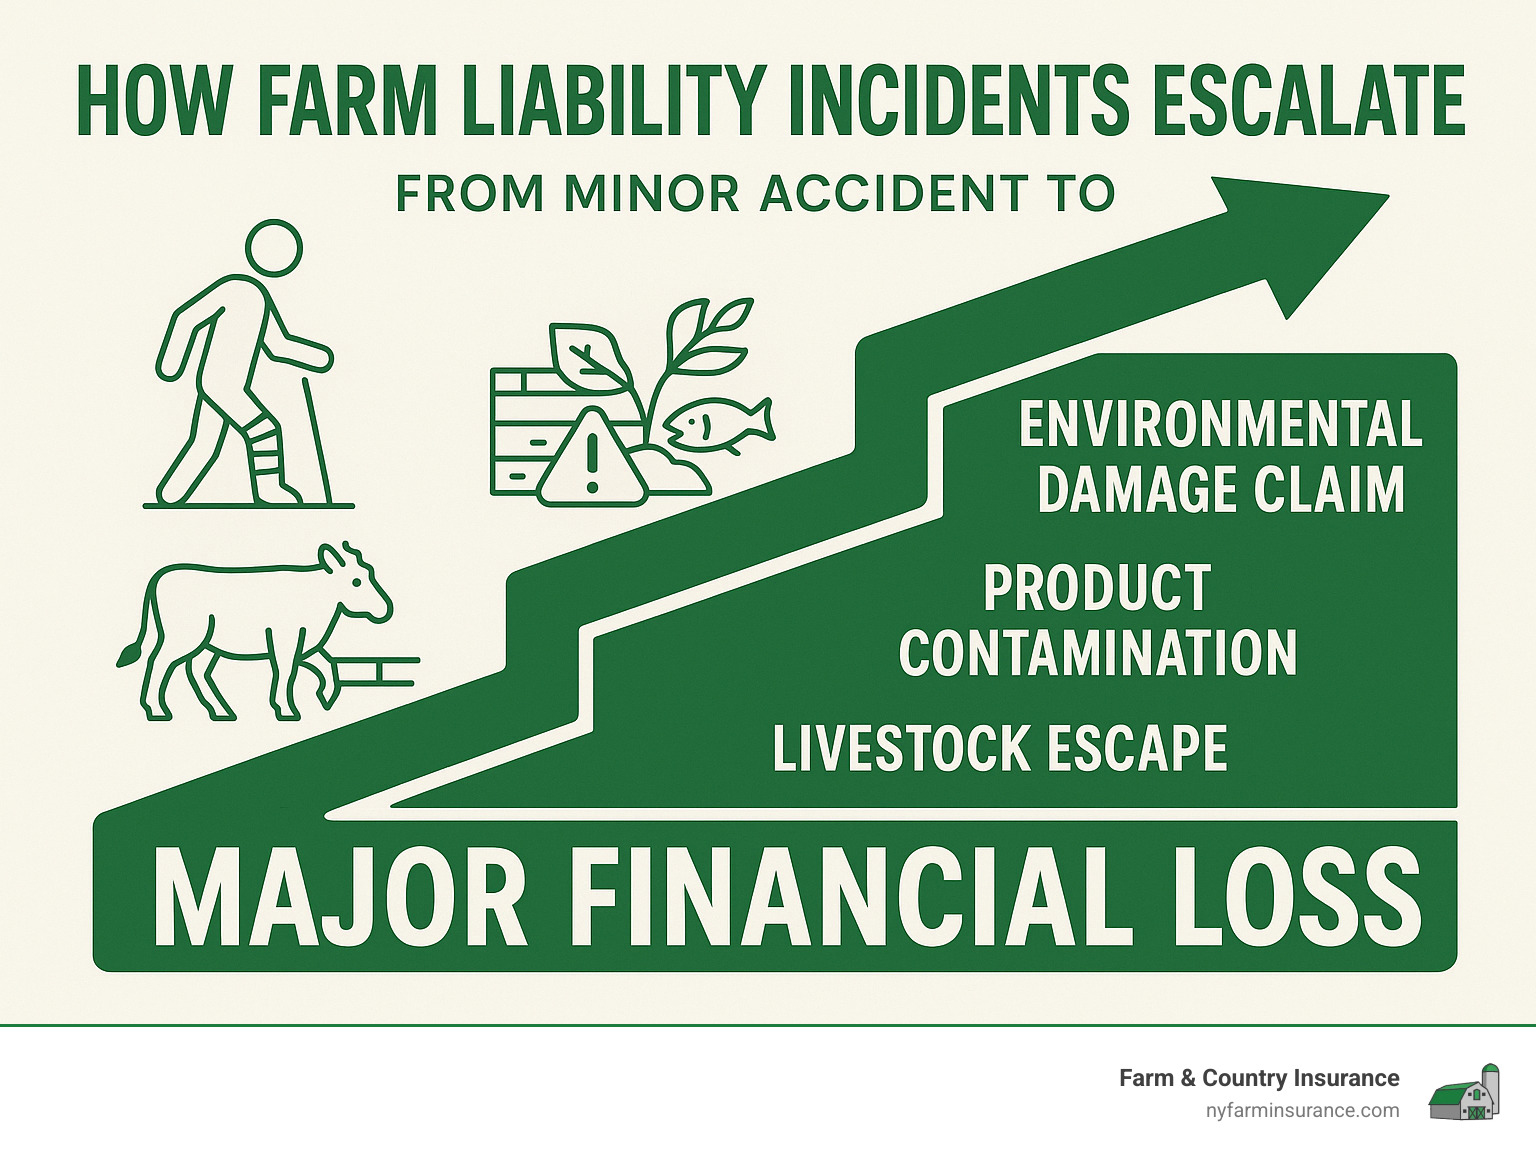
What Is Farm Liability Insurance & Why It Matters
Farm liability insurance is your financial safety net when things go wrong on your property. It covers the legal costs and damages when someone gets hurt or their property is damaged because of your farming operations. Think of it as your shield against lawsuits that could otherwise wipe out everything you’ve worked to build.
Unlike the basic coverage you might have on your home or regular business, farm liability insurance companies design their policies specifically for agriculture. They understand that farms have unique risks – from livestock escapes to equipment injuries to chemical drift incidents that suburban businesses never face.
General liability forms the backbone of your protection, covering bodily injury and property damage claims that happen during your day-to-day farm operations. But here’s what makes it really valuable: the legal defense coverage kicks in immediately when someone files a claim against you. Even if the lawsuit is completely bogus, you’ll still need a lawyer – and agricultural lawsuits can drag on for months.
Modern farms are doing more than just growing crops these days. Maybe you’ve added agritourism activities like corn mazes or farm tours. Perhaps you’re selling directly to consumers at farmers markets. Each new venture brings fresh liability exposures that need specialized coverage.

Pollution liability has become a big deal as environmental rules get stricter. A fuel spill from your tractor or fertilizer runoff can trigger expensive cleanup requirements – costs that can easily reach six figures.
More info about Farm Liability Insurance
Key Risks Farms Face Daily
Livestock escape incidents keep farm insurance adjusters busy. Cattle don’t respect property lines, and when they wander onto roads or into neighbors’ yards, the damage can be substantial. I’ve seen claims where escaped horses caused multi-car accidents, and the liability costs were staggering.
Equipment injury risks are everywhere on modern farms. Your combine harvester or hay baler can seriously hurt someone, even when you’re following all safety protocols. Visitors touring your operation might get too close to moving parts, or equipment might malfunction when the school bus full of kids is nearby.
Chemical drift has become a hot-button issue as suburbs creep closer to farmland. When your pesticide application drifts onto the neighbor’s organic garden or their prize roses, you could be looking at significant damages. These claims get especially expensive when organic certifications are at stake.
Typical Incidents Covered
Visitor injury claims happen more often than you’d think. That customer who slips on wet concrete at your farm stand, the delivery driver who trips over uneven pavement, or the agritourism guest who gets kicked by a “friendly” goat – they can all result in expensive medical bills and lawsuits.
Product recall situations can devastate direct-sales operations. If your farm-fresh eggs or homemade jam causes food poisoning, you’re not just dealing with sick customers. You’re facing potential recalls, medical expenses, lost income, and liability claims that can reach hundreds of thousands of dollars.
Environmental cleanup costs will shock you if you’re not prepared. A diesel spill from your fuel tank, manure runoff into a waterway, or chemical contamination can trigger cleanup requirements that cost more than most farmers make in several years. The right coverage helps manage these massive expenses and keeps your farm viable.
How to Choose the Right Farm Liability Insurance Partner
Finding the right farm liability insurance companies isn’t just about getting the cheapest quote – it’s about finding a partner who truly understands your operation and will be there when disaster strikes. After nearly four decades helping New York farmers protect their livelihoods, I’ve learned that the lowest premium often comes with the highest long-term costs.
The insurance marketplace offers everything from massive national carriers to small regional specialists. Each has its place, but the key is matching the right provider to your specific needs. A 2,000-acre grain operation has very different requirements than a 50-acre pick-your-own berry farm with weekend visitors.
What separates good farm liability insurance companies from great ones often comes down to three critical factors: financial strength to pay claims when they happen, coverage flexibility to adapt as your operation grows, and broker support that goes beyond just selling you a policy. Premium pricing matters too, but it should never be your only consideration.
Assessing Financial Strength of Farm Liability Insurance Providers
When your barn burns down or someone gets hurt on your property, you need to know your insurance company can actually pay the claim. That’s where A.M. Best ratings become your best friend. These independent ratings measure an insurer’s ability to meet their financial obligations to policyholders.
Look for carriers with A.M. Best ratings of A- or better. This indicates superior financial security and strong claim-paying ability. Companies that have maintained high ratings through multiple economic downturns demonstrate the financial stability you need for long-term protection.
Longevity in agricultural markets tells another important story. Insurance companies that have stuck with farming through good times and bad understand the unique challenges agriculture faces. They’re less likely to abandon the market when claims spike or when urban development makes farming less profitable in certain areas.
Comparing Policy Options for Farm Liability Insurance
The devil is always in the details when it comes to farm liability coverage. Occurrence limits determine how much protection you have for each incident, while aggregate limits cap your total annual coverage. Most farming operations need at least $1 million per occurrence, but larger or higher-risk operations may require significantly more.
Umbrella policies provide an extra layer of protection above your primary liability limits. Think of them as insurance for your insurance – they kick in when a major claim exceeds your base coverage. For the relatively small additional premium, umbrella coverage can protect against truly catastrophic losses.
The real value often lies in the endorsements and optional coverages available. Standard farm liability policies have gaps that can leave you exposed. Pollution liability protects against environmental cleanup costs. Product recall coverage helps when your direct-sales products cause problems. Agritourism endorsements cover the unique risks of having visitors on your farm.
| Coverage Type | Core Policy | Optional Endorsement |
|---|---|---|
| General Liability | ✓ | |
| Product Liability | ✓ | |
| Pollution Liability | ✓ | |
| Agritourism | ✓ | |
| Cyber Liability | ✓ | |
| Professional Liability | ✓ |
Price vs. Value: Premium Calculations
Insurance companies use different factors to calculate your premium, and understanding these can help you find better rates. Acreage serves as a base rating factor for many carriers, but don’t assume bigger always means more expensive. A well-managed large operation might get better rates than a smaller farm with higher risk activities.
Gross receipts matter especially for operations with direct sales, processing, or agritourism activities. Higher revenue generally means higher premiums, but it also indicates the income you’re protecting. The key is making sure your coverage limits match your actual exposure.
Livestock type and numbers significantly impact your rates. Dairy operations face different risks than sheep farms, and insurance companies price accordingly. Claims history affects pricing too – maintaining a clean record through good risk management practices can earn you substantial discounts.
At Farm & Country Insurance, we help you understand how different rating factors affect your premium and identify opportunities for risk mitigation discounts. Sometimes simple changes in operations or safety procedures can result in meaningful premium savings while actually improving your protection.
Understanding Provider Types & Their Strengths
The farm liability insurance companies landscape includes diverse provider types, each offering unique advantages to agricultural operations. Understanding these differences helps you identify the best fit for your specific needs and preferences.
When I work with farmers across New York, I often explain that choosing an insurance provider is like picking a business partner. You want someone who truly understands your operation, stands behind you when trouble hits, and grows with your business over time.

Local & Regional Expertise
Regional carriers bring something special to the table that big national companies often can’t match – they actually know your backyard. These insurers understand that a dairy farm in the Finger Lakes faces different challenges than a grain operation in Western New York.
Local underwriting expertise means your insurance company gets why you’re worried about late spring freezes or what happens when Lake Ontario decides to dump three feet of snow on your operation. They’ve seen these weather patterns before and price their policies accordingly.
On-farm visits from local representatives make all the difference. Instead of filling out forms and hoping for the best, you get someone who walks your property, asks smart questions, and spots potential problems before they become expensive claims. It’s like having a knowledgeable neighbor who happens to sell insurance.
Weather expertise becomes crucial when you’re dealing with New York’s unpredictable climate. Regional carriers track local weather patterns, understand seasonal risks, and know which farms typically face the biggest challenges during specific times of year.
Community-Focused Models
Member-owned cooperatives operate on a simple principle – when the company does well, you do well too. These member-benefit programs often include dividend payments, reduced premiums, and voting rights on company decisions.
Community programs show which insurers truly care about agriculture’s future. Companies that sponsor local fairs, support FFA chapters, or fund agricultural education demonstrate their commitment goes beyond just collecting premiums.
Agricultural support initiatives make a real difference in farming communities. 4-H is a global movement that develops young people’s leadership and agricultural skills, and insurers supporting such programs show genuine commitment to agriculture’s future.
When an insurance company invests in your community’s agricultural programs, they’re betting on the long-term success of farming in your area. That’s the kind of partner you want protecting your operation.
Comprehensive Coverage & Service
High liability limits accommodate farms with significant public exposure or those operating agritourism enterprises. Some carriers offer limits well above standard levels for operations requiring improved protection against catastrophic claims.
Bundled products simplify your insurance life by packaging multiple coverages with one carrier. This approach often results in premium discounts and means you only have one phone number to call when problems arise.
Technology-driven risk services help modern farms stay ahead of potential problems. These services might include online safety training, mobile apps for reporting issues, or regular risk assessments that identify exposures before they turn into expensive claims.
The Farm & Country Insurance Advantage
At Farm & Country Insurance, we’ve been serving New York’s agricultural community since 1984, developing deep expertise in the unique risks facing dairy, grain, fruit, and vegetable operations throughout our service areas.
Our approach focuses on obtaining multiple quotes from top-rated carriers, ensuring you receive competitive pricing without sacrificing coverage quality. We understand that every farm operation is unique, requiring customized solutions rather than cookie-cutter policies.
Claim advocacy represents one of our most valuable services. When losses occur, we work directly with carriers on your behalf, helping ensure fair and prompt settlement of legitimate claims. This support proves invaluable during stressful situations when you need to focus on your operation, not insurance paperwork.
We know farming because we’ve been part of New York’s agricultural community for decades. When you work with us, you’re not just buying insurance – you’re gaining a partner who understands your challenges and stands ready to help when you need it most.
More info about Farm Insurance Brokers
Real-World Claims & Coverage Gaps Exposed
Real farm liability claims often involve scenarios that might seem almost comical if they weren’t so costly. Understanding these actual incidents helps illustrate why comprehensive coverage is essential for modern agricultural operations.
One of the most memorable claims involved cattle that escaped and fell into a residential swimming pool, causing significant structural damage. This incident demonstrates how livestock can create unexpected and expensive liability situations.
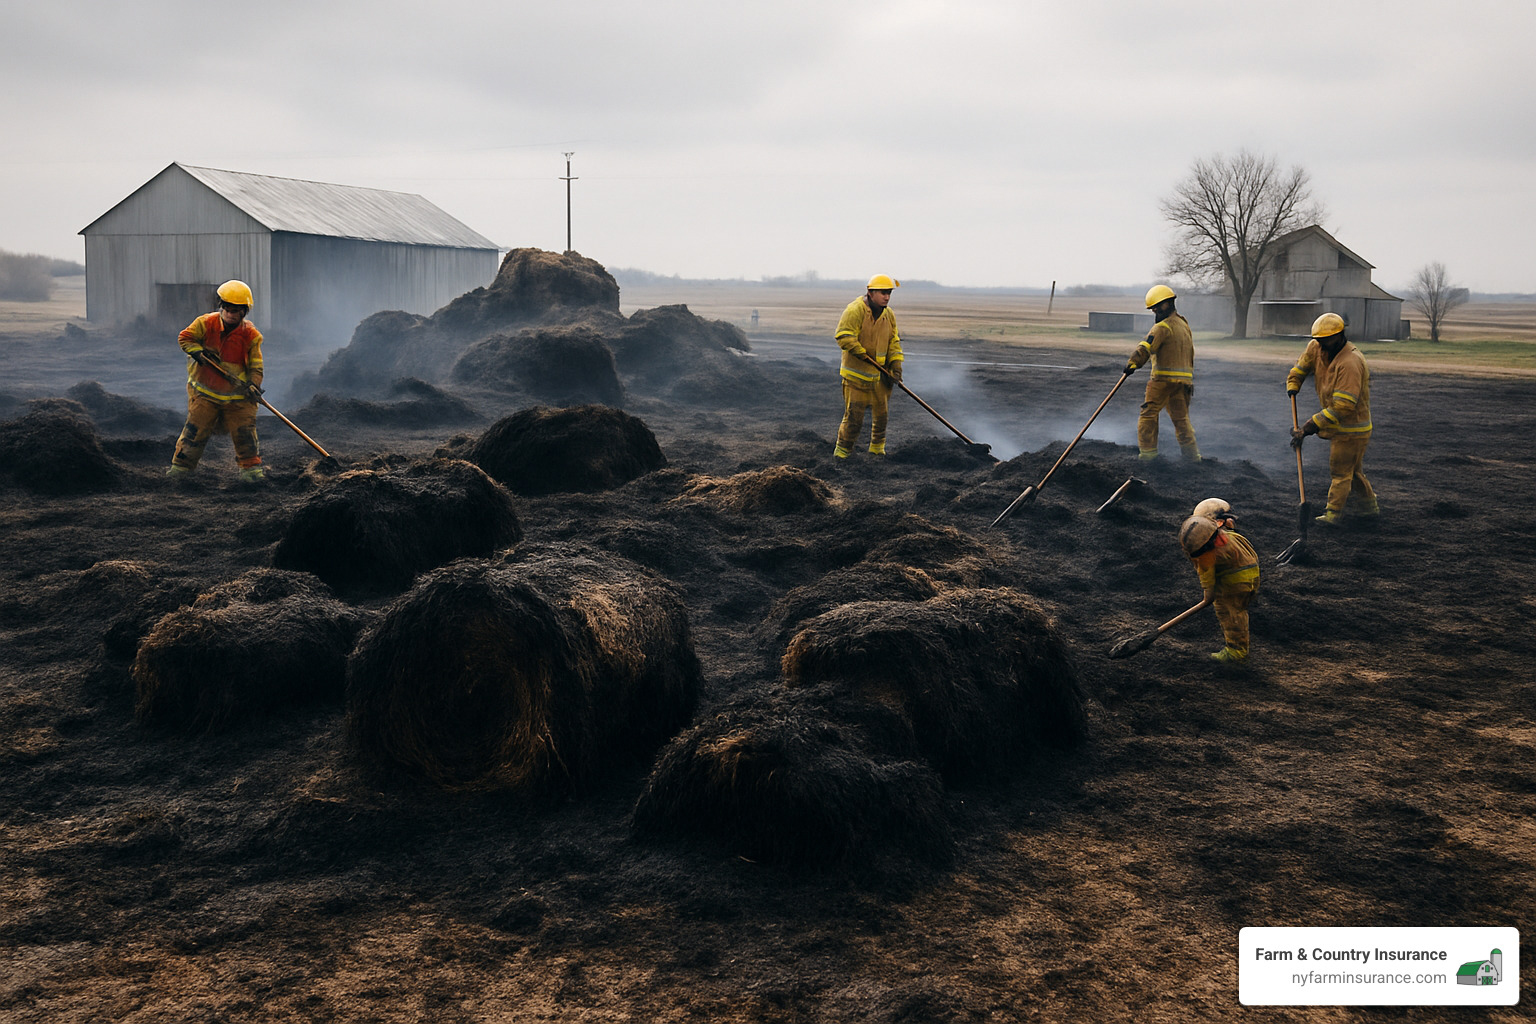
Hay stack fires from spontaneous combustion represent another surprising but real risk. These fires can spread to neighboring properties, creating substantial liability exposure beyond just the property damage on your own farm.
Pesticide overspray incidents have become increasingly common as suburban development encroaches on agricultural areas. These claims can be particularly expensive when they affect organic operations or cause health concerns among neighbors.
Cyber breaches now affect agricultural operations just like other businesses. Customer data from direct sales operations, financial records, and operational technology systems all create potential cyber liability exposures that traditional farm policies don’t address.
Visitor falls and injuries occur regularly on working farms. Whether it’s a customer at your farm market, a school group on a tour, or a delivery driver making a pickup, anyone on your property represents potential liability exposure.
Lessons Learned & Endorsements That Saved the Day
Pollution liability endorsements proved crucial in cases involving fuel spills from equipment or chemical releases during application. Without this coverage, cleanup costs and third-party claims could have been financially devastating.
Product recall coverage became essential when contamination issues affected direct-sales operations. The ability to manage recall costs and associated liability claims protected farm operations from potentially business-ending financial exposure.
Cyber risk endorsements helped farms manage data breach incidents and system failures that disrupted operations. As agriculture becomes increasingly technology-dependent, this coverage grows more important each year.
Agritourism liability endorsements protected farms offering educational tours, pick-your-own operations, and other public activities. These endorsements filled critical gaps in standard farm liability policies.
Tips to Lower Your Liability Risk
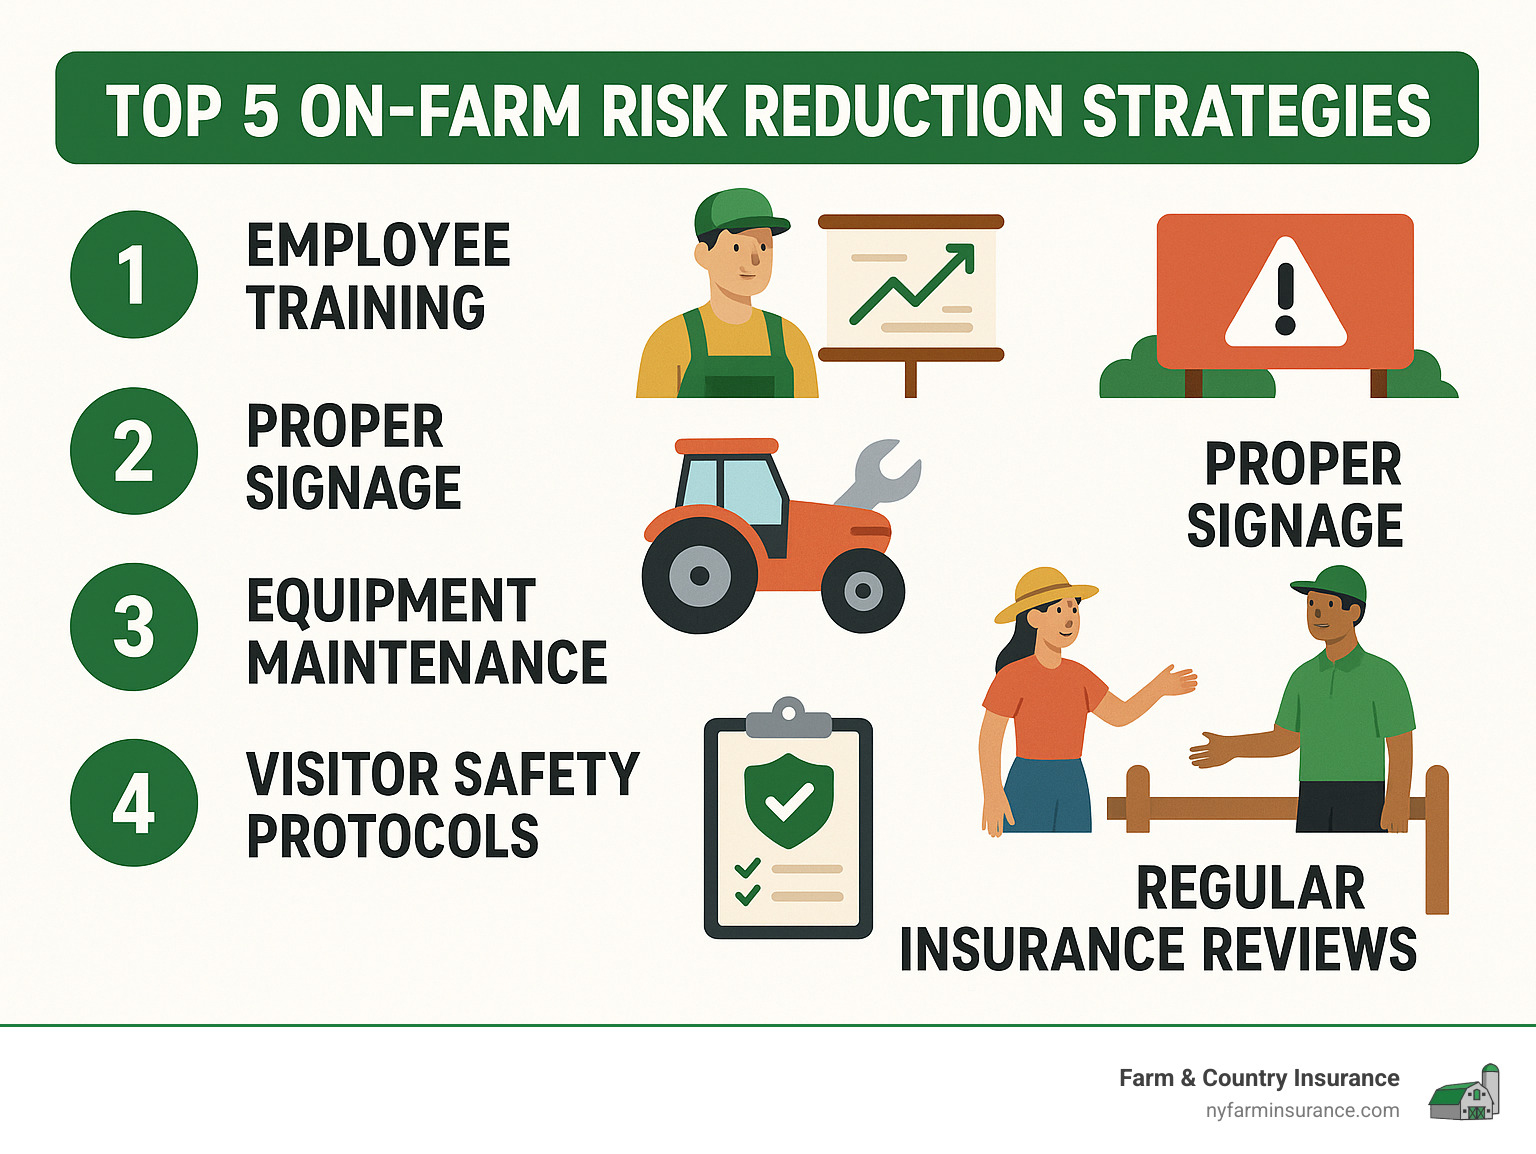
Employee training programs significantly reduce accident rates and liability claims. Regular safety meetings, proper equipment training, and clear protocols help create a culture of safety that benefits everyone.
Proper signage throughout your operation helps warn visitors of potential hazards and establishes reasonable safety expectations. Clear, visible warnings can provide important legal protection in liability situations.
Fence maintenance and livestock containment systems require regular inspection and prompt repair. Well-maintained barriers prevent animal escapes that could result in costly liability claims.
Inspection logs and maintenance records demonstrate proactive risk management efforts that can be valuable in defending against liability claims. Documentation shows you take safety seriously and maintain reasonable care standards.
Annual policy reviews ensure your coverage keeps pace with operational changes and evolving risks. Regular discussions with your insurance professional help identify new exposures and coverage needs.
Frequently Asked Questions about Farm Liability Insurance
When it comes to farm liability insurance companies and coverage questions, we hear the same concerns from farmers across New York time and time again. After nearly four decades serving the agricultural community, we’ve learned that most farmers have similar worries about their liability protection.
Let me address the most common questions we get at Farm & Country Insurance, so you can make informed decisions about protecting your operation.
How often should I review and update my coverage?
Annual policy reviews should be as routine as your yearly equipment maintenance. Your farming operation doesn’t stay the same from year to year, and neither should your insurance coverage.
Think about it this way – if you added fifty head of cattle last spring or started selling at the farmer’s market, your liability risks changed dramatically. Those changes need to be reflected in your coverage before something happens, not after.
Expansion triggers require immediate attention to your policy. Starting agritourism activities like corn mazes or farm tours creates entirely new liability exposures. Beginning direct sales operations means you’re now dealing with the public regularly, which brings different risks than wholesale operations.
Even seemingly small changes matter. Increasing your dairy herd from 100 to 200 cows doesn’t just double your milk production – it can significantly increase your liability exposure too. Most farm liability insurance companies adjust premiums based on these operational changes, so keeping them informed helps ensure you’re properly covered.
What isn’t covered under a standard liability policy?
This question always surprises new farmers, but understanding coverage exclusions can save you from nasty surprises later. Intentional acts top the list of exclusions – if you deliberately harm someone or damage their property, no insurance company will cover that. Thankfully, most farmers are decent folks who would never intentionally harm anyone.
Vehicle-related incidents catch many farmers off guard. If your farm truck causes an accident on the highway, that’s a commercial auto claim, not a farm liability claim. The same goes for tractors operating on public roads – they need separate coverage.
Professional services represent another common gap. If you provide custom pesticide application, veterinary services, or agricultural consulting, those activities require professional liability coverage. Your standard farm policy won’t cover mistakes or errors in professional judgment.
Workers’ compensation injuries also fall outside farm liability coverage. If your employee gets hurt on the job, that’s a separate type of claim entirely.
Are there government programs or subsidies that help?
Government assistance for liability insurance isn’t as common as crop insurance subsidies, but some programs can help reduce your overall risk and insurance costs.
USDA NRCS grants sometimes include funding for safety improvements that make your operation less risky. Better fencing, improved chemical storage facilities, or improved livestock handling systems can all qualify for cost-share programs while reducing your liability exposure.
State agricultural development programs occasionally offer risk management education and resources. While they don’t directly subsidize liability insurance, they can help you implement safety practices that lead to lower premiums.
The key is understanding that most liability insurance remains a private market purchase. Unlike crop insurance, which receives substantial federal subsidies, farm liability coverage relies on competitive pricing among private insurers.
That’s where working with an experienced agent becomes valuable. At Farm & Country Insurance, we help farmers steer available programs and find the most cost-effective coverage combinations for their specific situations.
Conclusion
Finding the right protection for your farm doesn’t have to feel overwhelming. Different insurers bring unique strengths to the table—whether it’s the rock-solid financial strength of a large national carrier, the generous coverage limits of a specialty insurer, or the farmer-focused approach of a mutual company.
What matters most is partnering with a provider who truly understands the daily realities of farming. Someone who knows that escaped cattle don’t check the calendar before they decide to take a swim in the neighbor’s pool. Someone who gets that a simple agritourism activity can turn into a complex liability situation faster than you can say “pumpkin patch.”
At Farm & Country Insurance, we’ve been walking alongside New York farmers since 1984. We’ve seen dairy operations in Auburn grow from small family farms to major producers. We’ve watched vegetable growers in Moravia adapt to changing markets and new risks. We’ve helped grain operations in Cato weather everything from market volatility to actual weather disasters.
Our approach is straightforward—we get to know your operation, understand your unique risks, and then shop multiple top-rated carriers to find you the best combination of coverage and value. When claims happen (and they do happen), we’re in your corner, working with the insurance company to make sure you get treated fairly.
The truth is, no amount of careful planning can prevent every accident. But the right liability coverage can mean the difference between a manageable setback and a business-ending catastrophe. Your farm represents years of hard work, smart decisions, and probably a few sleepless nights during planting or harvest season.
Don’t let one unexpected incident undo all that effort. Whether you’re milking cows at dawn, tending vegetables under the summer sun, or bringing in grain before the weather turns, you deserve peace of mind knowing you’re properly protected.
Ready to make sure your operation has the liability protection it needs? Let’s have a conversation about your specific situation and explore your options together. After nearly four decades of serving New York’s agricultural community, we’re here to help you protect what you’ve worked so hard to build.