
Why Standard Home Insurance Falls Short for Farm Properties
Farmers home insurance coverage is fundamentally different from a standard homeowners policy. Many farm owners mistakenly believe their regular home insurance protects their entire operation, but this assumption can lead to devastating financial gaps.
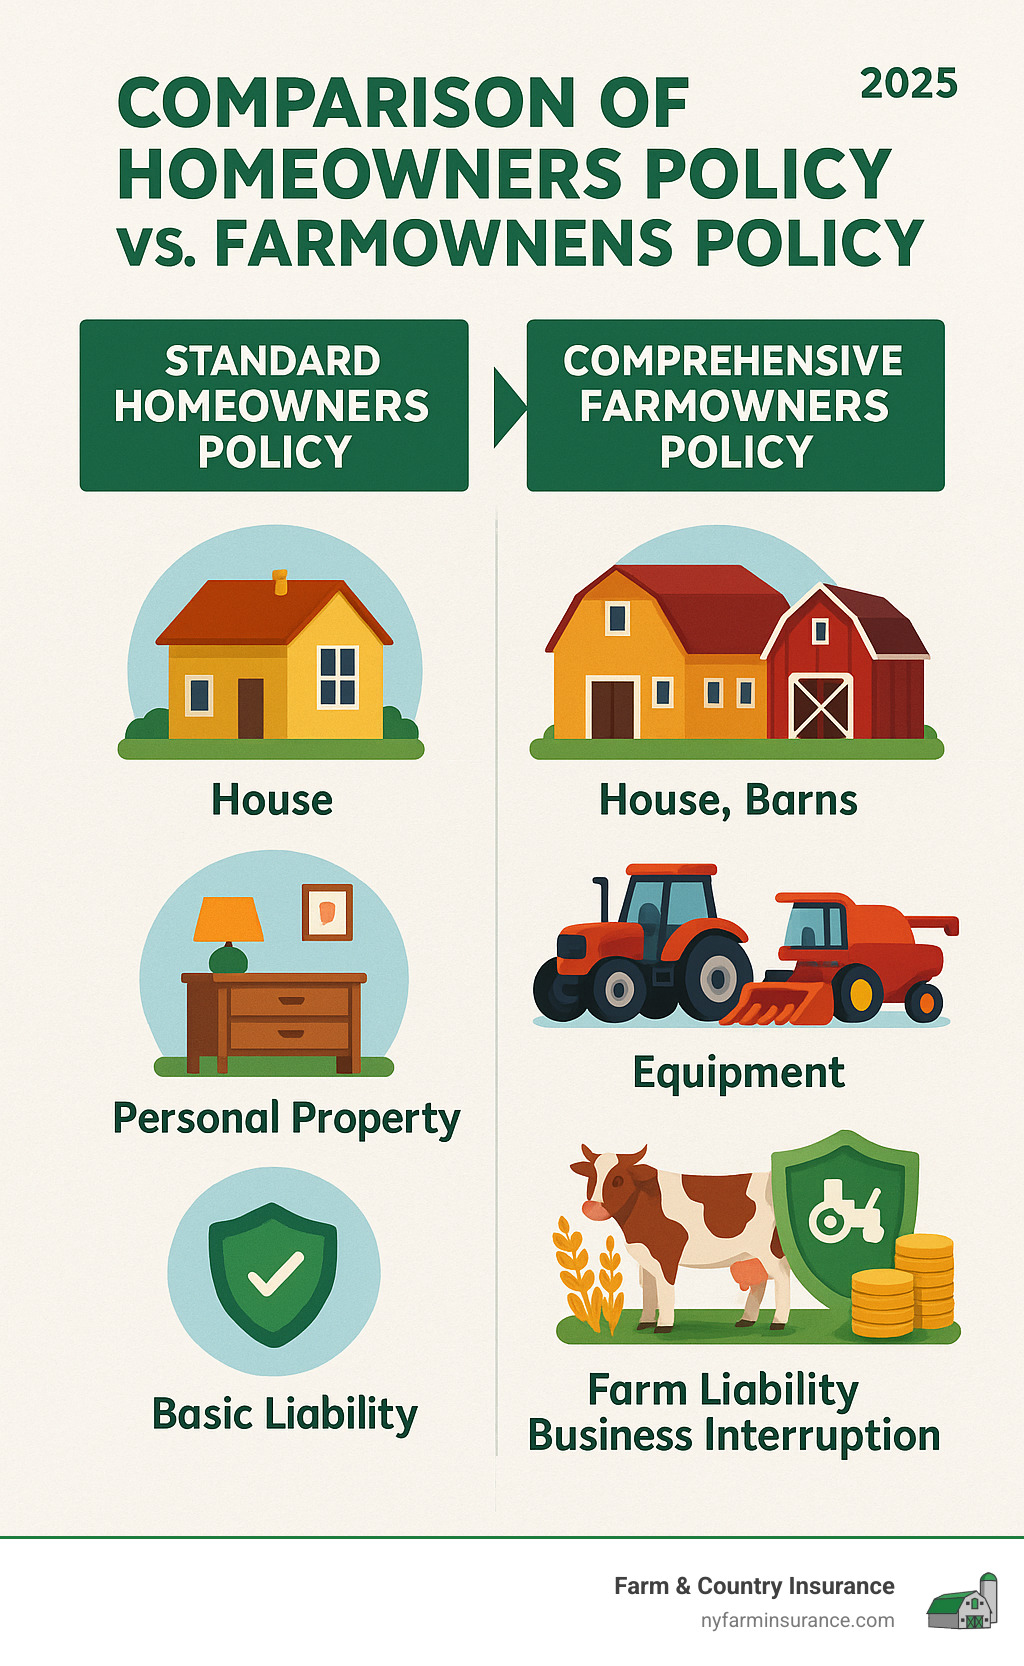
Here’s the core difference:
- Standard Homeowners Insurance: Covers your dwelling, personal belongings, and basic liability, but strictly excludes business-related activities.
- Farm Insurance: Protects your home PLUS your barns, equipment, livestock, crops, and farm-related liability.
Your farmhouse is the command center of a business. A standard policy might cover a kitchen fire, but it won’t help if lightning strikes your barn, a visitor is injured during a farm tour, or a $300,000 combine is stolen. These policies often cap business property coverage at a few thousand dollars, leaving hundreds of thousands in assets unprotected.
As one insurance expert notes, “Most home insurance policies do not provide enough coverage to protect your business from unforeseen incidents, like a loss of machinery or a farm accident.”
I’m Casey Love, owner of Farm & Country Insurance. For years, I’ve helped New York farmers secure specialized protection. The right coverage can mean the difference between recovering from a disaster and losing everything you’ve built.
Know your farmers home insurance coverage terms:
What a Standard Homeowners Policy Typically Covers
Most homeowners are familiar with the basic HO-3 policy, but understanding its limitations is crucial for anyone living on farm property. A standard policy revolves around a few core areas.

Dwelling coverage (Coverage A) protects your home’s physical structure. Personal property coverage (Coverage C) protects your belongings, like furniture and electronics. Personal liability coverage (Coverage E) provides financial protection if someone is hurt on your property or you accidentally damage someone else’s property.
Other coverages include protection for other structures (Coverage B) like detached sheds, loss of use (Coverage D) for temporary housing during repairs, and medical payments to others (Coverage F) for small medical bills.
While these policies work well for suburban homes, they fall short for agricultural properties. This is where the need for specialized farmers home insurance coverage becomes critical.
Typical Dwelling and Personal Property Protection
Understanding replacement cost versus actual cash value is vital. Replacement cost coverage pays to rebuild your home or replace items with new ones of similar quality, which we recommend at Farm & Country Insurance. Actual cash value coverage is cheaper but only pays the depreciated value, leaving you to cover the difference.
With rebuilding costs having risen significantly, replacement cost coverage is more valuable than ever. Standard policies cover typical household items but have special limits on high-value items like jewelry or cameras. Most importantly for farm families, they have severe limitations on business property, typically capping coverage at just $2,500 on-premises. Even a small tractor or feed supplies can easily exceed this limit.
For more guidance on protecting rural properties, check out our comprehensive guide on Home Insurance For Rural Properties.
Standard Liability and Medical Payments
Personal liability in a standard policy covers typical residential situations, like a guest tripping over a garden hose. Dog bite coverage is usually included, though some breeds may be excluded. The policy also covers non-business related incidents away from home.
Many homeowners add an umbrella policy for extra liability protection, typically starting at $1 million. However, the critical limitation is the phrase “non-business related.” If a guest injury happens near your barn or during a farm stand visit, a standard policy will likely deny the claim because it’s related to your farming operations.
This is where farmers home insurance coverage becomes essential, bridging the gap between residential and agricultural liability risks.
For more information about home insurance in our state, explore our guide on New York House Insurance.
The Critical Gaps: Why Standard Policies Don’t Work for Farms
Many farm families find too late that standard homeowners policies cannot provide the specialized protection they need. If you rely on regular home insurance for a farm, you’re likely exposed to significant risk, as most policies do not provide enough coverage for unforeseen business incidents.
Standard policies contain specific business activity exclusions that void coverage for anything related to your farm’s operation. Whether you have a few chickens or a 500-acre dairy, your farming activities are considered a commercial venture. This creates dangerous gaps by failing to account for high-value farm assets and the unique liability exposures of farm life.
Even hobby farms face this challenge. If you keep livestock, use a tractor, or sell produce, you’re operating a business in the eyes of an insurer. Any income-generating activity can void coverage for related losses under a standard policy. At Farm & Country Insurance, we’ve seen these gaps devastate families who thought they were protected.
For a comprehensive explanation of these limitations, read our detailed article on Why Standard Homeowners Insurance Isn’t Enough for Farms.
Uninsured Farm Structures and Equipment
A standard homeowners policy might cover a detached garage, but it specifically excludes structures used for farming. This means your barns, silos, greenhouses, fences, and corrals may have little to no coverage, despite being worth hundreds of thousands of dollars.
The equipment gap is even more staggering. Modern tractors, combines, and irrigation systems can be massive investments, yet standard policies offer no coverage for this commercial farm equipment. A basic homeowners policy might offer $10,000 for an outbuilding, while a single piece of equipment or a modest barn can easily exceed $100,000 in value. This isn’t just a coverage gap—it’s a financial cliff.
Farm & Country Insurance understands that your farmers home insurance coverage must reflect the true value of these essential business assets. We offer policies that recognize barns, silos, and specialized equipment for what they are.
To learn more about protecting these vital assets, visit our page on Farm Building Insurance Policy.
The Liability Black Hole: Farm Operations
The liability risks on a farm create a “liability black hole” where your greatest exposures receive zero protection from standard home insurance. The moment an incident is connected to your farming operations, business exclusions are invoked.
Consider these common farm-specific risks that standard policies won’t cover:
- Livestock escapes leading to traffic accidents or property damage.
- Visitor injuries in work areas, at a farm stand, or during agritourism activities.
- Product liability from selling farm goods like milk, eggs, or produce.
- Pesticide drift or pollution liability from fuel spills or chemical accidents.
These are real risks that farm families face daily. As one expert notes, “the deeper you dig, the bigger the differences become—and those differences can be critical for farmers.” Proper farmers home insurance coverage must address these unique agricultural risks with specialized liability protection.
To ensure you’re protected, understanding comprehensive farm and ranch coverage is essential. Read more about it on our page: Farm And Ranch Insurance Coverage.
A Deep Dive into Farm & Country Insurance Home Coverage for Farms
Your home is the command center of your farm. At Farm & Country Insurance, we’ve spent nearly four decades crafting farmers home insurance coverage that makes sense for agricultural life. Since 1984, we’ve worked with New York farmers, so we understand the language of your livelihood.
Our farmowners policies are a hybrid coverage, blending personal protection for your home with the commercial coverage essential for your farm. It recognizes that your home life and farming business are intertwined. Our policies are designed to protect:
- Your Dwelling: Your farmhouse receives comprehensive protection, just like a standard homeowners policy.
- Farm Personal Property: This includes everything from tractors and irrigation equipment to stored crops and specialized tools.
- Outbuildings and Farm Structures: Your barns, silos, sheds, and greenhouses are covered as the essential infrastructure they are.
- Livestock: We can protect your animals against perils like fire or lightning, with coverage scheduled per head or as a blanket.
- Farm Liability: This broad coverage protects you from claims arising from your farming operations, including visitor injuries or limited pollution liability.
We create policies that fit your farm like a good pair of work boots—reliable and ready for anything. For a comprehensive look at how we protect your entire farmstead, visit our page on Farmstead Insurance.

Essential Farm & Country Insurance home insurance coverage for your dwelling
Your farmhouse deserves protection that goes beyond the basics. We understand the unique challenges of rebuilding a rural home.
Guaranteed or Extended Replacement Cost is a popular option. If your home is destroyed, this coverage helps rebuild it even if construction costs have surged, providing a buffer of 20-50% above your dwelling limit. This is crucial in today’s world of fluctuating material and labor costs.
We ensure coverage for your primary farmhouse reflects the true cost to rebuild its unique structure, not just its market value. Your personal belongings within the home are also covered, often at replacement cost, so you can replace damaged items with new ones without a deduction for depreciation. We can also schedule high-value items like jewelry or heirlooms for adequate protection.
To explore how we can protect both your residential and agricultural assets, see our detailed guide on House And Farm Insurance.
Specialized endorsements every farmer should consider
Customizing your farmers home insurance coverage with endorsements addresses the unique risks of farming. Think of them as specialized attachments for your policy.
- Equipment Breakdown Coverage: Essential for modern farms, this covers repair or replacement costs from mechanical or electrical failure, like a power surge damaging milking equipment.
- Business Interruption Coverage: This financial safety net helps replace lost income and cover ongoing expenses if a covered peril disrupts your operation.
- Spoilage Coverage: Crucial for perishable products, this covers losses from power outages or refrigeration failure, with limits that reflect the true value of your goods.
- Chemical Drift Liability: Protects you if pesticides or herbicides from your property damage a neighbor’s land, crops, or livestock.
- Workers’ Compensation: Often required by law for employees, this covers medical expenses and lost wages for workers injured on the job.
These specialized coverages ensure your unique risks are properly addressed. For more insights, check out our guide on Best Hobby Farm Insurance.
What Factors Influence the Cost of Your Policy?
Understanding what drives the cost of your farmers home insurance coverage helps you make the best decisions for your operation. Several key variables work together to determine your premium.
Key pricing factors include:
- Farm Size and Value: The total value of your property, including your home, barns, and other structures, is a primary factor.
- Type of Farming Operation: Dairy farms, grain operations, and fruit orchards each have unique risk profiles that affect pricing.
- Location: Proximity to a fire department (your fire protection class rating) and regional weather patterns play a significant role.
- Claims History: A clean record of past losses often translates to better rates.
- Safety and Risk Management: Modern electrical systems, security features, and well-maintained facilities can lower costs.
- Coverage Limits and Deductibles: Higher limits increase premiums, while higher deductibles can lower them.
With construction and equipment costs rising, many farms are underinsured. It’s crucial to review your coverage regularly. For more on this, read our article: Is Your Farm Property Underinsured? The Answer Might Surprise You.
How to Manage Premiums Without Sacrificing Protection
Cutting corners on insurance is a dangerous gamble, but there are smart ways to manage your farmers home insurance coverage costs.
- Bundle Policies: Combine your farm homeowners policy with auto or umbrella liability to save 10% or more.
- Practice Strong Risk Management: Regular property maintenance and clear safety procedures show insurers you are a responsible risk.
- Choose Higher Deductibles: Raising your deductible from $1,000 to $2,500 can significantly reduce your premium. Just be sure you can comfortably cover the higher out-of-pocket cost.
- Invest in Safety: Installing fire alarms, security systems, or modern electrical wiring can qualify you for discounts.
- Maintain a Claim-Free Record: Many insurers reward claim-free periods with discounts.
The goal is finding the best value, not just the cheapest price. While our guide on Cheap Homeowners Insurance offers general tips, farm operations require specialized protection for your livelihood.
Frequently Asked Questions about Farm Home Insurance
Farm insurance can feel complicated. Here are answers to the questions we hear most often from New York farmers about their farmers home insurance coverage needs.
Is a farmowners policy required by law in New York?
No, New York state law does not mandate a farmowners policy. However, your mortgage lender will almost certainly require comprehensive coverage to protect their financial stake in your property. Even if you own your farm outright, a farmowners policy is essential business protection. Without it, a single fire, theft, or lawsuit could wipe out your livelihood and assets.
What’s the difference between ‘replacement cost’ and ‘actual cash value’ for my farm equipment?
This distinction is critical for your financial recovery after a loss.
Replacement Cost Coverage: Pays the full amount to replace your damaged equipment with a new, equivalent model. If your 10-year-old combine is destroyed, this coverage provides the funds to buy a brand new one, even if the price has increased.
Actual Cash Value (ACV) Coverage: Pays the depreciated value of your equipment. For that same 10-year-old combine, you would only receive what it was worth at the time of the loss, leaving you to cover the significant gap to buy a new replacement.
For high-value machinery, we always recommend replacement cost coverage to ensure you can get back to work quickly without a major financial setback.
Can I get coverage if I only have a small hobby farm?
Absolutely. This is a critical point for many rural property owners. A hobby farm is any property with agricultural activities, even if it’s not your primary income source. Raising chickens, keeping horses, or selling vegetables at a market are all considered business activities by insurers.
Your standard homeowners policy will not cover these risks. You need specific endorsements for your equipment, liability related to your animals or farm stand, and any agricultural structures. It is vital to disclose all activities to your insurer. Don’t assume small-scale means low-risk; a single incident can lead to a denied claim if the activity wasn’t disclosed.
To learn more about protecting your smaller-scale operation, check out our comprehensive guide on Homeowners Insurance For Hobby Farms.
Conclusion: Harvesting Peace of Mind with the Right Coverage
After reviewing farmers home insurance coverage, one truth is clear: standard homeowners insurance is not farm insurance. One is for suburban life; the other is built to protect your livelihood.
Your farm is where you live and work. Standard policies will leave your barn, equipment, livestock, and farm liability exposures unprotected. We’ve seen farmers learn this lesson the hard way when a fire, theft, or lawsuit wasn’t covered.
At Farm & Country Insurance, we’ve helped New York farmers sleep soundly since 1984. We understand agriculture and know that your combine is worth more than some houses. Our specialized farm coverage is comprehensive, protecting your farmhouse, barns, equipment, livestock, and the unique liability risks of farming.
We build relationships, not just policies. We take the time to understand your operation, whether it’s a large dairy or a small vegetable farm. Don’t let your family’s home and livelihood be an afterthought. Contact Farm & Country Insurance for a review that ensures your coverage is as strong as your commitment to the land.
Get a comprehensive review of your farm homeowners insurance today