
Aligned with Your Acreage: Finding the Best Hobby Farm Insurance Broker
Why Finding the Right Hobby Farm Insurance Broker is Critical for Your Success
A hobby farm insurance broker connects small-scale farm operators with coverage that bridges the gap between standard homeowners policies and full commercial farm insurance. Running a small farm in New York—whether raising chickens, growing vegetables, or keeping horses—creates unique risks that standard homeowners insurance simply won’t cover.
As one insurance expert notes, “A standard residential policy just won’t cut it for people living in rural areas with large properties or hobby farms.”
Hobby farms are generally defined as properties with limited acreage and income, operated for personal satisfaction rather than profit. Yet even these smaller operations face significant liability from visitor injuries, livestock damage, and equipment accidents. The challenge is finding coverage that’s neither too limited (homeowners) nor too expensive (commercial). This is where a specialized broker becomes invaluable.
Working with an experienced hobby farm insurance broker provides:
- Access to specialized carriers that understand hobby farm risks.
- Customized coverage for your specific property, livestock, and activities.
- Expert risk assessment to identify coverage gaps.
- Claims advocacy when you need support most.
At Farm & Country Insurance, we’ve dedicated ourselves to helping farmers across New York State protect their operations with custom insurance solutions. With deep roots in the agricultural community, we understand the unique challenges and risks that small farm operators face in our state.
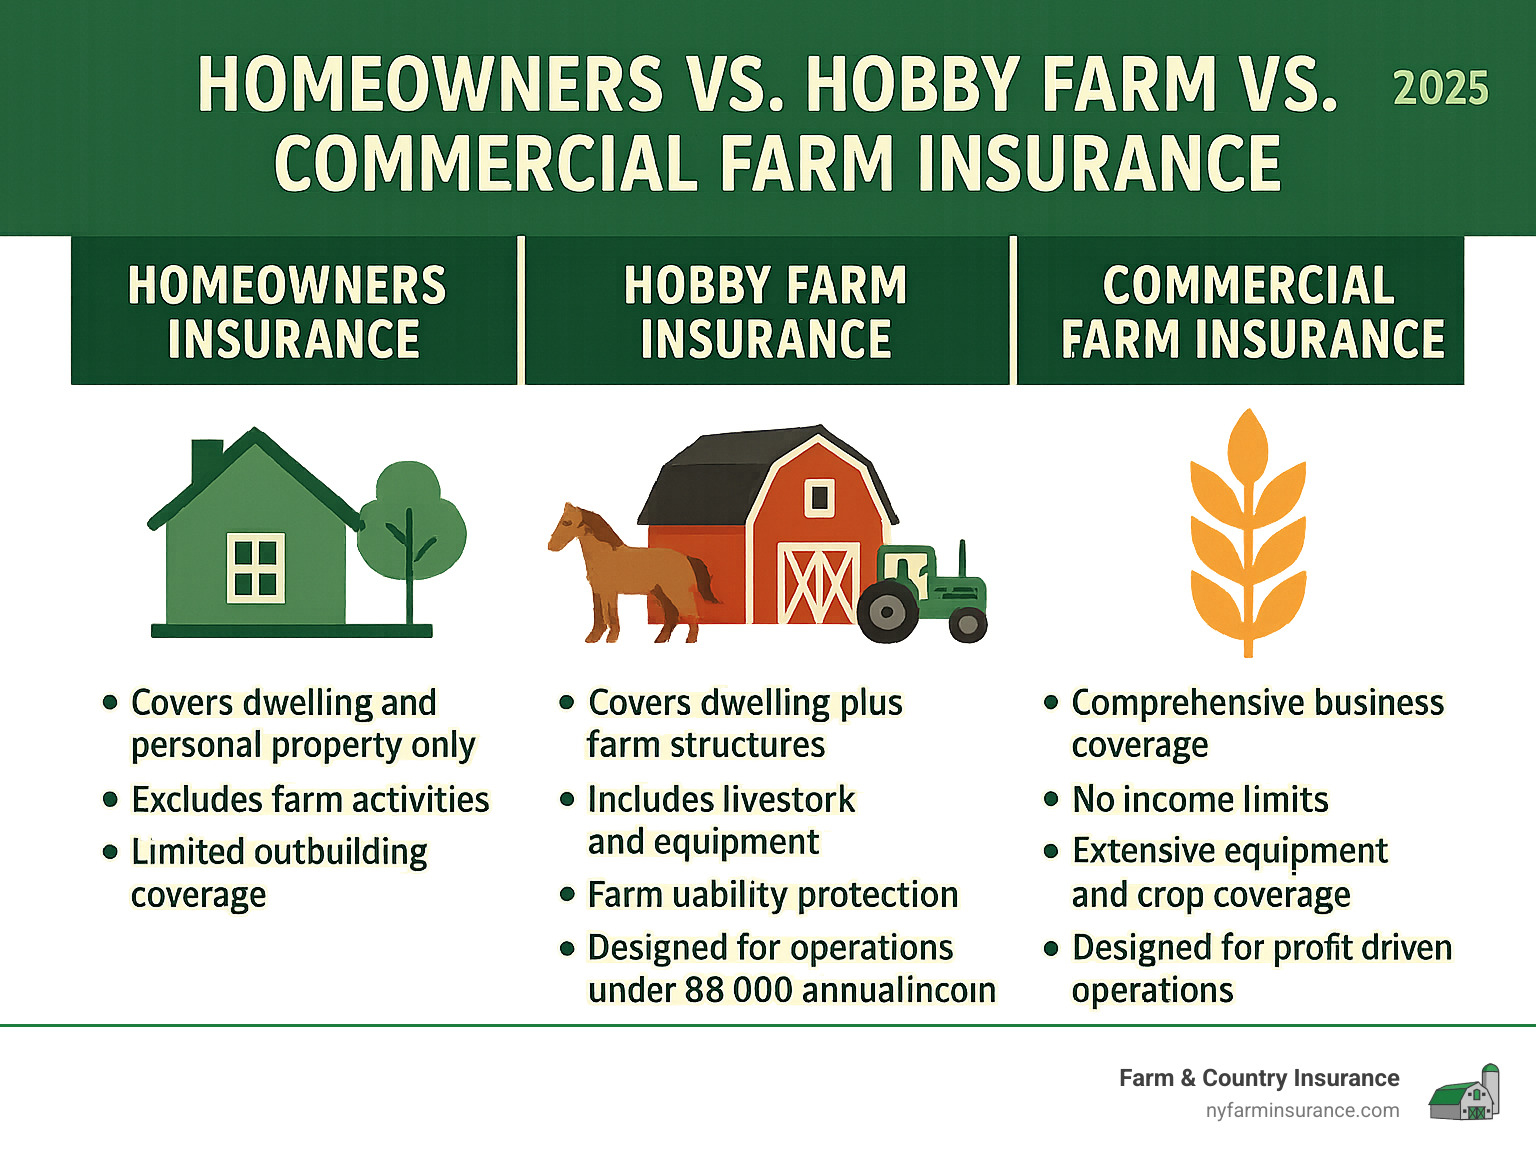
Hobby farm insurance broker terms at a glance:
Understanding the Unique Risks of Your New York Hobby Farm
Your hobby farm in upstate New York might be a weekend retreat or a childhood dream, but it faces risks most homeowners never consider. Hobby farms sit in a unique insurance gray area—you’re not a full commercial operation, but you’re doing much more than typical residential activities. This creates exposure gaps that can leave you financially vulnerable.
Consider these common risks on small New York farms:

- Visitor Liability: When friends visit, they enter an environment with inherent risks. A guest could slip on a wet barn floor, be startled by an animal, or encounter farm equipment, leading to costly injuries.
- Weather Risks: New York’s harsh winters can collapse barn roofs under heavy snow. Spring floods and summer storms can damage equipment, spoil feed, and threaten livestock.
- Animal-Related Incidents: Even gentle livestock can cause problems. A loose horse on a county road or chickens in a neighbor’s garden can create serious liability and property damage claims.
- Equipment Accidents: Tractors can overturn on hilly terrain, and power tools can malfunction, creating risks of injury and fire.
The consequences of being underinsured can be devastating. Without proper coverage, your personal assets—your savings, home, and financial future—are vulnerable in a lawsuit. This is why Why Hobby Farms Need Customized Insurance is so critical.
Why Standard Homeowners Insurance Falls Short
Many hobby farmers mistakenly assume their homeowners policy is enough. Unfortunately, these policies have critical gaps:
- Farming Exclusions: Most policies consider any agricultural pursuit a “business activity” and exclude related claims.
- Outbuilding Limits: A basic shed might be covered, but specialized structures like barns, coops, or stables are typically not.
- No Livestock Coverage: Animals are not considered “personal property.” If they are stolen, injured, or die from a covered peril, a homeowners policy offers no compensation.
- Inadequate Liability Limits: Standard liability limits are often insufficient for farm-related incidents.
- Risk of Cancellation: Undisclosed farming activities could lead your insurer to cancel your policy entirely, leaving you unprotected.
This is why Homeowners Insurance for Hobby Farms is not a viable solution.
Common Liabilities on a Small Farm
Running a small farm in New York means accepting certain liability exposures:
- Guest Injuries: Visitors face hazards like uneven terrain, curious animals, and unfamiliar equipment.
- Livestock Damage: Animals that escape can damage neighboring property or cause accidents, and the owner is typically responsible.
- Attractive Nuisances: Ponds, old equipment, and barns can tempt visitors, creating a legal obligation for you to secure these hazards.
- Product Liability: Selling eggs, produce, or other farm goods introduces liability. If someone gets sick from your product, you could face a lawsuit.
- Pollution Liability: Runoff from pastures or improper waste management can affect neighboring properties, creating environmental liability.
Understanding and managing these risks is key. Many agricultural resources offer valuable guidance on best practices for New York farmers. A qualified hobby farm insurance broker can then help you secure coverage for these specific exposures.
Hobby Farm vs. Commercial Farm Insurance: Finding the Right Fit
Choosing the right insurance for your New York farm can be confusing when your operation is between a backyard garden and a full-scale commercial enterprise. The good news is that hobby farm insurance exists precisely for this middle ground, bridging the gap between inadequate homeowners policies and expensive commercial farm coverage.
Think of it as getting the right tool for the job. Hobby farm insurance is designed for the specific terrain you’re actually covering.
| Feature | Standard Homeowners Insurance | Hobby Farm Insurance | Commercial Farm Insurance |
|---|---|---|---|
| Primary Purpose | Residential living | Personal enjoyment, supplemental income, self-sufficiency | Profit-driven business operation |
| Income Limits | Generally none, but excludes “business pursuits” | Typically up to $8,000 – $10,000 annually (varies by insurer) | No income limits, designed for primary income source |
| Acreage | Usually under 5-10 acres | Often up to 10-50 workable acres (varies) | Any size, often larger operations |
| Liability Coverage | Limited to personal risks, excludes farm-related incidents | Comprehensive farm liability for visitors, animals, equipment | Extensive business liability, product liability, employer liability |
| Equipment Coverage | Limited to household tools, lawn equipment | Covers farm machinery, tools, outbuildings, feed | Covers large-scale farm equipment, specialized machinery, inventory |
| Livestock Coverage | None | Covers specified types/numbers of livestock (mortality, theft) | Extensive livestock coverage, including large herds/flocks |
| Cost | Lowest (but inadequate for farm risks) | Moderate (custom to specific hobby farm risks) | Highest (due to extensive business coverage) |
This comparison shows that one size doesn’t fit all. Your hobby farm insurance broker can help determine where your operation falls. For more details, see our pages on Hobby Farm Insurance and Farm Insurance.
Defining a Hobby Farm for Insurance
Insurers use specific criteria to determine if your property qualifies for hobby farm coverage:
- Acreage: Typically fewer than 10 workable acres, though some policies go up to 50. The focus is on land you can actually farm.
- Income: Farm-related income is generally less than $8,000 to $10,000 annually.
- Labor: Operations use family labor only, with no outside employees.
- Livestock: Policies often cap the number of animals (e.g., six or fewer), though recreational horses may not count toward this limit.
- Purpose: The primary motivation is personal satisfaction or family food production, not profit.
When You Might Need Commercial Farm Insurance
As your farm grows, your insurance needs may evolve. It’s time to consider commercial farm insurance when:
- Income Exceeds Limits: Your annual farm income consistently surpasses the $8,000-$10,000 threshold.
- You Hire Employees: Hiring non-family workers requires workers’ compensation and broader employer liability protection.
- You Start Agritourism: Activities like corn mazes, pumpkin picking, or farm stays dramatically increase your liability exposure.
- Your Operation Scales Up: You significantly expand your livestock numbers or cultivate large acreage for cash crops.
- Your Purpose Shifts: Farming becomes your primary source of income and is run as a profit-driven business.
Transitioning to commercial coverage is a sign of success. At Farm & Country Insurance, we can guide you through options like Agribusiness Insurance to ensure your growing operation stays protected.
Key Coverages Included in a Hobby Farm Policy
Running a hobby farm in New York requires specialized protection that goes far beyond a typical homeowners policy. At Farm & Country Insurance, we understand your property is a unique blend of home and agricultural operation. A well-designed hobby farm policy protects all your assets, from your house and barn to your equipment and animals.
Key coverages include:
Dwelling and Personal Property: This forms the foundation, protecting your home and personal belongings just like a standard homeowners policy.
Farm Outbuildings: This is essential for protecting barns, stables, chicken coops, storage sheds, and fencing against perils like fire, wind, and hail.
Farm Machinery and Equipment: This covers your compact tractor, mower, tools, and ATVs from theft or damage, helping you get back up and running quickly.
Livestock Coverage: This provides protection for your animals against theft, accidental death, and injury—coverage that standard homeowners policies do not offer.
Farm Liability: This may be the most critical component, protecting you from claims related to visitor injuries, animal-caused damage, or equipment accidents.
For a deeper dive, check out our guide on Insurance for Small Farms.
Specialized and Optional Coverages to Consider
Every hobby farm is unique, and you might need additional coverages for complete protection. As your hobby farm insurance broker, we can help you identify these needs.
Product Liability Insurance: Essential if you sell any farm products, like eggs or produce. It protects you if someone gets sick or is injured by something you sold.
Business Interruption Coverage: Helps compensate for lost income and extra expenses if a covered event, like a fire, temporarily halts your operations.
Specialized Equine Coverage: Horse owners often add specific mortality, medical, or surgical coverage, as horses are valuable animals with unique risks.
Tack and Equipment Coverage: Protects high-value saddles, bridles, and other equestrian equipment that may exceed standard policy limits.
Pollution Liability: This optional coverage is worth considering, as it protects you from cleanup costs if runoff from your property damages a neighbor’s land or local water sources.
The key is working with a knowledgeable broker to build a policy that fits your operation. Learn more on our Best Hobby Farm Insurance page.
The Essential Role of a Hobby Farm Insurance Broker
Trying to figure out if your chickens are covered or if your old barn qualifies as a “farm structure” can be overwhelming. This is exactly why working with a dedicated hobby farm insurance broker transforms a confusing puzzle into a straightforward solution.
At Farm & Country Insurance, we know every New York farm tells a unique story. A broker does more than sell a policy; we act as your personal guide, translating complex terms and ensuring every aspect of your farm life is protected.
Our role is to provide ongoing support. We offer access to multiple carriers, which means we can shop for the best combination of protection and price. We provide policy customization as your farm evolves and claims assistance when you need it most. Having an advocate who speaks both “farmer” and “insurance company” is invaluable. Our deep knowledge of New York’s insurance landscape ensures your policy fits both your farm and your location.
Why Work with a Specialized Hobby Farm Insurance Broker?
General agents often lack the agricultural expertise to properly assess farm risks. A specialized broker offers:
- Industry Expertise: We understand the unique risks associated with different types of livestock, equipment, and farm activities.
- Custom Coverage: We don’t use a one-size-fits-all approach. We build a comprehensive solution that covers all your activities without dangerous gaps.
- Time and Money Savings: We do the heavy lifting of researching carriers and decoding policy language to find the best rates for your situation.
- Advocacy During Claims: When you face a loss, you have an experienced professional on your side to help steer the process and ensure a fair settlement.
For more insights, visit our Ag Insurance Agencies page. You can also learn more about working with a Farm Insurance Broker or find a Local Insurance Broker through our resources.
How to Prepare for Your Meeting with a Hobby Farm Insurance Broker
A little preparation makes your meeting more productive. Be ready to discuss the following:
- Property Details: Total acreage and a list of all buildings (house, barns, sheds), including their age and construction type.
- Machinery and Equipment: An inventory of your tractor, mowers, tools, and ATVs, with make, model, and estimated replacement value.
- Livestock Inventory: The type, number, and primary purpose of your animals.
- Farming Activities: A complete picture of what you do, from growing vegetables to any small-scale agritourism.
- Sales and Income: Be honest about all farm-related income, no matter how small.
- Prior Insurance: Information on your current policies and any past claims history.
Gathering this information helps us build the right policy for you. For more guidance, see our resource on Independent Insurance Agents Near Me.
Frequently Asked Questions about Hobby Farm Insurance
As a trusted hobby farm insurance broker at Farm & Country Insurance, we’ve guided countless New York farmers since 1984. Here are answers to the most common questions we hear.
What are the consequences of not having adequate hobby farm insurance?
The consequences can be financially devastating. Key risks include:
- Financial Loss from Uncovered Claims: If your barn burns down or a tractor is stolen, you would have to pay for replacement costs out of pocket.
- Personal Assets at Risk: If a visitor is injured or your livestock causes an accident, a lawsuit could threaten your savings, home, and financial future if your policy denies the claim due to farming exclusions.
- Difficulty Securing Future Insurance: An uncovered loss can make it harder and more expensive to get proper coverage later.
Why is specialized insurance necessary if my farm doesn’t make much money?
Liability is not tied to your profit margin. A visitor can be injured or your horse can cause an accident regardless of whether your farm is profitable. Standard homeowners policies contain specific exclusions for any farming activity, commercial or not. Insurance companies see “farming activity” and apply the exclusion. Your barn, equipment, and animals are valuable assets that represent a significant investment and deserve proper protection. The peace of mind from knowing your passion won’t become a financial burden is priceless.
What factors have the biggest impact on my insurance cost?
Several key factors determine your insurance costs. Understanding them helps you make informed decisions:
- Property and Location: The size of your property in New York, its structures, and its proximity to fire services all play a role.
- Animals: The type and number of animals you keep affect your liability risk. A few chickens pose less risk than horses or cattle.
- Value of Buildings and Equipment: The replacement cost of your barns, sheds, and machinery directly impacts your premium.
- Farming Activities: Selling products or inviting visitors to your property increases risk and, therefore, cost.
- Limits and Deductibles: Higher liability limits increase premiums, while higher deductibles can lower them.
For a detailed breakdown, check out our Small Farm Insurance Cost page. As your hobby farm insurance broker, we work with you to find the right balance between comprehensive coverage and affordability.
Your Partner in Protecting Your Passion
Your New York hobby farm is your personal sanctuary and the fulfillment of a dream. Whether you’re in Auburn, Genoa, or anywhere in between, your farm is an extension of who you are.
As we’ve discussed, standard homeowners insurance is not enough to cover the unique risks of livestock, farm equipment, and agricultural activities. This gap can leave you dangerously exposed. Specialized hobby farm insurance is designed to protect what you’ve worked so hard to build.
The peace of mind from proper coverage allows you to focus on what you love about your farm, rather than worrying about what could go wrong. This is where Farm & Country Insurance becomes your most trusted ally. As your dedicated hobby farm insurance broker, we’ve been protecting New York farmers since 1984. We understand the unique challenges of our state and what it takes to keep your farm safe.
The critical role of a specialized broker is to be your advocate and guide. We shop the market on your behalf to ensure you get comprehensive protection at a fair price.
Your hobby farm is your passion. Don’t let inadequate insurance put it at risk. Protecting your New York farm legacy starts with a conversation with someone who truly understands your world.
Get a quote for your Hobby Farm Insurance today and find the difference that working with a specialized hobby farm insurance broker makes. At Farm & Country Insurance, we don’t just protect farms—we protect dreams.