
Protect Your Passion: Understanding Hobby Farm Insurance
Hobby farm insurance is specialized coverage designed for small-scale farming operations that aren’t your primary source of income. Unlike standard homeowners insurance, it protects farm structures, equipment, livestock, and liability risks specific to small agricultural activities.
Quick Answer: What is Hobby Farm Insurance?
- Definition: Insurance specifically for small, non-commercial farms typically under 50 acres with annual revenue under $10,000
- Coverage: Farm buildings, equipment, livestock, crops, and liability
- Cost: Generally $50-$100 per month depending on assets and activities
- Why You Need It: Homeowners policies exclude farming activities, equipment, and related liability
- Eligibility: Small acreage, limited farm income, no employees
While your homeowners policy covers your residence, it explicitly excludes most farming activities, creating dangerous coverage gaps. If you have a barn, tractor, livestock, or sell produce at farmers markets, you need specialized protection that standard policies don’t provide.
Many hobby farmers mistakenly believe their small scale means they don’t need farm insurance. However, even a single incident—like a visitor injured during a farm tour or equipment damaged in a storm—can lead to significant financial loss.
I’m Casey Love, founder of Farm & Country Insurance, with over 15 years of experience helping New York farmers find affordable hobby farm insurance that protects their passion projects and small-scale operations.

Must-know hobby farm insurance terms:
– farm homeowners insurance
– farm bureau business liability insurance
– farm policy insurance
Hobby Farm vs. Commercial Farm: Know the Difference
Is your little slice of rural paradise a hobby farm or a commercial operation? The difference matters more than you might think – especially when it comes to insurance protection and tax implications.

A hobby farm is typically a small agricultural venture you maintain primarily for enjoyment rather than as your main income source. According to the U.S. Department of Agriculture, these small-scale farms have fueled a remarkable 12 percent population increase in rural counties since 1990. Today, hobby farms represent about half of all farms in the United States – a testament to Americans’ growing desire to reconnect with the land.
“Many New Yorkers are embracing hobby farming as a way to connect with nature, grow their own food, and enjoy a more sustainable lifestyle,” explains our risk management specialist at Farm & Country Insurance. “But they often don’t realize that their farming activities, even on a small scale, create unique insurance needs.”
| Characteristic | Hobby Farm | Commercial Farm |
|---|---|---|
| Primary Purpose | Enjoyment, lifestyle, supplemental income | Profit, primary income source |
| Acreage | Typically under 50 acres | Often larger than 50 acres |
| Annual Revenue | Less than $10,000 | More than $10,000 |
| Employees | None (family-operated) | May have employees |
| Tax Treatment | Limited deductions unless classified as business | Business deductions available |
| Insurance Needs | Hobby farm insurance or homeowners with endorsements | Commercial farm policy |
Key IRS & USDA Criteria
The IRS and USDA use specific benchmarks to distinguish hobby farms from commercial operations. These classifications affect both your insurance options and tax situation. To qualify as a hobby farm rather than a commercial venture, you’ll typically need to meet these criteria:
- Acreage less than 50 acres: Most hobby farms operate on relatively small parcels of land
- Annual receipts under $10,000: Your farm income should be modest and supplemental
- No employees: Hobby farms are typically family-run operations without hired help
These distinctions became even more significant after the 2018 Tax Cuts and Jobs Act, which requires hobby farms to be classified as businesses to remain eligible for certain tax deductions.
When a Hobby Farm Becomes a Business
That chicken coop you built for fresh eggs might be the first step toward something bigger. Here are signs your hobby farm might be evolving into a business:
Regular product sales at farmers markets or to local restaurants can transform your hobby into a commercial venture. Agritourism activities like paid farm tours or trendy “goat yoga” classes create additional liability concerns. If you’re offering Community Supported Agriculture (CSA) subscriptions where customers pay for regular shares of your harvest, you’ve definitely crossed into business territory. Even your local government might weigh in, as zoning regulations may require business classification once your activities reach certain thresholds.
“We’ve seen many clients start with a few chickens for eggs or a small vegetable garden, only to find themselves with a thriving small business a few years later,” notes our farm insurance specialist at Farm & Country Insurance. “When that happens, their insurance needs change significantly.”

Understanding where your farm falls on this spectrum is crucial for securing proper hobby farm insurance protection. The wrong classification could leave you vulnerable exactly when you need coverage most.
Why You Need Hobby Farm Insurance
Your backyard chickens, vegetable garden, and that old tractor you use on weekends might seem innocent enough. But when it comes to insurance protection, these hobby farm activities fall into a dangerous gap that your standard homeowners policy simply doesn’t cover.
Hobby farm insurance fills this critical protection gap by specifically covering the unique risks that come with small-scale farming activities – even when they’re just for fun.
“I can’t tell you how many times I’ve had clients shocked to learn their homeowners policy excludes that barn they just built or the tractor they invested in,” says one of our agents at Farm & Country Insurance. “Most people don’t find this coverage gap until after they’ve had a loss – exactly when it’s too late.”
Hobby Farm Insurance vs. Homeowners Endorsements
Your standard homeowners policy typically contains specific exclusions for:
- Farm structures like barns, coops, and greenhouses
- Equipment such as tractors, tillers, and irrigation systems
- Livestock, poultry, and other farm animals
- Liability for products you sell or give away
- Income loss from farming activities
Some insurance companies offer limited endorsements to homeowners policies that provide a small amount of farm coverage:
- ISO HO 24 72: This Incidental Farming Personal Liability endorsement provides limited protection for very small-scale activities
- ISO HO 24 73: The Farmers Personal Liability endorsement offers slightly broader coverage but still has significant limitations
“These endorsements are like putting a Band-Aid on a broken arm,” explains our farm specialist at Farm & Country Insurance. “They might work for someone with just a small garden, but if you have any real farm assets or activities, you need proper hobby farm insurance.”
The most critical difference is in the disclosure requirements. With farm insurance, you’ll properly document all your farming activities, ensuring nothing falls through the cracks when a claim occurs.
“I Only Sell Eggs on Weekends”—Still Need Coverage?
Many hobby farmers believe their small-scale or occasional sales don’t warrant specialized insurance. This dangerous misconception puts their personal assets at risk.
Consider this real scenario from one of our clients: They sold a few dozen eggs at their local farmers market each weekend. When a customer claimed food poisoning from these eggs and threatened legal action, they finded their homeowners policy specifically excluded product liability for farm products. Without proper hobby farm insurance, they would have been personally responsible for legal fees and potential damages.
“Even selling $20 worth of eggs weekly creates liability that standard policies won’t touch,” our risk management team explains. “Plus, many farmers markets now require proof of insurance before you can sell anything – they understand the risks even if many small farmers don’t.”
The reality is simple: any farming activity, no matter how small, creates unique risks. Whether you’re raising a few chickens, growing vegetables for a roadside stand, or keeping bees whose honey you share with neighbors, proper hobby farm insurance isn’t just a good idea – it’s essential protection for the rural lifestyle you love.
What Hobby Farm Insurance Covers & Excludes
When you’re running a hobby farm, understanding what your insurance actually protects (and what it doesn’t) makes all the difference. A good hobby farm insurance policy blends the best parts of homeowners coverage with specialized farm protections custom to your unique operation.
Core Coverages Inside a Policy
Your hobby farm policy’s backbone includes protection for your physical assets and liability concerns. The dwelling coverage protects your farmhouse just like a regular homeowners policy would, but then extends to include those crucial farm structures that standard policies ignore.
“The barns, coops, and equipment sheds that make your farm function aren’t covered under standard homeowners insurance,” explains our farm specialist at Farm & Country Insurance. “Neither is that tractor you use every weekend or the livestock you’ve invested in.”
A comprehensive policy typically protects your farm buildings, equipment like tractors and ATVs, and even your animals against perils like fire, lightning, and theft. Many policies also include limited coverage for harvested crops and products waiting to be sold.
The liability portion of your hobby farm insurance might be even more important. It protects you if someone gets injured on your property, covers claims related to products you sell, and pays for medical expenses and legal defense if you’re sued.
Farm personal property coverage extends to things like feed, seed, and supplies, while some policies offer loss of income protection if a covered event temporarily shuts down your operation. For equipment-heavy farms, breakdown coverage can be a lifesaver when mechanical failures occur beyond normal wear and tear.
For more specialized equipment concerns, our guide on Farm Equipment Insurance Coverage provides in-depth information about protecting these valuable assets.
Common Exclusions to Watch For
Just as important as knowing what’s covered is understanding what isn’t. Most hobby farm insurance policies won’t cover normal wear and tear, intentional damage, or certain natural disasters like floods and earthquakes (these typically require separate policies).
Farm-specific exclusions often catch hobby farmers by surprise. Custom farming (work you perform on someone else’s land), injuries to family members, and environmental contamination from chemicals or waste are typically excluded from standard policies.
“The vehicle coverage gap is probably the most dangerous,” warns our agent at Farm & Country Insurance. “Many hobby farmers don’t realize their personal pickup isn’t covered when they’re using it to haul livestock to the vet or transport produce to the farmers market. That usually requires commercial auto coverage.”
The Johnson family learned this lesson when their truck was damaged while delivering hay. Their personal auto policy denied the claim because they were using the vehicle for farm business. A proper hobby farm insurance policy would have addressed this gap.
Another common misconception involves assuming all farm activities are automatically covered. In reality, you need to specifically disclose each farming activity to your agent. That beekeeping hobby or the eggs you sell at the farmers market need to be on your policy, or you could find yourself without coverage when you need it most.
Premiums, Eligibility & Cost Drivers
Wondering if your small farm qualifies for hobby farm insurance and what it might cost? Let’s break it down in simple terms so you can understand what goes into pricing these specialized policies.
Who Qualifies for Hobby Farm Insurance?
Not every small farm operation fits the bill for hobby farm coverage. To qualify, your farm typically needs to check these boxes:
“Most of our clients have just a few acres with some chickens, maybe a vegetable garden, and possibly a couple of goats or sheep,” explains our specialist at Farm & Country Insurance. “That’s the sweet spot for hobby farm insurance.”
Your farm generally needs to have an annual income under $10,000 from farm activities and operate on less than 50 acres of land (though some insurers might stretch this to 200 acres for the right situation). The key is that farming isn’t your primary income source but rather something you do for personal enjoyment or to supplement your regular income.
The number of animals matters too – while there’s no universal limit, having hundreds of livestock would likely push you beyond hobby farm status and into commercial territory.
Want to learn more about coverage options for smaller operations? Check out our guide on Insurance for Small Farms.
How Insurers Calculate Your Rate
The cost of hobby farm insurance typically ranges from $50 to $100 monthly for most small farms. However, your specific rate depends on several factors that insurers carefully evaluate:
Your property details make a big difference – a 5-acre farm costs less to insure than a 40-acre one. The location matters too, with farms in flood-prone areas or regions with extreme weather facing higher premiums. Your farm buildings’ age, construction type, and condition all factor into the equation as well.
“When we write a policy, we look at everything from your tractor’s replacement value to whether you have a 100-year-old barn or a brand-new pole building,” says our Farm & Country Insurance agent. “Each element affects your premium differently.”
What you do on your farm significantly impacts your rates. Raising a few chickens for eggs carries different risks than growing specialty crops or raising larger livestock. If you sell products at farmers’ markets or invite visitors to your property for U-pick activities, your liability exposure increases, which affects your premium.
Your coverage choices naturally influence costs too. Opting for higher liability limits provides better protection but increases your premium. Choosing higher deductibles lowers your monthly cost but means more out-of-pocket expenses when claims happen. Additional endorsements for specialized coverage (like equipment breakdown or coverage for high-value livestock) add to your premium.
Your personal risk profile matters as well. Previous claims may increase your rates, while maintaining a good credit score (in states where this is permitted) can help lower them. Many insurers offer discounts for implementing safety measures like secure fencing, fire prevention systems, or security cameras.

The good news? Hobby farm insurance premiums typically cost significantly less than commercial farm policies, making proper coverage accessible for most small farm enthusiasts. At Farm & Country Insurance, we work with multiple carriers to find the right balance of coverage and affordability for your unique farming operation.
Reducing Risk & Lowering Your Hobby Farm Insurance Costs
Let’s face it – farming has its risks, but with some smart planning, you can make your hobby farm safer and save money on insurance at the same time. We’ve seen at Farm & Country Insurance how simple changes can make a big difference for our clients.
“Most hobby farmers don’t realize that the safety measures they implement not only protect their families and animals but can also lead to substantial insurance discounts,” explains our risk management specialist. “It’s a win-win.”
Practical On-Farm Risk Management Checklist
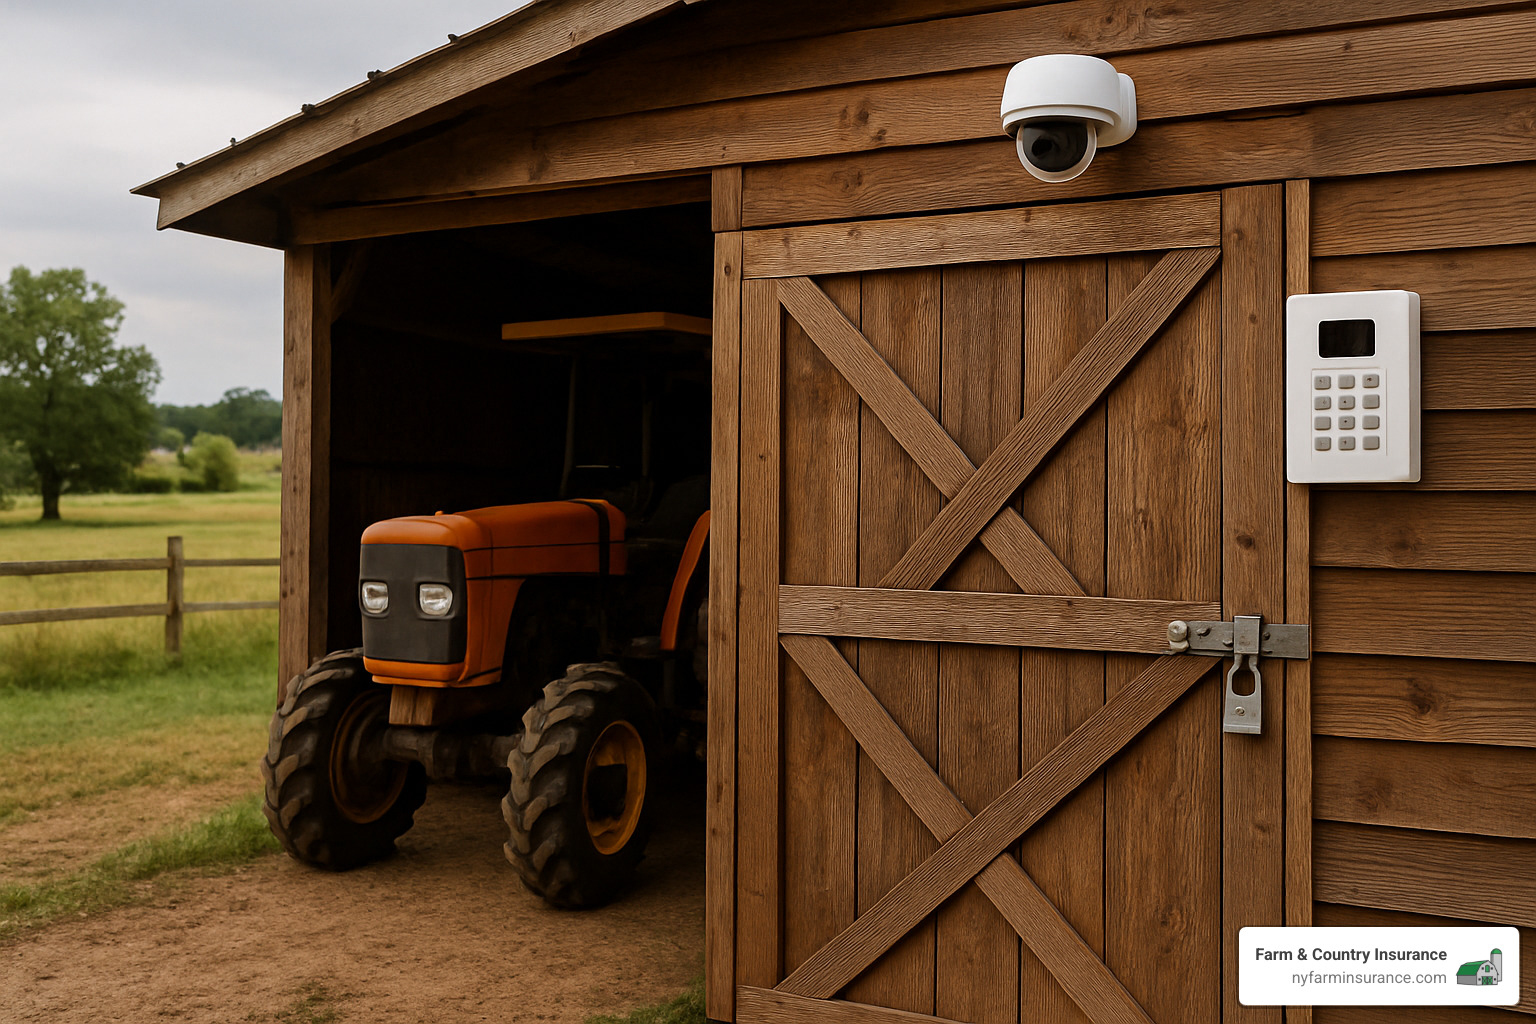
Walking your property with safety in mind can reveal simple improvements that make a big difference. One of our clients in Auburn installed secure fencing and proper lighting around their barn area, which not only qualified them for a safety discount but prevented a potential claim when their goats tried to make a midnight escape during a thunderstorm!
Your farm safety priorities should include secure fencing around livestock areas, fire extinguishers strategically placed in barns and outbuildings, and security measures like motion-sensor lighting. Don’t forget to maintain detailed records of your equipment, animals, and maintenance schedules – these prove invaluable during claims.
Create emergency plans for different scenarios like fires or severe weather, and make sure everyone who lives or works on your farm knows what to do. Clear signage warning visitors of potential hazards can also prevent accidents and potential liability claims.
Leveraging Liability & Equipment Schedules
Being strategic about how you structure your hobby farm insurance policy can lead to significant savings without sacrificing protection.
Consider scheduling high-value items individually on your policy. This means specifically listing valuable equipment like tractors or specialized tools with their accurate values. Not only does this ensure they’re properly covered, but it can sometimes reduce your overall premium by avoiding blanket coverage that might overinsure lesser items.
“I always recommend clients take a close look at their deductibles,” says our farm insurance specialist at Farm & Country Insurance. “Sometimes raising your property deductible while keeping a lower liability deductible gives you the best of both worlds – lower premiums where you can afford to take some risk, but strong protection where a claim could be costly.”
Bundling policies is another smart strategy. When you combine your hobby farm coverage with your home, auto, or other policies, you’ll typically save between 5-15% through multi-policy discounts. That adds up quickly!
Perhaps most importantly, schedule an annual policy review as your farm evolves. Maybe you’ve added beehives this year, or perhaps you’ve started selling at the local farmers market. These changes affect your coverage needs, and staying current ensures you’re neither paying too much nor leaving yourself vulnerable.
“One of the services we’re most proud of at Farm & Country Insurance is our ‘SuperCheck’ – an annual on-site policy review,” our agent explains. “We walk your property with you, noting changes and making sure your coverage grows along with your farm dreams.”
For more information about farm insurance questions, check out our Farm Insurance FAQs or explore our comprehensive risk management resources for farmers for additional guidance on protecting what matters most.
How to Secure the Right Hobby Farm Insurance in NY
Finding the perfect hobby farm insurance isn’t just about getting coverage—it’s about protecting your passion. After helping hundreds of New York hobby farmers over the years, we’ve developed a straightforward approach to make sure you get exactly what you need without overpaying.
Step 1: List Every Asset & Activity
Before you pick up the phone to call an agent, grab a notebook and take a walk around your property. You’d be surprised how many things we forget we own until we actually look!
Property Inventory
Start by documenting everything of value on your farm. This includes your farmhouse, that old barn you’ve been meaning to fix up, the chicken coop you built last spring, and even the greenhouse where you start your seedlings. Don’t forget to note the size, construction type, and approximate age of each structure.
Next, catalog your equipment—from the tractor you use every weekend to the collection of hand tools in your shed. Include make, model, year, and estimated value where possible.
For livestock, note each species, how many you have, and their approximate value. And don’t overlook your crops—what you’re growing, how much land you’re using, and what you expect to harvest.
“One of our clients in Auburn thought her small operation didn’t warrant much coverage until we helped her inventory everything,” shares our Farm & Country Insurance specialist. “She was shocked to realize she had over $50,000 in farm assets she’d built up over just three years!”
Don’t just list what you own—think about what you do. Do you sell eggs at the farmers market? Host school field trips? Make goat milk soap in your kitchen? These activities create different liability exposures that need to be covered.
Take photos of everything. They’ll not only help with getting accurate quotes but could prove invaluable if you ever need to file a claim.
Step 2: Talk to a Specialist & Get Multiple Quotes
When it comes to hobby farm insurance, working with someone who understands farming is non-negotiable. A general insurance agent might be great for your car insurance, but farm coverage is a different animal entirely (pun intended!).
At Farm & Country Insurance, we’ve been walking New York farmland since 1984. We know the difference between a hay wagon and a manure spreader—and why that matters for your insurance.
“I switched to Farm & Country after my previous agent suggested I just ‘add an endorsement’ to my homeowners policy for my small orchard,” explains Michael, a hobby farmer in Skaneateles. “When I mentioned I was selling cider at farmers markets, the Farm & Country agent immediately identified three coverage gaps that could have been disastrous.”
When comparing quotes, look beyond just the bottom-line price. Consider:
– Are the coverage limits adequate for your operation?
– What are the deductibles for different types of claims?
– Are there any exclusions that could leave you vulnerable?
– What’s the company’s reputation for handling farm claims?
For help finding qualified farm insurance specialists in your area, check out our guide on Farm Insurance Near Me.
Step 3: Bind, Review, and Update Annually
Once you’ve found the right policy, your relationship with your insurance is just beginning. Think of your policy as a living document that needs to grow alongside your farm.
After binding coverage (insurance-speak for “starting your policy”), carefully read through all your documents. Yes, insurance policies make for dry reading, but understanding what’s covered—and more importantly, what isn’t—can save you headaches later.
Set a reminder to touch base with your agent at least once a year, or whenever something significant changes on your farm. Did you add beehives this spring? Build a new tool shed? Start selling at a second farmers market? These changes could affect your coverage needs.
“Farming is never static,” notes our senior agent at Farm & Country Insurance. “The hobby farm you have today probably won’t be the same next year. Your insurance should evolve right alongside it.”
We had a client who started with just a vegetable garden and a few chickens. Within three years, they’d added a small orchard, beehives, and began hosting monthly farm-to-table dinners. Without regular updates to their policy, they would have had significant exposure to risk.
To learn more about the best insurance options for your specific type of hobby farm, visit our guide on Best Hobby Farm Insurance.
The goal isn’t just to have insurance—it’s to have the right insurance that lets you enjoy your hobby farm with complete peace of mind.
Frequently Asked Questions about Hobby Farm Insurance
What if I rent, not own, my farmland?
Renting your farmland doesn’t exempt you from needing proper insurance protection. While you won’t need coverage for the land itself, your hobby farm operation still faces significant risks that require protection.
“Many of our clients are surprised to learn they need specialized coverage even when they don’t own the land,” explains our specialist at Farm & Country Insurance. “Your lease agreement often requires specific insurance protections, and without them, you’re personally exposed to significant liability.”
When farming on rented land, you’ll typically need lease liability coverage to protect against accidentally damaging the property you’re renting. You’ll also need coverage for any equipment, livestock, or temporary structures you bring onto the property. Your landlord’s insurance protects their interests, not yours.
One of our clients in Seneca County learned this lesson when a visitor was injured during a farm tour on their rented property. Their hobby farm insurance policy covered the medical expenses and potential lawsuit, protecting their personal assets from what could have been a devastating financial blow.
Can I add hobby farm coverage to my homeowners policy?
While some insurance companies offer incidental farm endorsements to homeowners policies (like the HO 24 72 or HO 24 73 endorsements), these typically provide very limited protection that falls short for most hobby farmers.
“I’ve seen too many hobby farmers find the hard way that their homeowners policy endorsement wasn’t nearly enough,” shares our agent at Farm & Country Insurance. “These endorsements often cap coverage at just a few thousand dollars and exclude many common farm activities.”
The limitations of homeowners endorsements include strict coverage caps for farm property, minimal liability protection that may not cover product sales, and numerous exclusions for certain animals or activities. For most hobby farms with equipment, livestock, or regular product sales, a dedicated farm policy provides far more comprehensive protection.
Think of it this way: trying to cover your farm with a homeowners endorsement is like trying to protect an apple orchard with an umbrella – it might work for a small shower, but it’s going to leave you exposed when a real storm hits.
Does hobby farm insurance cover my pickup truck?
This question comes up in nearly every conversation we have with new hobby farm clients, and the answer is usually no. Hobby farm insurance typically doesn’t cover vehicles that are licensed for road use – including your pickup truck, flatbed truck, or livestock trailers.
For these vehicles, you’ll need either:
– A personal auto policy if the vehicle is primarily used for personal transportation with occasional farm use
– A commercial auto policy if the vehicle is primarily used for farm operations
“The key question isn’t what type of vehicle you have, but how you’re using it,” explains our Farm & Country Insurance specialist. “If you’re regularly hauling livestock to auction or delivering produce to farmers markets in your pickup, your personal auto policy might deny a claim because you’re using the vehicle for business purposes.”
We recently helped a client in Wayne County who was using their personal truck to transport their sheep to regional shows. After reviewing their activities, we recommended adding commercial auto coverage to ensure they wouldn’t face a coverage gap if an accident occurred during one of these trips.
Farm vehicle coverage can be complex, which is why we recommend discussing your specific situation with an agent who specializes in hobby farm insurance and understands the unique ways farmers use their vehicles.
Conclusion
There’s something special about waking up to the sound of roosters crowing and stepping outside to collect fresh eggs from your own chickens. Hobby farming connects us to the land in ways that nourish both body and soul. But this passion project needs proper protection—and that’s where hobby farm insurance comes in.
Throughout this guide, we’ve seen how standard homeowners policies leave dangerous gaps in coverage for farming activities, equipment, and liability. Even if you’re just selling eggs at the weekend farmers market or growing vegetables for your family, your hobby farm faces risks that require specialized protection.
At Farm & Country Insurance, we’ve spent nearly four decades helping New York’s hobby farmers protect their dreams. We’ve seen how the right coverage provides not just financial security but genuine peace of mind.
“One of our clients started with just a small vegetable garden and a few chickens,” shares our senior agent. “Today, she runs a thriving lavender farm with beehives and seasonal agritourism events. Her hobby farm insurance grew right alongside her operation, protecting each new venture and investment.”
Remember these essential points as you consider your coverage needs:
Your homeowners policy likely excludes most farming activities, creating significant protection gaps that could cost you thousands. Even small-scale operations face substantial risks from visitor injuries, property damage, equipment breakdowns, and weather events. The right policy should grow with your operation, adapting as you add livestock, equipment, or new activities.
Working with an agent who understands farming isn’t just helpful—it’s crucial. At Farm & Country Insurance, we speak your language. We know the difference between a rotary tiller and a post-hole digger, and we understand the unique risks of raising livestock versus growing crops.
Ready to protect your slice of rural paradise? We’d love to help craft coverage that’s as unique as your hobby farm. Our personalized approach ensures you get exactly the protection you need—nothing more, nothing less.
Visit our farm insurance hub for a personalized quote
Your hobby farm is more than just land and buildings—it’s your passion, your sanctuary, and perhaps your legacy. Let’s make sure it’s protected for years to come.