
Why Farm Families Need Specialized Protection for Their Homestead
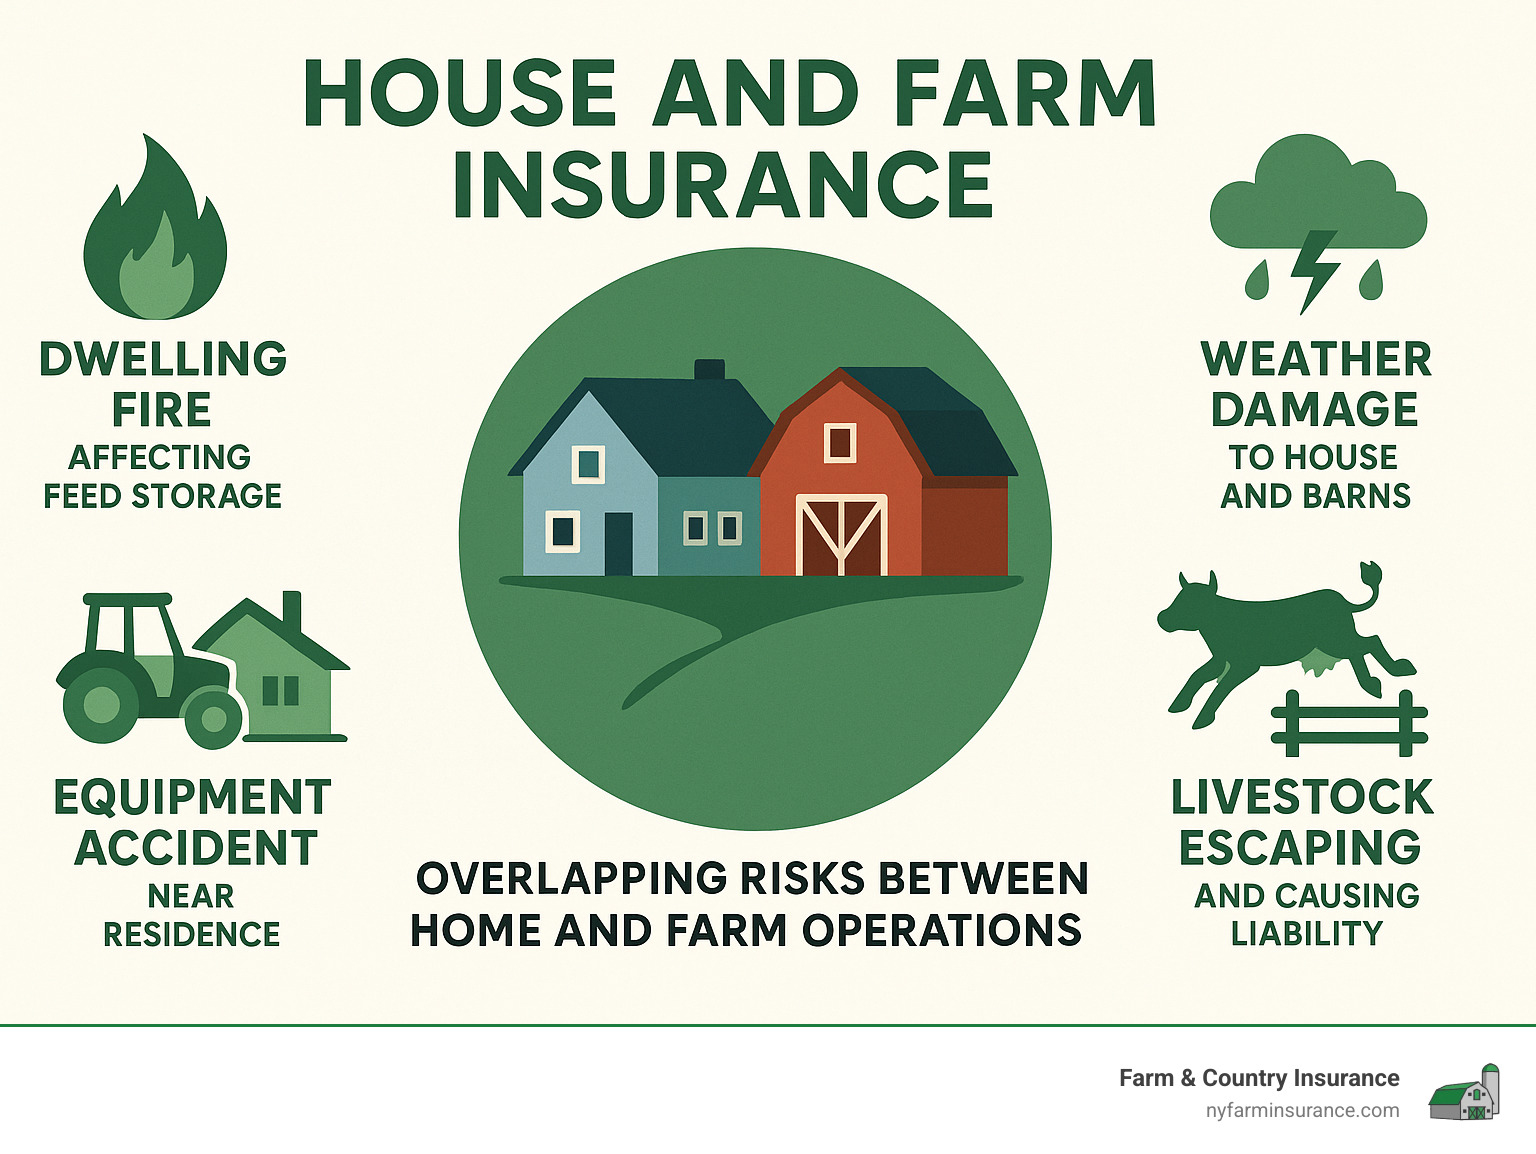
House and farm insurance protects both your family residence and agricultural operations under one comprehensive policy, covering everything from your dwelling and personal belongings to barns, equipment, livestock, and farm liability risks that standard homeowners insurance excludes.
Standard homeowners policies leave dangerous gaps for rural property owners. They typically exclude farm structures like barns and silos, expensive equipment like tractors and combines (which can cost $300,000+), livestock, harvested crops, and liability from farming operations.
Key coverage differences:
– Standard homeowners: House, personal property, basic liability
– House and farm insurance: All homeowners coverage PLUS barns, equipment, livestock, crops, farm liability, and agricultural endorsements
Whether you run a full-scale dairy operation or a small hobby farm with a few animals, mixing residential and agricultural activities on the same property creates unique risks that require specialized protection.
I’m Casey Love, owner of Farm & Country Insurance, and I’ve spent years helping New York farmers secure comprehensive house and farm insurance policies that protect both their homes and agricultural operations. My agency specializes exclusively in farm insurance, ensuring rural families get the custom coverage they need without dangerous gaps.
Find more about house and farm insurance:
– flood insurance New York
– home insurance for rural properties
– homeowners insurance for hobby farms
What Is House and Farm Insurance & Why It Matters
House and farm insurance is like having a best friend who truly understands your unique rural lifestyle. It’s a hybrid policy that wraps your home, your farming operation, and everything in between under one protective umbrella. Think of it as the Swiss Army knife of insurance – covering your dwelling, personal belongings, barns, tractors, livestock, and all those agricultural activities that make your property special.

At Farm & Country Insurance, we’ve been helping New York farm families since 1984, and we’ve learned that rural living creates a beautiful but complex web of risks. Your farmhouse isn’t just a home – it’s often the heart of a working agricultural operation. Your barn isn’t just storage – it might house expensive equipment worth more than most people’s homes.
Here’s why house and farm insurance matters so much: standard homeowners policies were designed for suburban families with manicured lawns, not for folks who might have a $200,000 combine parked next to their kitchen garden. When you’re running a dairy operation in Cayuga County or growing crops in Auburn, you face unique challenges that require specialized protection.
Most lenders understand this reality. They typically require comprehensive coverage that protects their investment in both your residential property and your agricultural assets. But even beyond lender requirements, the risks are real and potentially devastating.
How It Differs from Standard Homeowners Coverage
The gap between standard homeowners insurance and what farm families actually need is enormous – and potentially devastating. Standard homeowners policies contain specific exclusions for commercial activities, which includes most farming operations, even if you just keep a few chickens and sell eggs at the local farmers market.
Here’s what gets excluded from typical homeowners coverage: barns, silos, grain bins, and other agricultural structures that might represent hundreds of thousands of dollars in investment. Farm machinery and equipment like tractors, combines, and irrigation systems are also excluded. Your livestock, harvested crops, stored feed, and any liability from farming operations? Not covered.
Coverage Comparison:
| Coverage Type | Standard Homeowners | Farm Homeowners | Standalone Farm |
|---|---|---|---|
| Dwelling | ✓ | ✓ | Optional |
| Personal Property | ✓ | ✓ | Optional |
| Barns & Outbuildings | ✗ | ✓ | ✓ |
| Farm Equipment | ✗ | ✓ | ✓ |
| Livestock | ✗ | ✓ | ✓ |
| Crops & Feed | ✗ | ✓ | ✓ |
| Farm Liability | ✗ | ✓ | ✓ |
| Business Interruption | ✗ | Optional | ✓ |
We’ve seen the heartbreak that these gaps can cause. One dairy farmer in Moravia lost his entire herd in a barn fire, only to find his homeowners policy excluded livestock coverage entirely. Another vegetable grower in Fleming faced a lawsuit when a visitor slipped during a farm tour, but his standard homeowners policy offered no protection for farm-related activities.
Specialized Protection for Modern Homesteads
Today’s homesteads are wonderfully diverse, blending traditional farming with creative agribusiness ventures. We work with families running pick-your-own operations, farm-to-table restaurants, wedding venues, and educational tours. Some clients combine dairy farming with cheese-making, while others grow vegetables and run farm stands.
These modern agricultural activities create unique liability exposures that require specialized attention. House and farm insurance adapts to these realities with endorsements for agritourism liability when visitors attend events, environmental liability for pesticide application and manure management, product liability for direct-to-consumer sales, and even cyber liability for online farm stores and social media marketing.
The beauty of specialized house and farm insurance is that it grows with your operation. Whether you’re planning to expand your dairy herd, add agritourism activities, or start selling products directly to consumers, the right policy adapts to protect your evolving agricultural venture.
Essential Coverages to Look For in House and Farm Insurance
When you’re shopping for house and farm insurance, knowing which coverages are absolutely essential can save you from devastating financial losses down the road. At Farm & Country Insurance, we’ve helped countless farm families steer these decisions since 1984, and we’ve seen what happens when critical protections are missing.
The foundation of solid farm homeowners coverage starts with dwelling replacement cost protection that rebuilds your home to current standards, not yesterday’s prices. You’ll also need comprehensive personal property coverage, farm personal property protection for your equipment and supplies, livestock mortality coverage, and robust liability limits with umbrella options available.
Core Property Protections
Your home deserves replacement cost coverage, not actual cash value that leaves you scrambling to make up the difference between what you receive and what rebuilding actually costs. We always recommend automatic inflation guard provisions that bump up your coverage limits each year – construction costs have been climbing steadily, and you don’t want to find you’re underinsured after a total loss.
Debris removal coverage might sound boring, but it’s absolutely crucial for rural properties. When that ice storm knocked down trees across a client’s property in Sterling, the cleanup costs hit $50,000. Without proper debris removal coverage, that family would have faced a massive out-of-pocket expense just to clear their land.
For a deeper dive into protecting your rural home, check out our guide on Home Insurance for Rural Properties.
Outbuildings, Equipment & Livestock
Your barns, silos, grain bins, and equipment sheds aren’t just storage – they’re the heart of your operation. These structures need specialized coverage that understands their unique construction and the valuable contents they protect. Our Farm Building Insurance Policy guide walks you through the specifics of properly insuring these critical buildings.
Equipment coverage is where the numbers get serious fast. A single combine harvester can easily cost $300,000 or more, while a new tractor runs well over $100,000. We help our clients decide between scheduled coverage for their most expensive equipment and blanket coverage for general farm tools and machinery.
Livestock mortality coverage protects your animals from covered perils like fire, lightning, windstorms, and theft. Better policies extend this to include accidental shooting, vehicle strikes, and attacks by dogs or wild animals. For dairy operations, we often add coverage for veterinary expenses and temporary housing costs if your barns are damaged.
Transit coverage protects your animals and equipment while being transported to markets, shows, or between farm locations. One cattle rancher in Ledyard learned this lesson the hard way when his trailer overturned, resulting in significant livestock losses that transit coverage would have protected.
Liability Risks on the Farm
Farm liability is where things get complicated quickly. Premises liability covers injuries to visitors on your property, while operations liability protects against accidents caused by your farming activities away from the farm. If you sell products directly to consumers, product liability becomes essential protection.
Chemical drift liability has become increasingly important as neighbors become more sensitive to pesticide and herbicide applications. Environmental liability covers pollution cleanup costs from fuel spills or manure runoff – exposures that have grown more serious as environmental regulations tighten.
Agritourism activities create their own unique liability challenges. Farm tours, pumpkin patches, corn mazes, and wedding venues bring visitors who may not understand farm hazards. Our Farm Liability Insurance resource explains how to protect your operation from these growing risks.
Popular Endorsements & Add-Ons
Smart farm families customize their house and farm insurance with endorsements that address their specific risks. Flood insurance is crucial since standard policies exclude flood damage entirely. Equipment breakdown coverage protects against mechanical failures that could shut down critical operations during your busiest seasons.
Business interruption coverage helps replace lost income when covered perils prevent normal operations. This proved invaluable for a dairy farmer in Genoa whose milking parlor fire required weeks of repairs while he still had to maintain his herd.
Costs, Discounts & Customization Tips
Understanding house and farm insurance costs doesn’t have to feel like solving a math puzzle. At Farm & Country Insurance, we’ve been helping New York farm families steer premium calculations since 1984, and we’ve learned that a little knowledge goes a long way toward keeping your coverage affordable.
How Premiums Are Calculated
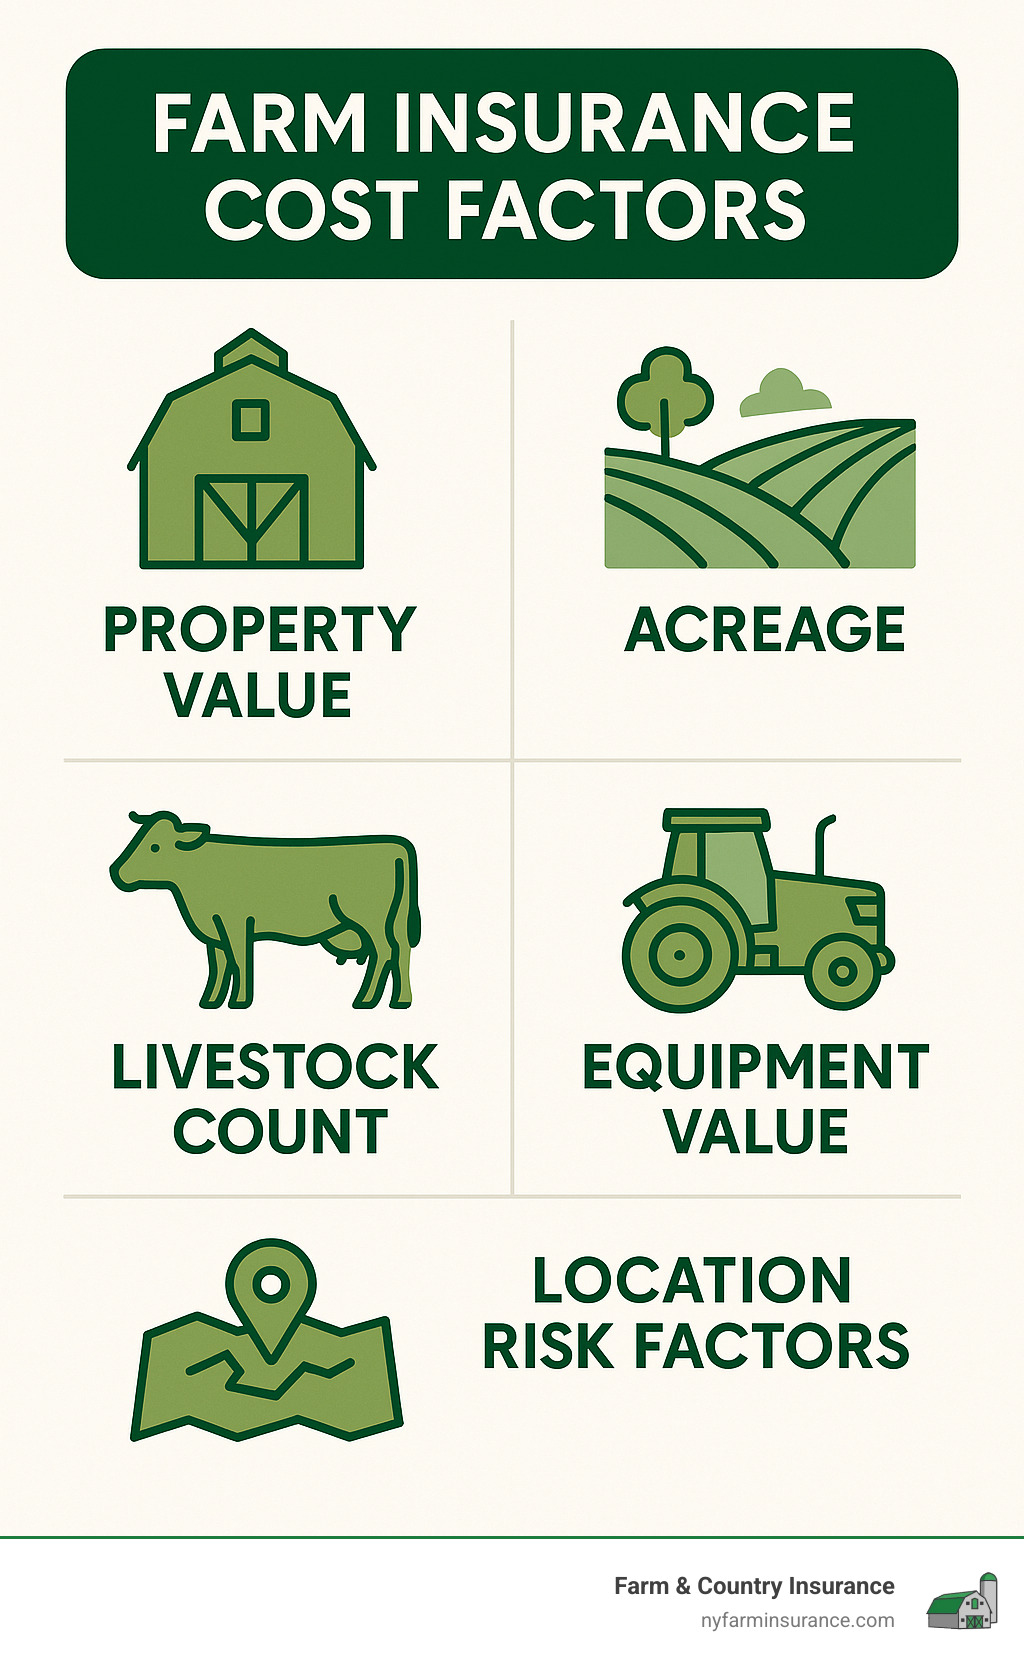
Your house and farm insurance premium starts with your location. Properties in Cayuga County face different weather patterns than farms in other parts of New York, and insurers price accordingly. Areas prone to severe storms, flooding, or high winds naturally cost more to insure.
Distance matters too. If you’re fifteen miles from the nearest fire department, that affects your rates differently than a farm just outside Auburn. Emergency response times play a real role in how much damage a fire or other emergency can cause.
The value of your assets makes the biggest difference in premium calculations. A modern dairy operation with robotic milking systems and climate-controlled barns costs more to insure than a simple grain storage facility. Every piece of equipment, every building, and every animal adds to your total exposure.
Money-Saving Moves
Smart risk management often pays for itself through insurance discounts. Installing lightning protection on your barns isn’t just good farming – it can reduce your premiums by 5-10%. One of our clients in Moravia saw his rates drop significantly after adding a comprehensive lightning system to his dairy barn.
Security systems earn discounts too. Cameras, alarms, and motion sensors don’t just protect your property – they show insurers you’re serious about preventing losses. The same goes for fire suppression systems and automatic shut-offs on equipment.
Bundling your policies creates the biggest savings opportunity for most farm families. When you combine your house and farm insurance with your auto coverage, umbrella policy, and other protections, discounts of 10-15% are common. We’ve helped clients save over $800 annually just by organizing their coverage properly.
Higher deductibles reduce premiums, but you need to balance savings against your ability to handle larger out-of-pocket costs. A $2,500 deductible instead of $1,000 might save you $200 annually, but make sure you can afford the difference if you need to file a claim.
Customizing House and Farm Insurance for Your Operation
Every farm operation tells a different story, and your house and farm insurance should match your unique situation. We work with dairy farmers who need extensive livestock coverage and vegetable growers who worry more about equipment and crop storage.
Scheduled coverage works best when you have specific high-value items like expensive tractors or combines. You list each piece of equipment with an agreed value, so there’s no guessing about coverage limits when you file a claim. Blanket coverage gives you a total limit for categories of property, which works well for operations with lots of smaller equipment items.
Regular inventory updates keep your coverage accurate as your operation grows and changes. We recommend annual reviews where we go through your equipment lists, livestock counts, and any operational changes. That new tractor you bought in July needs to be properly covered before harvest season.
Our Farm Homeowners Insurance guide provides detailed tools for maintaining accurate inventories and understanding your coverage options. The key is working with an agent who understands farming and can help you customize protection that fits both your operation and your budget.
Choosing & Bundling Providers for House and Farm Insurance
Finding the right provider for your house and farm insurance can feel overwhelming, but it doesn’t have to be. After nearly four decades helping New York farmers protect their operations, we at Farm & Country Insurance know exactly what to look for in an agricultural insurance provider.
The most important factor is finding an agent who truly understands agriculture. Look for AgWise Certified agents or similar agricultural specialization credentials. These professionals receive specialized training in farm risks that general insurance agents simply don’t have. There’s a world of difference between an agent who’s helped suburban families and one who’s walked through dairy barns at 5 AM understanding the real risks farmers face.
Local expertise matters tremendously in farming. An agent familiar with New York’s weather patterns, soil conditions, and agricultural challenges will serve you far better than someone trying to apply cookie-cutter solutions. We’ve seen too many farm families struggle with out-of-state insurers who don’t understand why a late spring freeze devastates fruit orchards or how quickly a barn fire can spread in dry conditions.
Claims handling reputation deserves serious research before you buy. When your barn roof gets torn off during harvest season, you need an insurer who responds quickly and pays fairly. Delayed claim settlements during critical farming periods can destroy an entire year’s income. Ask potential providers for references from other farm clients, and don’t be shy about calling those references.
For help finding qualified agricultural agents in your area, check out Find a farm agent.
Smart Bundling Strategies for Homesteads
Bundling your house and farm insurance with other policies creates real savings while simplifying your life. The key is understanding which combinations provide the best value for your specific operation.
Home and auto bundling forms the foundation of most farm insurance packages. Since farm families typically own multiple vehicles – from the family car to farm trucks – combining these policies often generates significant discounts. We regularly see clients save 10-15% on their total premiums through strategic bundling.
Commercial farm vehicle coverage becomes crucial when you’re hauling grain to market or transporting livestock. Regular auto policies exclude commercial use, leaving dangerous gaps in coverage. Bundling commercial and personal auto coverage often costs less than buying them separately while ensuring seamless protection.
Umbrella liability coverage provides the best insurance value available to most farm families. For a few hundred dollars annually, umbrella policies add millions in additional liability protection above your primary policy limits. Given the liability exposures from farming operations, equipment, and livestock, this extra protection is essential.
For smaller operations just getting started, our guide on Homeowners Insurance for Hobby Farms explains how to bundle coverage appropriately without overpaying for protection you don’t need.
Keeping Coverage Up-to-Date
Your house and farm insurance needs change constantly as your operation evolves. Equipment gets purchased, livestock numbers fluctuate, and new enterprises launch throughout the year. Staying on top of these changes protects you from dangerous coverage gaps.
Annual policy reviews should be comprehensive, not just a quick renewal conversation. We schedule detailed meetings with our clients each year to walk through equipment inventories, assess new risks, and adjust coverage limits. These reviews often uncover savings opportunities or identify exposures that need addressing.
Mid-season equipment purchases require immediate attention. Don’t wait until renewal to add that new combine or tractor to your policy. Most insurers allow mid-term additions with prorated premiums, and the coverage begins as soon as you complete the paperwork.
The farming business moves fast, and your insurance coverage needs to keep pace. Regular communication with your agent ensures your house and farm insurance continues protecting your operation as it grows and changes.
Frequently Asked Questions about House and Farm Insurance
After helping New York farm families secure house and farm insurance for decades, I’ve noticed the same questions come up time and again. Let me share the answers that matter most to rural property owners considering their coverage options.
Is house and farm insurance required by law or only by lenders?
Here’s something that surprises many farm families: house and farm insurance isn’t legally required by New York state or any other state government. You won’t get a ticket for operating without it, unlike auto insurance.
However, if you have a mortgage on your property or financing on your equipment, that’s a completely different story. Lenders almost always require comprehensive coverage as a condition of your loan. They want to protect their investment in your property and equipment, so they’ll specify minimum coverage amounts and typically require themselves to be named as additional insureds or loss payees on your policy.
Beyond what lenders require, carrying house and farm insurance is simply smart business. When you consider the value of a modern farmhouse, barn, equipment, and livestock, most farm families have hundreds of thousands or even millions of dollars at risk. One barn fire or severe storm could wipe out a lifetime of hard work without proper protection.
At Farm & Country Insurance, we’ve seen too many families face financial disaster because they thought they could get by with minimal coverage. It’s not worth the risk, especially when comprehensive protection is more affordable than most people expect.
How does the claims process work for a mixed home-and-farm loss?
When disaster strikes both your home and farm operations – like when a tornado damages your house, barn, and equipment all at once – the claims process requires careful coordination. The good news is that house and farm insurance policies are designed to handle these complex situations with a single experienced adjuster.
Your first step is thorough documentation. Take photos of everything damaged before you start cleanup, maintain detailed lists of damaged property, and preserve damaged items for the adjuster to inspect. This documentation becomes crucial when you’re dealing with both household items and expensive farm equipment.
The adjuster assigned to your claim will have agricultural experience, which makes a huge difference. They understand the difference between a hobby garden tractor and a commercial combine, and they know how to properly value livestock and assess crop losses. This expertise speeds up the process and ensures fair settlements.
Business interruption calculations add another layer of complexity to mixed losses. If your farming operation stops producing income because of the damage, you’ll need to provide documentation of lost revenue and ongoing expenses. The adjuster will work with you to calculate these losses fairly.
Timeline expectations should account for this complexity. While a simple house fire might settle in weeks, agricultural components often require equipment appraisals, livestock valuations, and crop assessments that can extend the process. Patience during this time usually results in more thorough and fair settlements.
How often should I review and update my house and farm insurance policy?
The short answer is annually, but the complete answer depends on how much your operation changes throughout the year. At Farm & Country Insurance, we schedule comprehensive policy reviews with our clients every year before their renewal date. This ensures coverage keeps pace with equipment values, operational changes, and evolving risks.
Some changes can’t wait for your annual review, though. Equipment purchases need immediate attention – don’t assume that new $200,000 combine is automatically covered under your existing policy. Livestock additions, operational changes like adding agritourism activities, and property improvements all require prompt policy updates.
Major life events also trigger the need for policy reviews. Getting married, divorced, or adding family members to your farming operation can affect coverage needs and beneficiary designations. Estate planning considerations become particularly important for multi-generational farm operations.
Seasonal operations benefit from more frequent check-ins. If you run a Christmas tree farm, maple syrup operation, or other seasonal business, your risk profile changes dramatically throughout the year. We often adjust coverage levels based on inventory fluctuations and seasonal activity patterns.
The key is staying in touch with your agent throughout the year, not just at renewal time. A quick phone call when you make major purchases or operational changes can prevent costly coverage gaps when you need protection most.
Conclusion
Your homestead deserves protection that goes beyond what standard homeowners insurance can offer. House and farm insurance bridges the dangerous gaps between residential and agricultural coverage, giving you the comprehensive protection your unique property demands.
After nearly four decades of helping New York farm families, we at Farm & Country Insurance understand that every farm operation tells its own story. Whether you’re milking cows at dawn in Auburn, tending vegetable gardens in Fleming, or welcoming visitors to your agritourism venture in Owasco, your risks are as unique as your operation.
The reality is simple: mixing residential living with agricultural activities creates exposures that standard policies simply weren’t designed to handle. That expensive combine in your barn, the dairy herd in your pasture, and the liability from farm visitors all need specialized protection that only house and farm insurance provides.
We’ve seen too many farm families learn about coverage gaps the hard way. The dairy farmer whose homeowners policy excluded his livestock losses. The hobby farmer whose visitor injury wasn’t covered. The grain operation that faced environmental liability claims with no protection. These stories don’t have to be yours.
Since 1984, Farm & Country Insurance has been the trusted partner for farm families throughout Cayuga County and beyond. Our deep understanding of agricultural risks means you get coverage that actually fits your operation – not a one-size-fits-all policy that leaves you vulnerable when you need protection most.
Your farm represents generations of hard work, family dreams, and financial investment. Protecting it with comprehensive house and farm insurance isn’t just smart business – it’s essential for your family’s future. When storms hit, accidents happen, or liability claims arise, you’ll have the peace of mind that comes from knowing you’re properly protected.
Don’t wait for a wake-up call to find your coverage gaps. Take the first step toward comprehensive protection today. Our Farm Insurance Near Me guide can help you understand your local options, or contact Farm & Country Insurance directly to discuss how we can customize coverage for your specific needs.
Your homestead is more than property – it’s your livelihood, your legacy, and your home. Let us help you protect it all with the specialized coverage it deserves.