
Why Protecting Your Farm Buildings is Critical for Your Operation’s Future
Insurance for farm buildings protects the structures that house your livestock, equipment, and crops from financial losses due to covered perils like fire, wind, and theft. Here’s what you need to know:
Key Coverage Areas:
- Barns, silos, and outbuildings – Physical structure protection
- Built-in equipment – Milking systems, augers, water pumps
- New construction – Automatic coverage for up to 60 days
- Building code compliance – Costs to meet updated regulations
- Business interruption – Lost income from damaged facilities
Common Exclusions:
- Wear and tear from normal use
- Flood damage (requires separate coverage)
- Poor maintenance issues
As one farmer found after a devastating barn fire: “If you experience property damage or theft, facing the financial burden without proper insurance can be overwhelming.” Your farm buildings represent a massive investment.
The financial stakes are high. A single storm can destroy structures that took decades to build. Without proper coverage, rebuilding costs could be financially devastating while you still meet loan payments on destroyed assets.
Standard homeowners insurance won’t protect your farm buildings because it excludes business operations and agricultural structures. You need specialized coverage that understands the unique risks of farming—from equipment breakdown in milking parlors to crop contamination from building damage.
I’m Casey Love, owner of Farm & Country Insurance, and I’ve spent years helping New York farmers protect their operations with comprehensive insurance for farm buildings. My agency specializes in farm coverage because I understand your buildings are the foundation of your livelihood.


Insurance for farm buildings word list:
What’s Covered? From Barns and Silos to Built-in Equipment
When we discuss insurance for farm buildings, we mean more than just a simple barn. New York farms, from Cayuga County to the broader state, have diverse, specialized structures housing critical equipment. Our policies are designed to cover this extensive range of assets.
Typically, a comprehensive farm building insurance policy includes protection for:
- Barns and Stables: The heart of the farm, housing livestock, feed, and equipment.
- Silos and Grain Bins: Essential for storing and protecting your harvest.
- Sheds and Outbuildings: Includes machine sheds, workshops, and general utility buildings.
- Greenhouses and High Tunnels: Critical for fruit and vegetable farmers to control growing environments.
- Processing Facilities: Structures for dairy processing, fruit packing, or vegetable washing.
- Confinement Buildings: Specialized structures for livestock, such as hog barns or poultry houses.
- Dairy Parlors: Highly specialized buildings with intricate milking systems.
- Portable Buildings: Movable structures that still represent a valuable investment.
- Fencing and Corrals: Integral parts of livestock operations that can be costly to replace.
Beyond the structures, our insurance for farm buildings policies can extend to fixtures and equipment that are integral to the building’s function. This often includes:
- Milking Systems: The network of pipes, pumps, and machinery in a dairy parlor.
- Built-in Augers and Dryers: Essential for grain handling and storage.
- Water Pumps and Motors: Critical for irrigation and livestock watering.
- Fixed Irrigation Equipment: Components fixed to a building or part of its immediate operation.
It’s not just about four walls and a roof; it’s about your farm’s entire ecosystem. For a deeper dive into protecting your most iconic farm structures, read our guide on Barn Insurance Coverage.
Key Differences from a Standard Homeowners Policy
A common misconception is that a standard homeowners policy is enough for a farm, but it’s designed for personal, not commercial, risk. A homeowners policy explicitly excludes protection for farm property, operations, and equipment. It won’t cover your barn if it collapses under snow or your tractor if it’s damaged in a fire. Even small agricultural enterprises, like a hobby farm, fall outside the scope of standard home insurance.
For any farm operation in New York, from a sprawling dairy farm in Moravia to a small fruit orchard in Ledyard, a homeowners policy is inadequate. It doesn’t recognize your unique assets or the specific risks of agricultural activities. This means your outbuildings, equipment, and farm-related liability would not be covered.
Here’s a quick comparison to highlight these critical differences:
| Feature | Standard Homeowners Policy | Farm Insurance (including Farm & Country Insurance policies) |
|---|---|---|
| Primary Focus | Personal dwelling and household possessions | Integrated coverage for personal dwelling, farm property, and commercial farm operations |
| Covered Structures | Home, detached garages, small sheds (non-business use) | Home, barns, silos, sheds, greenhouses, processing facilities, confinement buildings, etc. |
| Business Operations | Generally excluded | Fully covered, including income-generating activities and associated risks |
| Farm Personal Property | Not covered (e.g., tractors, livestock, harvested crops) | Covered (machinery, equipment, livestock, grain, tools, supplies) |
| Liability | Personal liability (e.g., guest injury at home) | Personal and farm-related liability (e.g., farm visitor injury, product liability, environmental) |
| Equipment Breakdown | Limited to household appliances | Can include specialized farm equipment and built-in systems |
| Business Interruption | Not applicable | Can cover lost income if farm operations are halted due to covered damage to buildings |
Even if you consider your farming a passion project, the risks are real. That’s why we always recommend specialized coverage. If you’re running a smaller operation, our Hobby Farm Insurance might be what you need. For a comprehensive look at how your home and farm assets can be covered together, explore our Farm Homeowners Insurance options.
Understanding Covered Perils and Common Exclusions
Understanding what your insurance for farm buildings policy protects against—and what it doesn’t—is vital. Policies define “Causes of Loss” in different forms: Basic, Broad, and Special.

- Basic Form: Covers a specific list of perils, including fire, lightning, windstorm, hail, and vandalism. It’s the most limited coverage.
- Broad Form: Adds to the Basic Form, including perils like falling objects, weight of ice, snow, or sleet, and collapse. Given New York’s winters, this is particularly relevant.
- Special Form (often called “all-risk”): The most comprehensive option. It covers all direct physical loss or damage unless specifically excluded, offering the broadest protection.
Common perils our policies protect against include:
- Fire: A devastating risk, especially for barns storing hay. For more, see our article on Farm Fire Insurance.
- Windstorms and Hail: Can cause significant damage to roofs, siding, and entire structures.
- Lightning: Can cause direct strikes or power surges that damage electrical systems.
- Vandalism and Theft: Protecting your structures from malicious damage or theft.
- Weight of Ice and Snow: A major risk in New York winters that can cause roof collapse.
It’s equally important to be aware of common exclusions. Insurance is for sudden, accidental losses, not gradual issues. Standard exclusions include:
- Wear and Tear, Deterioration, or Lack of Maintenance: Damage from neglect or aging.
- Flood: Damage from floodwaters is typically excluded and requires a separate policy, often through the National Flood Insurance Program (NFIP).
- Earthquake: Usually requires a specific endorsement or separate policy.
- Settling, Shrinking, Bulging, or Expansion: Damage from natural ground movement over time.
- Infestation: Damage caused by insects, rodents, or other pests.
We work with our clients in places like Auburn and Cato to ensure they understand their policy’s specific perils and exclusions.
Customizing Your Insurance for Farm Buildings and Managing Costs
Every New York farm is unique, and your insurance for farm buildings policy should be too. Tailoring your coverage ensures you get adequate protection while managing costs. This customization involves choosing the right valuation method and deductible.
Valuation Methods: Replacement Cost vs. Actual Cash Value (ACV)
When insuring your farm buildings, we’ll look at two main valuation methods:
- Replacement Cost (RC): This is often the best option. If your building is damaged, this method pays to repair or rebuild it with new materials of similar kind and quality, without subtracting for depreciation. For an older barn in Owasco, Replacement Cost provides the funds to rebuild it as a functional, modern structure, helping you get back to business without a huge out-of-pocket expense.
- Actual Cash Value (ACV): This method pays the replacement cost minus depreciation, accounting for the age and condition of your building. While ACV policies usually have lower premiums, the payout after a loss will be less, potentially leaving a large gap between what insurance pays and the actual cost to rebuild.
At Farm & Country Insurance, we generally recommend Replacement Cost coverage for farm buildings whenever possible, as it offers the most complete financial protection.
Your deductible is what you pay out-of-pocket before your insurance coverage begins. A higher deductible can lower your premium, but it means you’ll pay more upfront on a claim. We’ll work with you to find a balance that saves on premiums while ensuring the deductible is manageable.
Finally, policy limits are the maximum amount your insurer will pay for a covered loss. It’s crucial these limits reflect the actual value of your farm buildings. We encourage regular reviews to ensure your limits keep up with rising construction costs. If you’re wondering if your farm property is adequately covered, our article Is Your Farm Property Underinsured? The Answer Might Surprise You offers valuable insights.
What are the key factors that affect the cost of insurance for farm buildings?
The cost of insurance for farm buildings is not one-size-fits-all. Many factors come into play, reflecting the unique risks of your New York farm.
Your location is a key factor. Proximity to risks like severe weather can increase premiums, while being near fire protection services can lower them.
The construction type and materials of your buildings matter. Concrete and steel structures may be less expensive to insure than older wooden barns because they are more fire-resistant. The age and condition of buildings also matter; newer, well-maintained buildings usually pose less risk and could qualify for better premiums.
The farm type and operations you run directly influence risk. A dairy farm with milking parlors has different needs than a grain farm with storage silos. Our deep understanding of New York’s dairy, grain, fruit, and vegetable farms allows Farm & Country Insurance to tailor policies precisely for you.
Your claims history can also impact future premiums. A history of frequent claims might suggest a higher risk. Finally, proactive security measures (alarms, cameras) and good fire protection (extinguishers, clear access for fire trucks) can help reduce risk and potentially lower your premiums. As mentioned, your deductible amount also plays a part—a higher deductible generally means a lower premium.
We pride ourselves on understanding these nuances. For specific information on barn insurance in our state, check out our page on Barn Insurance New York.
Does insurance for farm buildings cover new construction?
Yes, absolutely! We know farms are always growing. Many comprehensive insurance for farm buildings policies, including those from Farm & Country Insurance, provide automatic coverage for new construction and structural alterations.
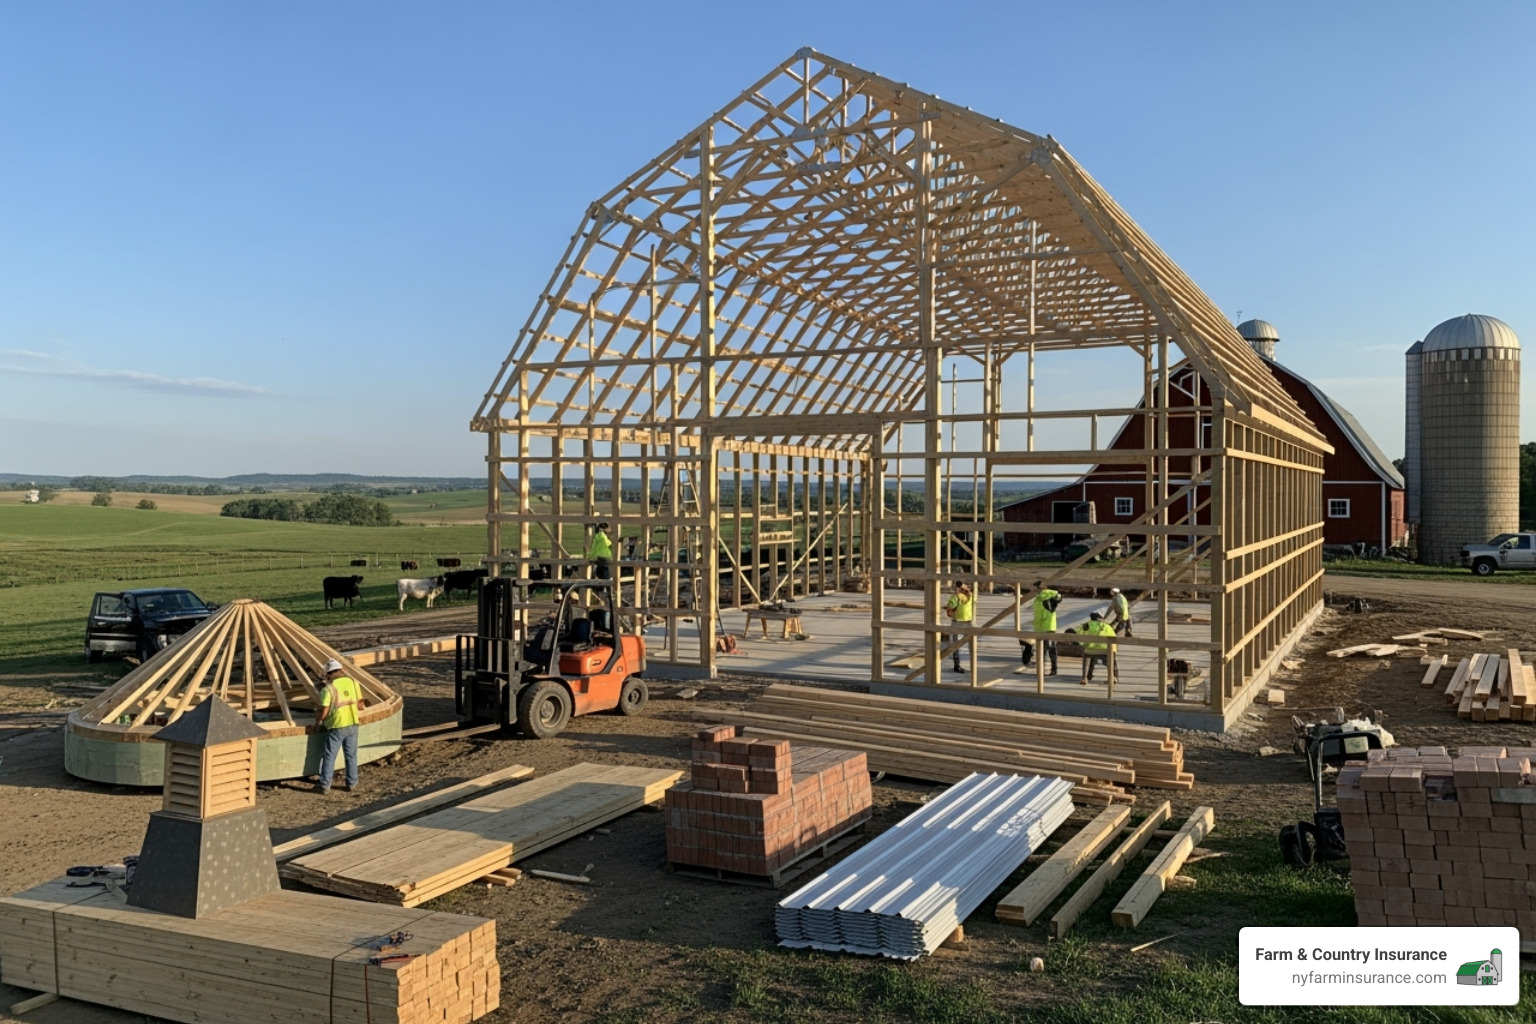
This automatic coverage is a crucial safety net during the high-risk construction phase. Typically, this coverage lasts for a set period, like 60 days, or until your next policy renewal, and has a specified limit (e.g., up to $250,000 for new barns). This means if a fire or windstorm damages your new barn while it’s being built, you have initial protection.
However, it’s critical to notify Farm & Country Insurance as soon as possible about any new construction. While automatic coverage is a good start, it’s temporary. To ensure your new asset is fully insured for its completed value, we need to officially add it to your policy and adjust your coverage limits. This also applies to building materials you’ve bought for the project, which are often covered while on your premises.
Keeping us in the loop about your farm’s growth is key to continuous protection. A quick call to your Farm & Country Insurance agent in places like Scipio or Sennett can ensure your investment is protected.
Frequently Asked Questions about Farm Building Protection
You’ve got questions, and we’ve got answers! Here are some of the most common questions our New York farm families ask about insurance for farm buildings.
Can I insure a barndominium under a standard farm policy?
Barndominiums, which combine living space with a farm workspace, are growing in popularity. Because they mix residential and commercial uses, they create a unique insurance challenge. A typical homeowners policy will likely miss the commercial parts, and a basic farm policy might not fully protect the residential dwelling.
What you need is a specialized, comprehensive plan. Our House and Farm Insurance options at Farm & Country Insurance are designed for these situations. They blend residential and commercial coverage to ensure every part of your barndominium—from living room to workshop—is fully protected. We can craft a policy that leaves no gaps in your coverage.
What happens if building codes change after a loss?
This is a critical question. Imagine your barn in Montezuma is damaged, and when you rebuild, you find local building codes have been updated. These new rules could demand more expensive materials or construction methods. A standard insurance for farm buildings policy might only pay to rebuild what you had before, leaving you to cover these extra costs.
This is where an “Ordinance or Law” endorsement becomes invaluable. This optional coverage helps pay for the increased costs of rebuilding or repairing to meet current building codes. It can cover demolition of undamaged sections, the higher cost of new materials, and related professional fees. We strongly recommend talking to your Farm & Country Insurance agent about adding this endorsement to save you from significant, surprising expenses.
Are contents like tools and harvested crops covered?
It’s important to understand this distinction. Insurance for farm buildings covers the physical structure, while the valuable items inside are covered under a separate but vital part of your policy: “Farm Personal Property” coverage.
This matters because the value of your farm’s contents can be extremely high. Farm Personal Property coverage can protect a wide range of crucial assets, including:
- Farm machinery and equipment like tractors and combines.
- Tools, from hand tools to workshop equipment.
- Livestock, such as dairy cattle, poultry, or other farm animals.
- Harvested crops and produce, like grain, hay, and silage stored in your buildings.
- Supplies like fertilizers, pesticides, and feed.
So, while a collapsed barn roof would be covered, the combine stored inside would be protected under your Farm Personal Property section. It’s essential to ensure both your buildings and their contents are properly valued and protected. For details, check your Farm Building Insurance Policy documents or reach out to us at Farm & Country Insurance.
Conclusion: Secure Your Legacy with Regular Policy Reviews
Insurance for farm buildings is more than a policy; it’s a critical investment in your farm’s future. This financial protection safeguards the structures that are the backbone of your operation, from dairy parlors to equipment sheds. A well-crafted, comprehensive policy can be the difference between a swift recovery and overwhelming financial challenges.
Here in New York, farming is anything but static. Whether you’re running a grain operation in Ira, a fruit farm in Venice, or a dairy farm in Springport, your business is constantly evolving. Your assets change, operations grow, and risks shift. That’s why, when it comes to your insurance for farm buildings, it’s not enough to “set it and forget it.”
Think of your annual policy review as a vital check-up for your farm’s financial health. It’s the perfect time to discuss changes on your farm. Have you added a new barn, expanded a greenhouse, or made structural alterations? Have you invested in new equipment? Has your farm operation shifted? All these changes affect your risk profile and asset values. We also need to consider fluctuating market values for construction to ensure your buildings are insured for their current replacement cost, preventing you from being underinsured.
At Farm & Country Insurance, we’ve been rooted in the New York farming community since 1984. Our expertise is in understanding the unique challenges and triumphs of farming life. We offer comprehensive coverage and risk management services custom-fit for dairy, grain, fruit, and vegetable farms, as well as agribusinesses, across Cayuga County and the wider New York state.
We’re here to be your trusted partner. By working closely with us, you can rest easy knowing that your insurance for farm buildings always reflects the dynamic reality of your evolving farm. This ensures your hard-earned assets are always protected, helping to secure the legacy you’re building for generations to come. Don’t leave your hard work to chance.
Learn more about our specialized insurance for dairy farms and find how we can help protect every vital aspect of your operation.