
Why Your Farm Equipment Investment Deserves Professional Protection
Insurance for farm equipment is specialized coverage that protects your agricultural machinery from damage, theft, and other perils. It provides a crucial financial safety net, helping you repair or replace vital equipment to ensure business continuity when the unexpected happens.
Your tractors and combines represent massive investments, with modern machinery often costing hundreds of thousands of dollars. Without proper insurance, a single event—like a barn fire, theft, or storm damage—could devastate your farm’s finances. The risks are real: nearly 1,500 tractors are stolen annually, with few recovered, and complex machinery can incur repair bills exceeding $12,000 from a single breakdown.
I’m Casey Love, an insurance agency owner. For years, I’ve helped New York farmers secure their most valuable assets with comprehensive insurance for farm equipment. My experience has shown that the right policy is the difference between a temporary setback and a disaster that threatens your farm’s future.
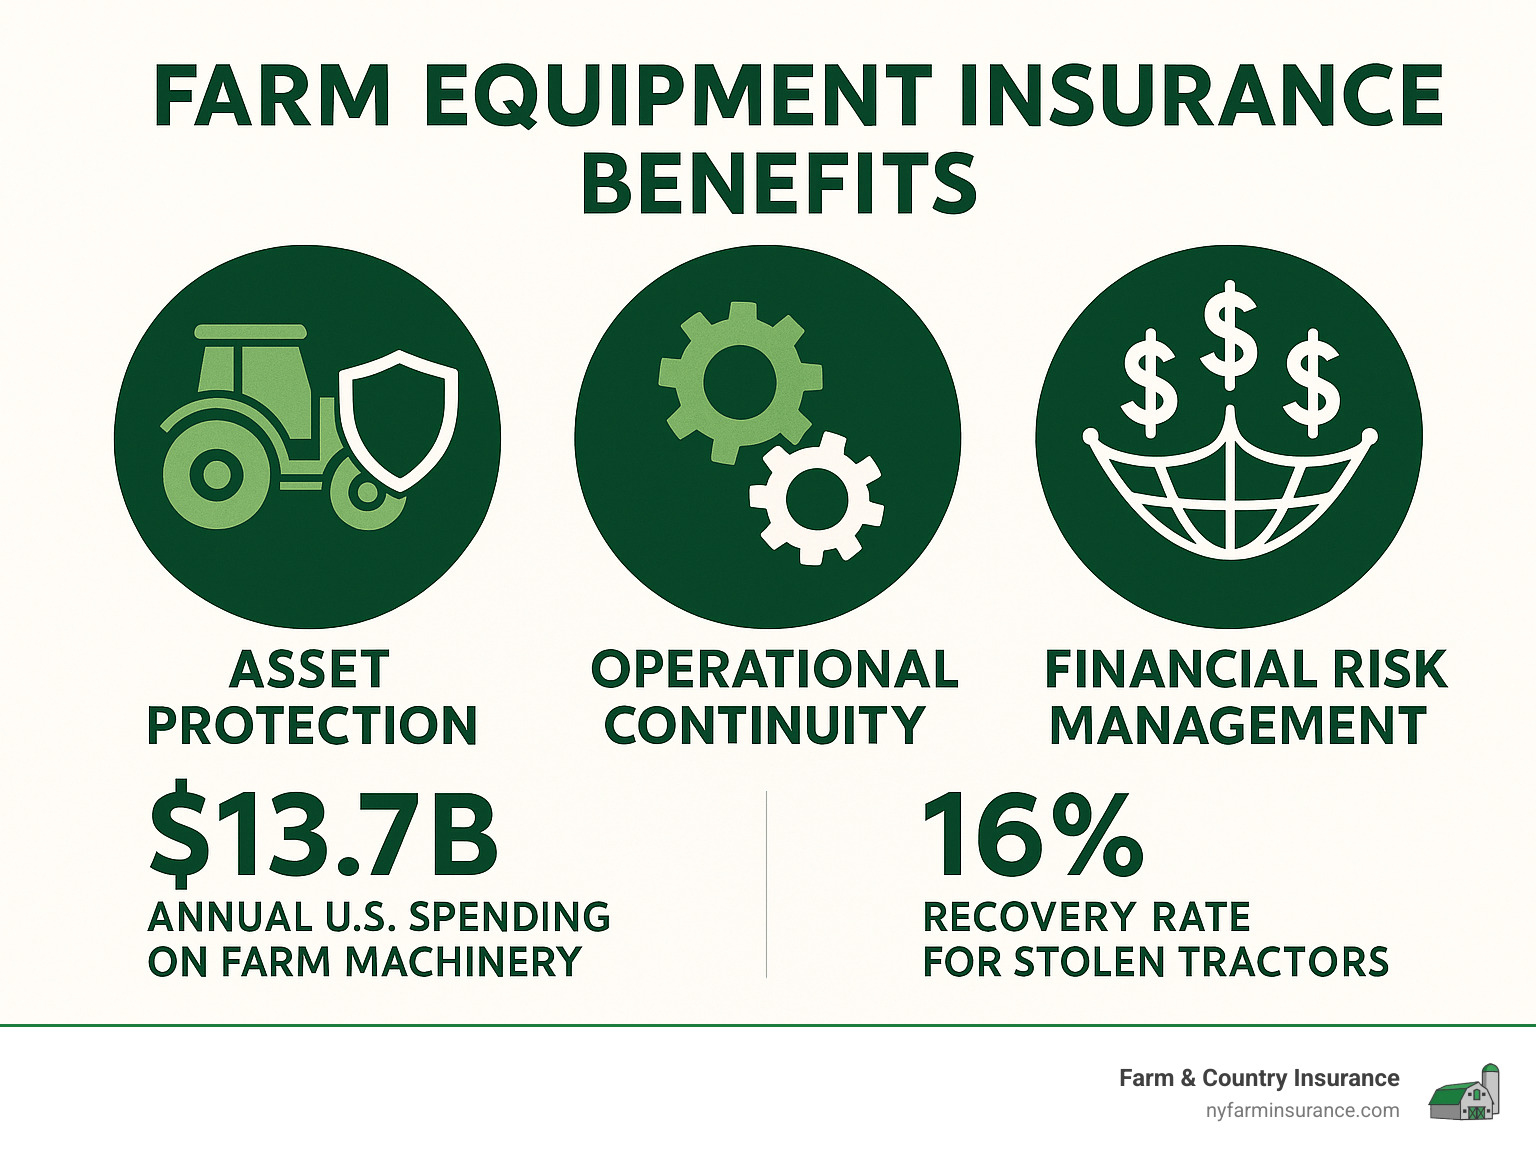
Insurance for farm equipment terms to remember:
Why Your Farm’s Mechanical Muscle Needs Protection
Your farm’s success depends on its mechanical muscle. From a dairy in Cayuga County to grain fields across New York, your tractors, combines, and specialized equipment are the heartbeat of your operation. These machines are significant investments, and protecting them with insurance for farm equipment is essential for keeping your farm running.
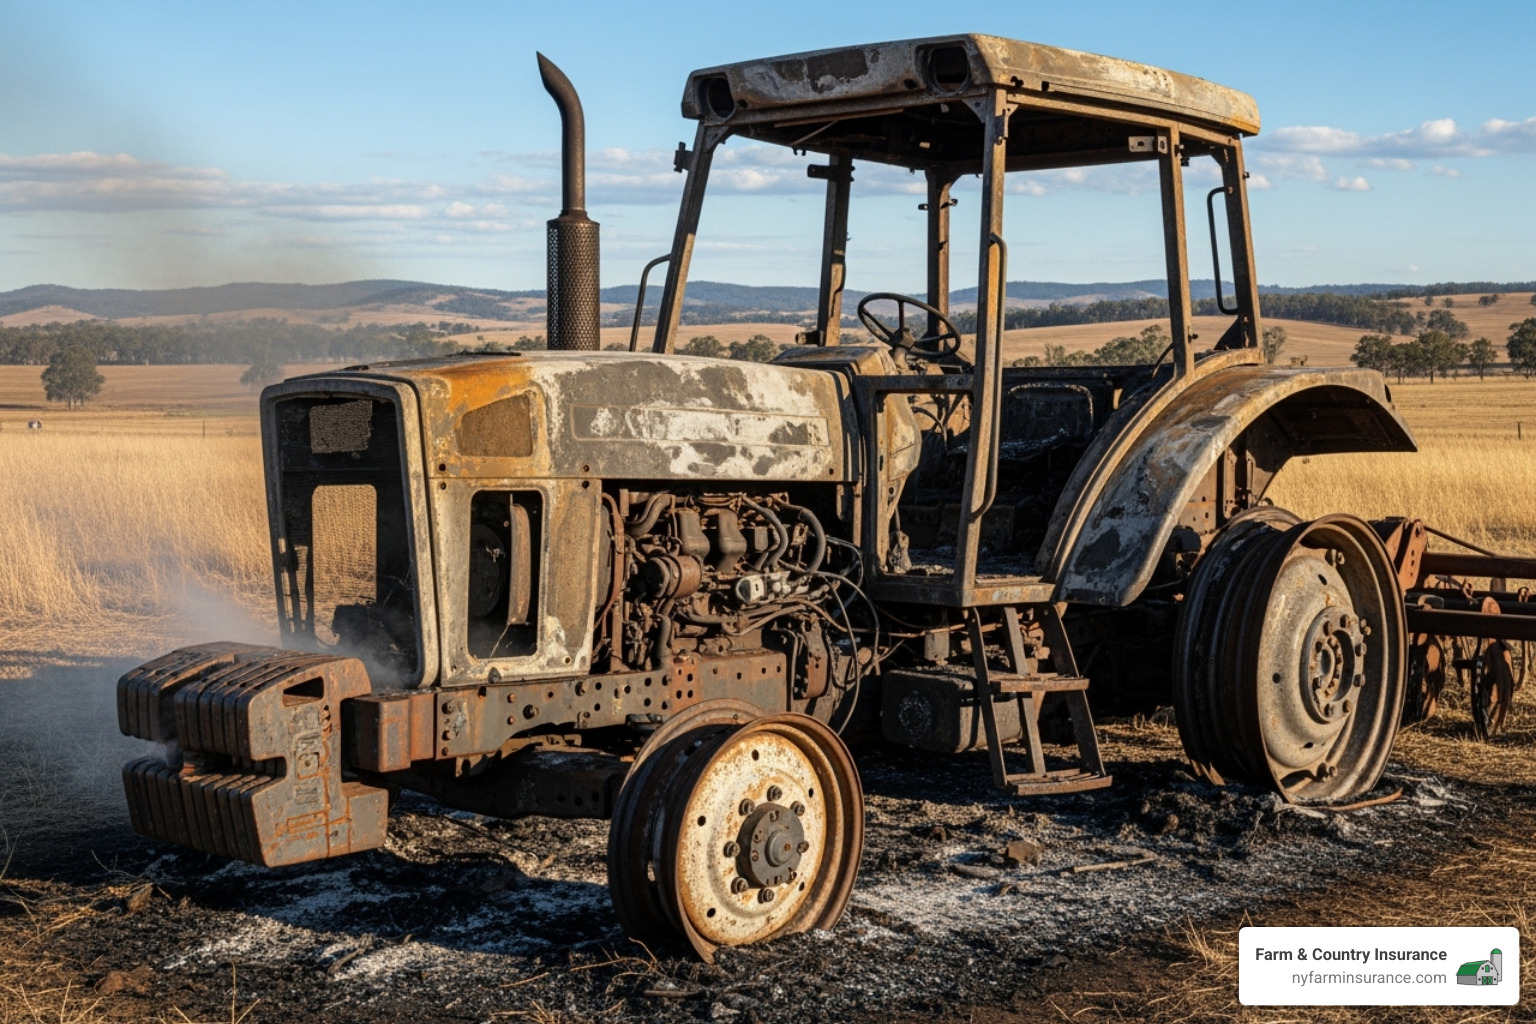
Modern agriculture relies on sophisticated, expensive machines. A single barn fire, stolen tractor, or severe storm can wipe out years of investment. New York’s weather can be particularly unforgiving, with lightning, hail, and windstorms posing a constant threat. When your primary tractor breaks down during planting season, you face not just repair costs but potential crop losses and rental expenses. This is why agricultural equipment insurance exists—to shield farmers from the financial devastation of equipment loss.

Common Risks and Perils Covered
Insurance for farm equipment policies are designed to cover the real-world perils New York farmers face:
- Fire: A leading cause of loss, whether in a barn or from an electrical issue within the machinery itself. For more on this, see our guide to Farm Fire Insurance.
- Lightning and Electrical Damage: A power surge can fry the delicate, expensive electronics that control modern equipment.
- Weather-Related Damage: Windstorms, hail, and flooding can overturn machinery, shatter glass, and cause total losses.
- Theft and Vandalism: A growing problem in rural areas, targeting valuable and often remotely stored equipment.
- Collision and Overturn: Covers accidents on uneven ground or on public roads.
- Foreign Object Ingestion: Protects against internal damage when equipment accidentally picks up rocks, metal, or other debris, which can cause thousands in repairs.
What Types of Farm Equipment Can Be Insured?
Comprehensive insurance for farm equipment can protect virtually every valuable piece of machinery on your farm:
- Tractors: The backbone of any operation, from compact utility models to large field tractors.
- Combines and Harvesters: Often the most valuable single piece of equipment on a farm.
- Planters and Sprayers: Increasingly sophisticated and expensive due to precision technology.
- Hay Equipment: Critical tools like balers, rakes, and mowers represent significant investments.
- Irrigation Systems: Center pivots and other water management systems are expensive and vital for crop success.
- Precision Agriculture Technology: GPS systems, yield monitors, and automated steering add significant value to machinery.
- Smaller Equipment: The collective value of tools, shop equipment, and farm office computers can be substantial.
For specific information on protecting your most important asset, see our guide on Insurance for a Tractor. The key is working with a provider who understands that every farm is different and can design coverage that fits your unique operation.
Key Coverage Options for Insurance for Farm Equipment
Choosing the right insurance for farm equipment means tailoring the protection to your farm’s specific needs. This customization often comes down to how your equipment is listed and valued on your policy. The two primary methods are scheduled and blanket coverage.
Here’s a quick look at the two main ways we can set up your coverage:
| Feature | Scheduled Coverage | Blanket Coverage |
|---|---|---|
| Itemization | Each piece of equipment is listed with a specific value. | All equipment covered under one aggregate total limit. |
| Flexibility | Less flexible; requires policy updates for changes. | Highly flexible; new items automatically covered (up to limit). |
| Premiums | Often lower for specific high-value items. | Can be higher due to broader coverage. |
| Best Use Cases | High-value, unique, or infrequently changing equipment. | Diverse inventory, frequent additions/changes, smaller implements. |
| Valuation | Precise, item-by-item valuation. | Overall valuation, with individual item limits often applied. |
| Claim Process | Straightforward as value is pre-determined. | May require proving value of individual items during claim. |
Scheduled vs. Blanket Coverage: Which Is Right for You?
When setting up your insurance for farm equipment policy, we’ll help you decide between two main approaches:
Scheduled Coverage lists each piece of equipment with a specific insured value. This is ideal for high-value machinery like your primary combine or tractor, as the value is pre-agreed, simplifying the claims process. It’s best for farms with a stable inventory, but you must remember to update the policy when you buy or sell equipment.
Blanket Coverage protects all your farm equipment under one aggregate limit. This offers great flexibility, as newly acquired items are often automatically covered without an immediate policy update. It’s perfect for farms with a diverse and changing inventory of smaller implements and tools. Be aware that there may be sub-limits for individual items.
Many New York farms benefit from a hybrid approach, scheduling high-value, critical pieces while using blanket coverage for all other implements and tools. This combines precision with flexibility. For more details, see our guide on Farm Equipment Insurance Coverage.
Property Damage vs. Liability Coverage: What’s the Difference?
It’s crucial to understand two distinct types of protection for your farm:
Property Damage Coverage is what most people think of as insurance for farm equipment. It protects the physical machinery itself from covered events like fire, theft, or collision. This coverage pays to repair or replace your assets to get you back to work quickly.
Liability Coverage protects you from claims made by others. If your farm equipment causes bodily injury or damages someone else’s property (e.g., hitting a neighbor’s fence), this coverage responds. Standard equipment policies do not include liability protection. It is provided under a separate farm liability insurance policy, which is essential for shielding your business from costly lawsuits.
At our agency, we ensure your property and liability policies work together to eliminate coverage gaps. Learn more about this vital protection at Farm Liability Insurance.
Understanding Policy Details and Costs
Navigating an insurance for farm equipment policy requires understanding key components like premiums, deductibles, and endorsements. Knowing these details ensures you get the right protection without overspending. Your policy is a vital contract, and we’re here to clarify the language so you can be confident in your coverage.
Factors That Influence Your Insurance Premiums
Your premium for insurance for farm equipment is calculated based on several factors:
- Equipment Value, Age, and Condition: Higher-value and newer equipment costs more to insure because the potential replacement cost is greater.
- Type and Horsepower: Specialized or high-power machinery carries different risk profiles and repair costs.
- Farm Location: Rates can be affected by regional risks like severe weather frequency or higher theft rates.
- Claims History: A history of frequent or large claims can increase your premiums.
- Security Measures: Proactive steps like security lighting or locked storage can often earn you a discount.
- Deductible Amount: Choosing a higher deductible (the amount you pay out-of-pocket) will lower your premium.
It’s important to ensure your coverage levels are adequate. Learn more here: Is Your Farm Property Underinsured? The Answer Might Surprise You!.
Enhancing Your Policy with Optional Endorsements
Optional endorsements allow you to customize your insurance for farm equipment policy for more complete protection:
- Replacement Cost Coverage: Pays to replace damaged equipment with a brand-new model, avoiding deductions for depreciation. This is crucial for newer machinery.
- Equipment Breakdown Coverage: Covers losses from internal electrical or mechanical failures, which are not covered by a standard policy. Learn more at Farm Equipment Breakdown Coverage.
- Rented or Borrowed Equipment: Extends your coverage to machinery you’re temporarily using, often more affordably than the rental company’s insurance.
- Cab Glass Coverage: Covers breakage of expensive cab glass, often with a low or zero deductible.
- Loss of Use/Rental Reimbursement: Helps cover the cost of renting a replacement machine if your primary equipment is down for repairs during a critical season.
- Foreign Object Ingestion: Specifically covers internal damage caused when foreign objects are pulled into your machinery.
Common Policy Exclusions and Limitations
It’s also important to know what your policy typically doesn’t cover. Exclusions ensure that coverage is for sudden and accidental losses, not predictable issues. Common exclusions include:
- General Wear and Tear: Gradual deterioration from normal use, rust, or corrosion.
- Failure to Maintain Equipment: Damage resulting from a lack of proper maintenance.
- Intentional Damage: Losses caused deliberately by the policyholder.
- Mechanical Breakdown: Internal failures are excluded unless you have the specific endorsement.
- Catastrophic Events: Nuclear hazards, war, and terrorism are standard exclusions.
Always review your policy documents with us to understand all terms and limitations, ensuring there are no surprises during a claim.
How to Choose the Right Plan
Selecting the right insurance for farm equipment is like choosing the right tool for the job—it needs to fit your specific needs and goals. We’ve helped New York farmers build policies based on a clear understanding of their unique operations since 1984.
The foundation of a good policy is knowing what you’re protecting and what risks concern you most. Your insurance should reflect the uniqueness of your farm, not force you into a one-size-fits-all box.
Steps to Selecting the Right Insurance for Farm Equipment
Building the right policy involves careful preparation. Follow these steps to ensure nothing is overlooked:
- Create a complete equipment inventory. List the make, model, year, serial number, and current value for every piece of machinery. Keep photos and maintenance records.
- Assess your farm’s specific risks. Consider your location’s vulnerability to floods, storms, or theft. A fruit grower’s risks differ from a grain farmer’s.
- Compare replacement cost vs. actual cash value. Replacement cost (RC) pays for a new machine and is best for newer equipment. Actual cash value (ACV) pays the depreciated value and may be more economical for older machinery.
- Choose your deductible wisely. A higher deductible lowers your premium, but ensure it’s an amount you can comfortably pay out-of-pocket during a claim.
- Review your policy annually. Your equipment inventory and values change over time. An annual review prevents dangerous coverage gaps.
The Role of a Specialist Agent
Working with a specialist agent who understands farming is essential for getting the right protection. Agriculture is all we do.
- Industry Knowledge: Our exclusive focus on New York farms since 1984 means we understand the unique risks of your operation, whether it’s a dairy in Cayuga County or a local vegetable farm.
- Risk Management Advice: We provide practical advice, not just policy sales, helping you identify ways to reduce risk and potentially lower your premiums.
- Access to Multiple Carriers: As independent agents, we shop multiple insurance carriers to find the best combination of coverage and price for you.
- Claims Advocacy: When a claim occurs, we are your advocate, guiding you through the process to ensure a fair and prompt settlement.
Working with local specialists makes all the difference. Learn more about the benefits here: Local Heroes: Best Farm Insurance Agents Near You.
Frequently Asked Questions about Farm Equipment Insurance
We’ve helped countless New York farmers steer insurance for farm equipment. Here are answers to some of the most common questions we hear.
How does replacement cost coverage work for older machinery?
The age of your equipment is a key factor in how a claim is settled. Newer equipment (typically under 5-8 years old) often qualifies for full Replacement Cost (RC) coverage, which pays to replace it with a brand-new, similar model. For older equipment, coverage usually shifts to Actual Cash Value (ACV). ACV pays the replacement cost minus depreciation for age and wear. This can create a significant financial gap; for example, a 12-year-old tractor costing $180,000 new might have an ACV of only $95,000. We always discuss these differences upfront to avoid surprises.
Can I insure borrowed or rented equipment?
Yes, and it’s a smart move. Most insurance for farm equipment policies can be improved with an endorsement to cover borrowed or rented machinery while it’s in your care. This is typically far more cost-effective than purchasing daily insurance from the rental company. The endorsement protects the borrowed equipment against the same perils as your owned machinery, providing peace of mind and preventing a favor from turning into a financial burden.
Is my equipment covered if I use it off my property?
Generally, yes. A well-designed insurance for farm equipment policy is built for the reality of modern farming. Your machinery is typically covered on your farm, in transit on public roads, and while being used on other properties for farm work, such as helping a neighbor or doing custom harvesting. The geographical limits are usually generous, but it’s always wise to confirm the specifics of your policy with us, especially if you do extensive work far from your home base.
Conclusion: Secure Your Farm’s Future
Your farm equipment is more than just an investment; it’s the engine of your livelihood and legacy. Protecting these critical assets with comprehensive insurance for farm equipment is one of the smartest decisions you can make for your farm’s long-term stability.
A proper policy ensures that a fire, theft, or breakdown is a manageable setback, not a financial catastrophe. We’ve specialized in protecting New York farms since 1984. We understand the unique risks you face in areas like Cayuga County and beyond.
We don’t sell one-size-fits-all policies. We partner with you to build customized coverage that safeguards your machinery and your future. Don’t leave your most valuable assets vulnerable.
Ready to protect what you’ve worked so hard to build? Contact our farm insurance brokers today to get a personalized quote and find how the right coverage can secure your farm’s future.