
Why Insurance for Hobby Farms is Essential for Your Rural Dreams
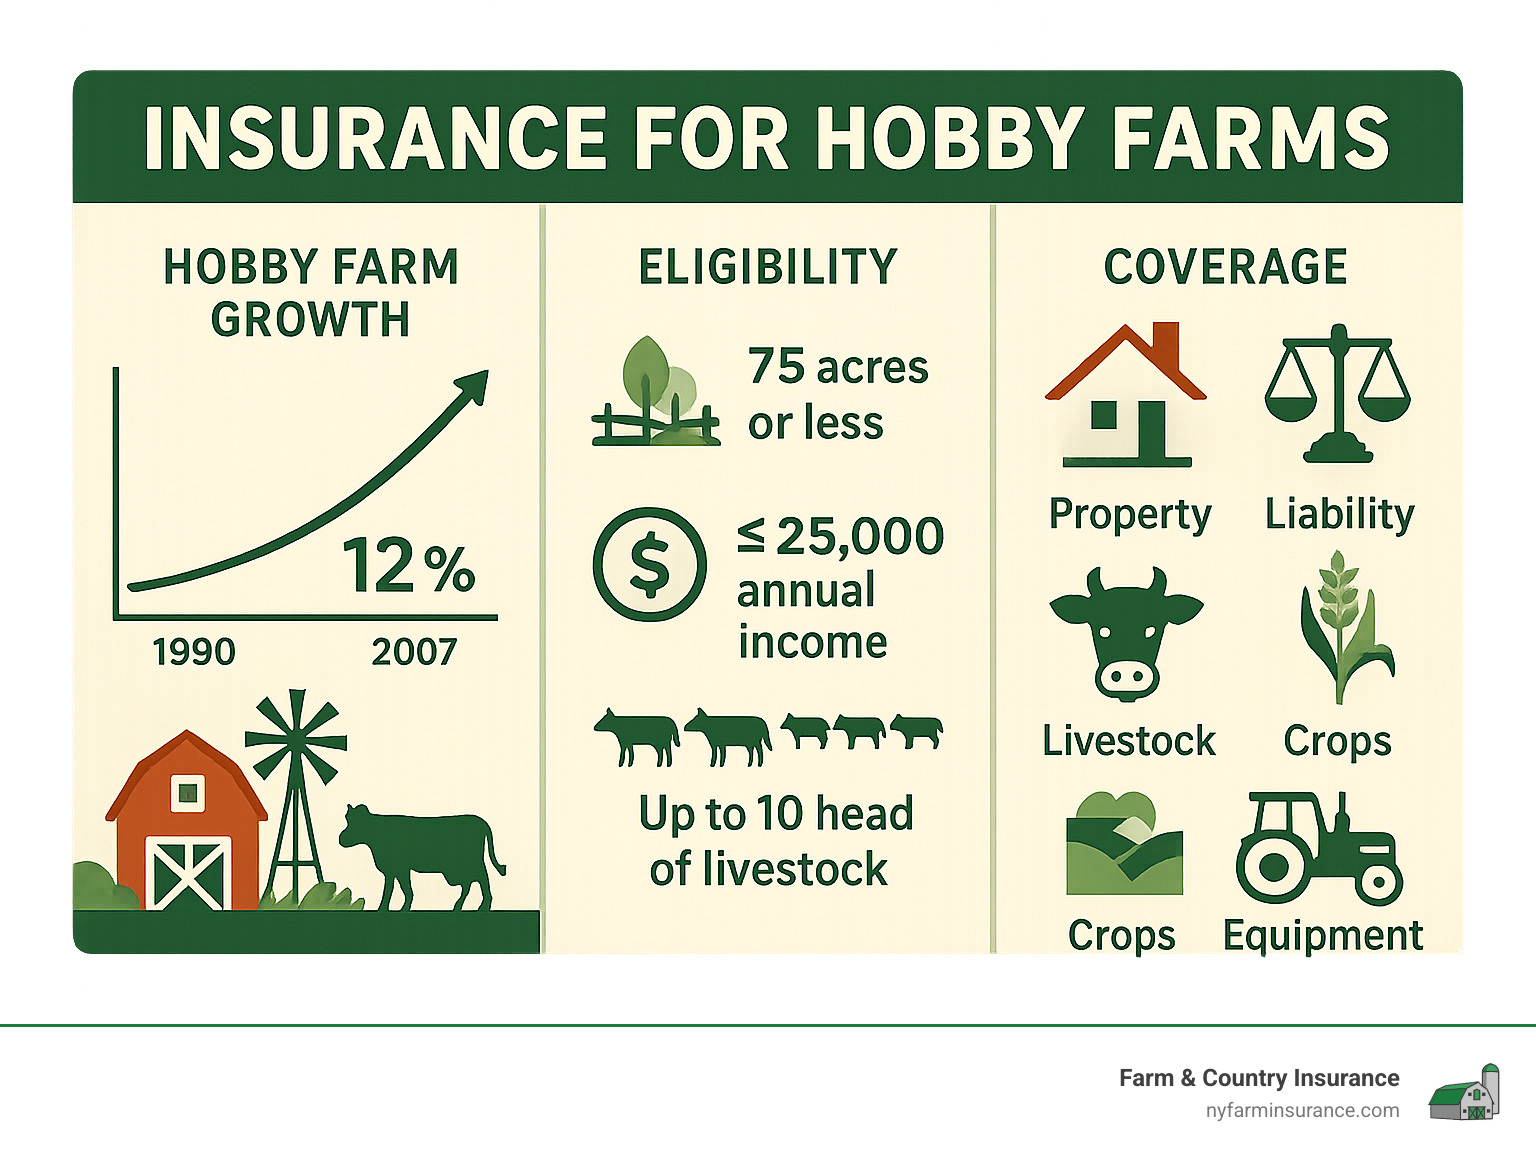
Insurance for hobby farms is specialized coverage for small-scale agricultural operations that are not your primary source of income. Unlike a standard homeowners policy, it protects your rural lifestyle and the unique risks of raising livestock, growing crops, and using farm equipment.
Key Components of Hobby Farm Insurance:
- Property Coverage: Protects your home, barns, outbuildings, and farm equipment
- Livestock Protection: Covers animals against injury, illness, or death
- Crop Coverage: Protects harvested crops and produce from weather damage and pests
- Liability Protection: Covers injuries to visitors and damages caused by your animals
- Product Liability: Protects you if someone gets sick from products you sell
- Farm Equipment: Covers tractors, tools, and machinery used in your operations
The popularity of hobby farming is significant, with these operations representing half of all farms as of 2007. They typically involve properties of 75 acres or less, generate annual farm income of $25,000 or less, and may include up to 10 head of livestock like cattle, sheep, goats, or horses.
Standard homeowners insurance is insufficient for a hobby farm. Most policies exclude business and farming activities, leaving you vulnerable to major financial losses from weather, animal accidents, or liability claims. Whether you’re selling eggs at a farmers market or simply enjoying your rural property, you need protection that understands your unique risks. At Farm & Country Insurance, we have spent decades helping farmers across New York State find the right insurance for hobby farms to fit their specific needs and budget, allowing them to focus on their passion without worrying about financial risks.
Why Your Homeowners Policy Falls Short
Many new hobby farmers assume their homeowners insurance will protect their new rural property, but this is a costly mistake. Standard homeowners policies were not designed for life with farming activities, creating dangerous coverage gaps that could leave you financially vulnerable.
The Limits of Standard Homeowners Insurance
When you begin any farming activities, even for personal enjoyment, your standard homeowners policy shows its limitations. These are serious gaps that could cost you thousands.


Business activity exclusions are a major trap. Most homeowners policies exclude coverage for “business pursuits” or “farming activities.” If you sell a few eggs or host an agritourism event, your insurer could deny a claim, eliminating both liability and property coverage.
Farming exclusions go beyond income. The simple act of farming introduces risks that standard policies don’t cover, failing to recognize the unique challenges of rural property ownership.
Limited property coverage is another issue. While your home is covered, farm structures like barns, greenhouses, or animal shelters are often excluded or given minimal coverage. If a storm damages your barn, your policy might offer little to no protection.
No coverage for farm equipment means your tractor isn’t protected. Homeowners policies cover household items, not specialized machinery like plows or cultivators.
Inadequate liability protection is perhaps the most dangerous gap. Standard liability covers a slip on your front steps, but not a visitor injured by an animal or someone getting sick from your produce. This leaves you exposed to potentially devastating lawsuits.
Failing to disclose all your activities, even with an incidental farming endorsement, can lead to denied claims. For more details, see our insights on Homeowners Insurance for Hobby Farms.
Key Differences: Standard Homeowners vs. Insurance for Hobby Farms
The contrast between standard homeowners and insurance for hobby farms is clear when compared side by side:
| Feature | Standard Homeowners Insurance | Insurance for Hobby Farms |
|---|---|---|
| Dwelling Coverage | Covers your primary residence and attached structures | Covers your primary residence with integrated farm-specific considerations |
| Outbuilding Coverage | Limited coverage for detached structures like sheds, typically excluding farm buildings | Comprehensive coverage for barns, greenhouses, animal shelters, silos, and other farm structures |
| Equipment Coverage | Covers personal lawnmowers and basic tools, but not farm machinery | Covers tractors, combines, plows, specialized farm equipment, and tools |
| Livestock Coverage | Generally no coverage for farm animals | Specific coverage for livestock against injury, illness, theft, or death |
| Liability | Personal liability for accidents not related to business or farm activities | Personal liability extended to farm operations, product liability, animal liability, and visitor injuries related to farming |
This comparison shows the fundamental difference: homeowners insurance is for suburban life, while hobby farm insurance understands your blend of personal and agricultural risks. Farm-specific risks like product liability or injuries from livestock are outside the scope of typical home insurance.
On a hobby farm, commercial versus personal risks are blurred. Selling eggs or hosting visitors are commercial activities. Standard policies draw a hard line between them, but hobby farm insurance recognizes your operation straddles both worlds.
The bottom line is clear: to protect your rural dreams, insurance for hobby farms is essential. At Farm & Country Insurance, we’ve helped New York farmers steer these unique challenges since 1984.
For more information, visit our page on Farm Homeowners Insurance.
What Does Hobby Farm Insurance Actually Cover?
Now that we know why standard homeowners insurance isn’t enough, let’s explore what insurance for hobby farms covers. This specialized policy is a comprehensive safety net for the unique blend of residential and agricultural elements on your property.
Protecting Your Property and Assets
Your hobby farm is a significant investment of time and money. Insurance for hobby farms protects your property far beyond a typical home, covering everything from your house to the structures that make farming possible.

- Your dwelling and personal property receive protection similar to a standard homeowners policy, but it’s integrated with your farming activities.
- Barns and outbuildings are where this insurance truly shines. Unlike standard policies, it treats barns, greenhouses, and workshops as essential parts of your operation, covering them against storm, fire, or other damage. Learn more about our Farm Building Insurance Policy.
- Fences are crucial for containing animals. Your policy can include coverage for the fencing that keeps your livestock safe.
- Farm machinery and equipment coverage protects your tractor, mower, tiller, and other tools against theft, vandalism, fire, and other perils. We know these tools are vital to your operation. See more at Farm Equipment Insurance Coverage.
- Harvested crops and produce can be protected against damage from pests, weather, or other unexpected events, safeguarding the fruits of your labor.
Coverage for Your Farming Activities
Insurance for hobby farms is designed to protect the diverse activities that make your farm unique.
- Livestock protection is crucial for your valuable and vulnerable animals. Whether you have chickens, goats, or horses, your policy can cover them against injury, illness, theft, and accidents. Find out more at How Much Does Livestock Insurance Cost?.
- Poultry, eggs, and beekeeping are popular hobbies. Your policy can offer specialized coverage for your birds, beehives, and the products they create.
- Roadside stands and farmers’ market sales turn your hobby into a small venture. Product liability coverage is essential here, protecting you from lawsuits if someone gets sick from your products.
- Agritourism activities like farm tours or pumpkin picking come with unique liabilities. Your policy can be custom to cover these risks when you welcome visitors.
- Crop insurance isn’t just for large operations. It can protect your valuable produce against storms, pests, or other factors. For more information, visit Crop Insurance for Farmers.
Essential Liability Protection
Liability protection is where insurance for hobby farms is most critical, as you take on risks beyond those of a typical homeowner.
- Farm premises liability extends personal liability to cover accidents related to your farming operations, such as a visitor tripping over equipment or getting injured in the barn.
- Product liability is vital if you sell anything from your farm, protecting you from claims related to the products you’ve grown or raised.
- Animal-related injuries are a real risk. If your goat headbutts a visitor or your chickens cause a fall, you’re protected from the financial responsibility.
- Visitor accidents can happen due to uneven terrain or unfamiliar equipment. Your liability coverage helps protect you when they do.
- Chemical drift liability provides protection if agricultural chemicals you use accidentally drift and cause damage to neighboring properties.
For a full overview, visit our Farm Liability Insurance page.
Common Exclusions and Limitations
It’s important to know what your policy doesn’t cover:
- Intentional acts of damage or injury are never covered.
- Normal wear and tear is not covered, as insurance is for sudden, unexpected losses.
- Damage from floods or earthquakes typically requires separate, specialized policies.
- Commercial-level operations with high income or full-time employees may require a commercial farm policy.
- Non-disclosed activities may not be covered. Transparency with your agent is crucial.
- Pollution liability is often excluded and usually requires specialized environmental insurance.
At Farm & Country Insurance, we encourage full transparency to ensure you have the right coverage to protect your rural dreams.
Getting Started with Insurance for Hobby Farms
Ready to protect your hobby farm? Getting started is straightforward. Let’s walk through the key questions: “Do I qualify?” and “What will it cost?”
Are You Eligible for a Hobby Farm Policy?
Hobby farm insurance is for people who love farming but don’t rely on it as their full-time career. Insurers have specific criteria to distinguish a hobby farm from a commercial operation.
Here’s what typically qualifies you for insurance for hobby farms:
- Your farm isn’t your main paycheck. Farming is primarily for enjoyment or supplemental income, not your primary living.
- You’re working with manageable acreage. Most policies are for properties of 75 acres or less.
- Your farm income stays within limits. Insurers often set annual income thresholds, typically $25,000 or less from farm activities.
- You keep your livestock numbers reasonable. A common guideline is up to 10 head of larger livestock like cattle, sheep, or horses.
- You’re not employing a full-time crew. Hobby farms generally don’t have a permanent, paid workforce.
- The property is your personal residence. Your farm is where you live, not just a place of business.
The IRS also has helpful guidelines for distinguishing a hobby from a business for tax purposes. You can review their IRS tips on determining if your farm is a hobby or a business.
If your operation has grown beyond these limits, we can help you explore Small Farm Business Insurance options.
What Factors Influence the Cost of Insurance for Hobby Farms?
The cost of insurance for hobby farms varies based on your unique situation. It’s typically more comprehensive and expensive than homeowners insurance but more affordable than a commercial policy.
Several key factors determine your premium:
- Property size and location: A larger property or one in a high-risk area (e.g., for severe weather) will cost more to insure.
- Type of farming activities: Raising chickens carries different risks than keeping horses or running a roadside stand.
- Value of your home and outbuildings: Higher-value structures cost more to insure.
- Your equipment and livestock values: The higher their replacement value, the more you’ll pay to cover them.
- Your chosen coverage limits: Higher limits provide more protection but increase your premium.
- Your deductible amount: A higher deductible lowers your premium but means you pay more out-of-pocket for a claim.
- Your claims history: A history of multiple claims can increase your premiums.
- Safety measures: Implementing safety protocols can sometimes earn you discounts.
At Farm & Country Insurance, we work with you to understand these factors and create a policy that fits your needs and budget, so you can focus on enjoying your farm.
How to Choose the Right Policy for Your Needs
Selecting the right insurance for hobby farms doesn’t have to be overwhelming. At Farm & Country Insurance, we’ve helped New York farmers make these decisions since 1984. The best policy is one that fits your farm’s unique personality and needs.
Assess Your Unique Risks and Needs
Before meeting with an agent, take a thorough inventory of your operation. This preparation leads to a more productive conversation and a better outcome.
- Inventory your assets. List everything you want to protect, including your home, barn, chicken coop, greenhouse, fencing, tractor, and even hand tools. Note the types and values of your animals.
- List all your activities. Do you sell eggs, host tours, or deliver produce? Even occasional activities matter, as they can impact your coverage needs.
- Consider your future plans. Are you thinking of adding more animals or starting an agritourism venture? Sharing your goals helps ensure your policy can grow with you.
- Evaluate potential liabilities. Think through worst-case scenarios. What if a visitor trips, an animal causes an injury, or a customer gets sick? This helps build a comprehensive safety net.
This self-assessment is the foundation for selecting the right Agriculture Insurance for your situation.
Questions to Ask Your Insurance Agent
An experienced agent who understands farming is a valuable partner. We encourage you to ask detailed questions to fully understand your policy.

- Are my liability limits sufficient for my activities?
- Is my equipment covered for replacement cost or actual cash value? Replacement cost pays for a new item, while actual cash value includes depreciation.
- What perils are my specific animals covered for?
- What endorsements do I need for unique activities like beekeeping or a roadside stand?
- How does my policy handle income from sales?
- What are the key exclusions and limitations?
- What risk management strategies could lower my premiums?
For more answers, browse our Farm Insurance FAQs page.
Customizing Your Coverage
Insurance for hobby farms is flexible. We can tailor your policy with options and endorsements to create protection that fits perfectly.
- Policy endorsements are add-ons for specific needs, like coverage for bee colonies or a farm vehicle used for deliveries.
- Umbrella policies provide an extra layer of liability protection ($1 million or more) beyond your standard limits, offering significant peace of mind for a modest cost.
- Bundling policies, such as combining your farm and auto insurance, often leads to discounts and simplifies management.
- Annual policy reviews are crucial. As your farm evolves, your insurance needs change. We recommend an annual review to ensure your coverage keeps pace with your dreams.
By taking these steps, you can ensure your insurance for hobby farms is as comprehensive as your rural lifestyle. For more guidance, explore our insights on Best Hobby Farm Insurance.
Conclusion
Your hobby farm is more than a lifestyle—it’s a dream realized and a significant investment. Protecting it requires more than a standard homeowners policy.
Homeowners insurance is not enough. Its exclusions for business and farming activities can leave you exposed when you need protection most. Standard policies are not designed to handle the realities of a rural property with livestock, equipment, and visitors.
Specialized coverage protects your passion and investment. Insurance for hobby farms understands that your property is a working farm. It bridges the gap between residential and commercial insurance, providing protection that fits your actual life.
Proper hobby farm insurance protects your buildings, equipment, and livestock while also covering the liability risks from selling products or welcoming visitors. This allows you to focus on what you love—tending your land and animals—without the constant worry of financial catastrophe.
Proactive risk management is key. Working with an experienced agent who knows farming helps you make informed decisions about coverage and safety measures that protect both your family and your budget.
For New York farmers seeking a policy that understands their unique challenges, the experts at Farm & Country Insurance can help. Since 1984, we’ve specialized in custom farm insurance solutions, offering comprehensive coverage rooted in a deep understanding of the industry’s risks. We know every farm is different, and we’re here to protect your small acreage and your big dreams.
Your hobby farm deserves protection that works as hard as you do. Find the right insurance for your small farm with Farm & Country Insurance today, and get the peace of mind to truly enjoy your rural lifestyle.