
Protecting Your Prairie: Understanding Land Insurance
Land insurance is a specialized type of coverage designed to protect landowners from financial risks associated with their property, especially undeveloped or vacant land. It primarily safeguards against:
- Liability claims: If someone gets injured on your land or their property is damaged. This covers medical expenses, legal fees, and settlements.
- Unexpected incidents: Even on empty land, accidents can happen, leading to costly lawsuits. The average claim for bodily injury and property damage from 2014 to 2018 was over $26,870.
- Financial protection: Prevents potential financial burdens and stress from unforeseen events on your property.
Owning land, whether it’s a vast prairie or a smaller vacant lot, comes with unique responsibilities. While you might think empty land poses little risk, unexpected events can quickly turn into major financial burdens. Having the right coverage is a crucial safety net, providing peace of mind by protecting your investment from unforeseen incidents and potential lawsuits.
As Casey Love, owner of Farm & Country Insurance, I specialize in helping farmers like you steer the complexities of land insurance. Our goal is to provide custom solutions that protect your livelihood, assets, and legacy.

Land insurance definitions:
The Foundation: What is Land Insurance and Why is it Essential?
At Farm & Country Insurance, we often hear folks wonder, “It’s just land, why do I need to insure it?” It’s a fair question! But the truth is, owning land, even if it’s undeveloped, comes with some big responsibilities and potential risks. Land insurance, often called vacant land insurance, is a smart way to manage these risks. Think of it as a crucial safety net for your property.
Its main job is to protect you from what we call “premises liability.” This simply means the legal duty landowners have to make sure their property is safe for anyone who might set foot on it. This coverage is super important because it shields your valuable land investments from costly claims if someone gets hurt or their property is damaged on your land.
Imagine this: an unexpected guest, or even a trespasser, suffers an injury while on your property. Without land insurance, you could be personally on the hook for their medical bills, legal fees, and any settlements. Those costs can add up fast! From 2014 to 2018, the average claim for bodily injury and property damage was over $26,870. That kind of bill could really shake up your financial plans. Here at Farm & Country Insurance, our goal is to give you peace of mind with strong protection against these unexpected events.

Want to learn more about how insurance protects your agricultural interests? Check out our article on Agriculture Insurance.
What Types of Land Can Be Insured?
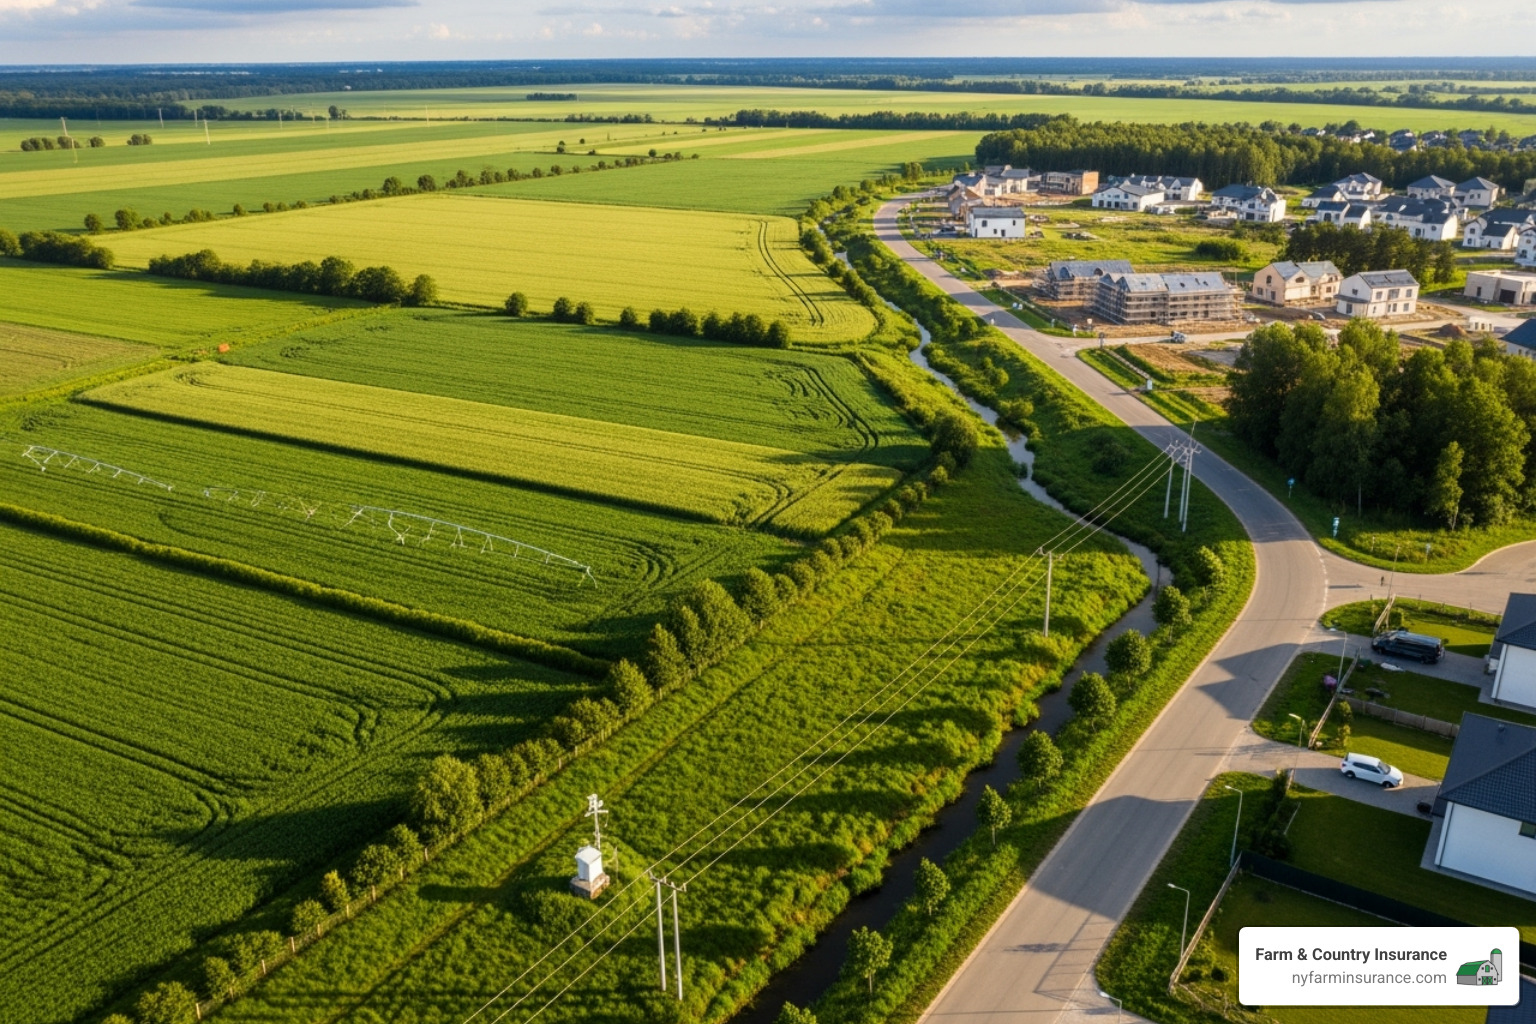
One of the great things about land insurance is how flexible it is. We can help you find coverage for almost any kind of undeveloped property. Whether it’s a sprawling piece of rural acreage in Cayuga County, New York, or a smaller vacant lot in one of our local towns like Auburn or Moravia, we’ve got you covered.
Here’s a look at the different types of land we can typically insure:
- Vacant Land: This is the most common kind, referring to any property that doesn’t have permanent buildings on it.
- Undeveloped Properties: Land you’ve bought with plans for future development, like a spot for your dream home or an investment property, before any construction begins.
- Agricultural Land: This includes pastures, ranges, and grasslands. Even if they’re not actively farmed, they still need liability protection. This is especially important for our New York farm clients.
- Recreational Land: Properties that folks use for private hunting, fishing, camping, or even ATV riding.
- Woodlands: Timberland or forested areas.
- Commercial Land: Empty plots set aside for future commercial buildings.
- Residential Land: Undeveloped plots in residential neighborhoods.
Even land that has natural features like bluffs, cliffs, or water bodies (think ponds or creeks) can often be insured. While these features might increase the chance of an accident, we can work with you to find a policy that fits, as long as you let us know about them upfront.
The Importance of Land Insurance for Undeveloped Land
It’s easy to think, “If there are no buildings, there’s no risk.” But that’s not quite true! Even undeveloped land comes with ongoing liability risks. For example, trespassers can sometimes still hold landowners responsible for injuries they get on your property, even if they weren’t invited. This is a common misunderstanding; the law often holds landowners accountable for making sure their property is reasonably safe for anyone who enters it, whether invited or not.
Unexpected events are precisely why land insurance is so vital. Imagine a hidden hole, a fallen tree branch, or even an old, crumbling structure. Any of these could lead to a slip and fall, resulting in big medical expenses and potential lawsuits. Even if you’re not planning to develop your land anytime soon, having land insurance protects your investment from these unforeseen incidents.
Beyond just protecting you from immediate liability, land insurance can also be helpful if you plan to develop the land later. Having your vacant land insured can even make the permitting process smoother when you decide to build. Plus, a history of land insurance might make getting homeowner’s insurance easier and potentially more affordable once you construct a dwelling. It’s an affordable way to protect your assets and gives you peace of mind, knowing your land is covered against those unexpected surprises.
For more detailed information, explore our article on Agricultural Land Insurance.
Understanding Your Policy: What Land Insurance Covers (and What It Doesn’t)
Navigating insurance policies can feel like reading a foreign language. At Farm & Country Insurance, we believe in making it simple and clear. When it comes to land insurance, understanding the scope of your policy – what it covers, its limits, and any endorsements – is crucial. We’ll help you decipher the jargon so you know exactly what protection you have.
More info about Farm and Ranch Insurance Coverage
What Land Insurance Typically Covers
The primary purpose of land insurance is liability protection. This means it’s designed to protect you, the landowner, from financial loss if someone is injured or their property is damaged on your land, and you are found legally responsible.
Here’s what land insurance typically covers:
- Bodily Injury Claims: If a third party, whether an invited guest or an uninvited trespasser, suffers an injury on your land (e.g., a slip and fall, an injury from rough terrain), the policy can cover their medical expenses.
- Property Damage Claims: If your land causes damage to a neighbor’s property (e.g., a dead tree on your property falls and damages their fence or shed, or debris from your land causes damage during a storm), the policy can cover the repair costs.
- Legal Defense Costs: If a lawsuit arises from an incident on your land, your policy will typically cover the costs of your legal defense, regardless of whether you are found liable. This can include attorney fees, court fees, and settlements.
Liability Coverage Limits and Typical Use Cases
| Coverage Limit (Per Occurrence / Annual Aggregate) | Typical Monthly Cost (approx.) | Common Use Cases “`
Prairie Protection: What You Need to Know About Insuring Your Land
Protecting Your Prairie: Understanding Land Insurance
Land insurance is a specialized type of coverage designed to protect landowners from financial risks associated with their property, especially undeveloped or vacant land. It primarily safeguards against:
- Liability claims: If someone gets injured on your land or their property is damaged. This covers medical expenses, legal fees, and settlements.
- Unexpected incidents: Even on empty land, accidents can happen, leading to costly lawsuits. The average claim for bodily injury and property damage from 2014 to 2018 was over $26,870.
- Financial protection: Prevents potential financial burdens and stress from unforeseen events on your property.
Owning land, whether it’s a vast prairie or a smaller vacant lot, comes with unique responsibilities. While you might think empty land poses little risk, unexpected events can quickly turn into major financial burdens. Having the right coverage is a crucial safety net, providing peace of mind by protecting your investment from unforeseen incidents and potential lawsuits.
As Casey Love, owner of Farm & Country Insurance, I specialize in helping farmers like you steer the complexities of land insurance. Our goal is to provide custom solutions that protect your livelihood, assets, and legacy.
Land insurance definitions:
The Foundation: What is Land Insurance and Why is it Essential?
At Farm & Country Insurance, we often hear, “It’s just land, why do I need to insure it?” It’s a fair question! Many folks think that if there’s no house or barn on it, there’s no real risk. But the truth is, owning land, even if it’s undeveloped, comes with significant responsibilities and potential liabilities you might not expect.
Land insurance, often called vacant land insurance, is a critical tool for any landowner. Think of it as a crucial safety net that protects your financial well-being. Its main job is to shield you from something called premises liability. This is simply your legal responsibility to make sure your property is safe for anyone who might enter it, whether they’re invited or not. This coverage is absolutely essential because it protects your valuable land investment from costly claims if someone gets hurt or their property is damaged on your land.
Imagine this: an unexpected visitor, or even a trespasser, suffers an injury while on your property. Without land insurance, you could find yourself personally responsible for their medical bills, legal fees, and any settlements. Those costs can add up fast! For example, the average claim for bodily injury and property damage between 2014 and 2018 was over $26,870. That’s a sum that could easily disrupt your financial stability and cause a whole lot of stress. Our main goal at Farm & Country Insurance is to ensure you have true peace of mind by providing robust protection against these unexpected incidents.
Want to learn more about how insurance helps protect agriculture? We’ve got more information right here: More info about Agriculture Insurance
What Types of Land Can Be Insured?
The great thing about land insurance is how versatile it is! We can help you find coverage for almost any type of undeveloped property you might own. Maybe you have sprawling rural acreage in a beautiful area like Cayuga County, New York, or perhaps a smaller vacant lot right within one of our local towns, such as Auburn or Moravia.
No matter the size or location, if it’s undeveloped, chances are we can help you protect it. This includes common types like vacant land (any property without permanent structures) and undeveloped properties you’re holding onto for future plans, like a dream home site or a smart investment before construction begins.
For our New York farm clients, we can also insure agricultural land, like pastures, ranges, and woodlands, even if they aren’t actively farmed. This is especially important for dairy, grain, fruit, and vegetable farms. If you have recreational land used for private hunting, fishing, camping, or ATV riding, we can cover that too. We also assist with commercial land (empty plots for future business buildings) and residential land (undeveloped plots in neighborhood areas).
Even land with natural features like bluffs, cliffs, or water bodies (think ponds or creeks) can typically be insured. While these features might increase the chance of an accident, we’ll work closely with you to find a policy that accounts for them, as long as they’re fully disclosed upfront.
The Importance of Land Insurance for Undeveloped Land
It’s easy to assume that because there are no buildings, there’s no risk. But that’s a common misconception! Undeveloped land still carries ongoing liability risks. For example, trespassers can still hold landowners responsible for injuries they suffer on your property, even if they weren’t invited. The law often holds landowners accountable for ensuring the safety of anyone who enters their property, invited or not. It’s a surprising fact, but true!
Unexpected events are precisely why land insurance is so vital. Imagine a dead tree branch suddenly falling and injuring someone, or a hidden hole causing a serious slip and fall. Even an old, dilapidated structure on your property could lead to significant medical expenses and potential lawsuits. Even if you don’t plan to develop your land anytime soon, having land insurance protects your investment from these kinds of unforeseen events. It truly offers invaluable peace of mind.
Beyond just immediate liability protection, land insurance also offers benefits if you plan to develop your property in the future. Having your vacant land insured can actually simplify the permitting process when you decide to build. Plus, a history of land insurance can make it smoother and potentially more affordable to get homeowner’s insurance once you construct a dwelling. It’s an affordable protection measure that truly safeguards your assets and provides peace of mind, knowing your land is covered against whatever unexpected incidents might come its way.
For more details specific to farm properties, check out: More info about Agricultural Land Insurance
Understanding Your Policy: What Land Insurance Covers (and What It Doesn’t)
Navigating insurance policies can feel like reading a foreign language. At Farm & Country Insurance, we believe in making it simple and clear. When it comes to land insurance, understanding the scope of your policy – what it covers, its limits, and any endorsements – is crucial. We’ll help you decipher the jargon so you know exactly what protection you have.
For an impartial overview of the legal concept that often comes into play with liability claims, take a look at this explanation of premises liability.
More info about Farm and Ranch Insurance Coverage
What Land Insurance Typically Covers
The primary purpose of land insurance is liability protection. This means it’s designed to protect you, the landowner, from financial loss if someone is injured or their property is damaged on your land, and you are found legally responsible.
Here’s what land insurance typically covers:
- Bodily Injury Claims: If a third party, whether an invited guest or an uninvited trespasser, suffers an injury on your land (e.g., a slip and fall, an injury from rough terrain, or a drowning incident on waterfront property), the policy can cover their medical expenses.
- Property Damage Claims: If your land causes damage to a neighbor’s property (e.g., a dead tree on your property falls and damages their fence or shed, or strong winds send debris from your land flying into their yard), the policy can cover the repair costs.
- Legal Defense Costs: If a lawsuit arises from an incident on your land, your policy will typically cover the costs of your legal defense, regardless of whether you are found liable. This can include attorney fees, court fees, and settlements.
Liability Coverage Limits and Typical Use Cases
| Coverage Limit (Per Occurrence / Annual Aggregate) | Typical Monthly Cost (approx.) | Common Use Cases