Why Protecting Your Farm Animals is Critical for Your Operation
Livestock insurance near me searches have surged as farmers recognize that their animals represent significant financial investments that need protection. Whether you’re raising cattle, horses, swine, or poultry, a single catastrophic event could wipe out years of hard work and breeding programs.
Quick Answer: How to Find Livestock Insurance Near You
• Use the USDA Agent Locator at public-rma.usda.gov to find authorized livestock insurance agents
• Contact specialized farm insurers that focus on agricultural operations
• Check with local co-ops and agricultural lenders for agent referrals
• Ask county extension offices for insurance provider recommendations
• Search online using zip code tools to locate specialized livestock agents
Your livestock face constant risks – from natural disasters like fires and floods to theft, disease outbreaks, and transportation accidents. Standard farm policies often provide limited livestock coverage, leaving dangerous gaps that could threaten your operation’s survival.
The good news? Specialized livestock insurance can protect against these perils through individual animal policies, blanket coverage, or herd protection plans. You can also access federal programs like Livestock Risk Protection (LRP) and Livestock Gross Margin (LGM) that guard against market price volatility and feed cost spikes.
I’m Casey Love, owner of Farm & Country Insurance, and I’ve spent years helping New York farmers find the right livestock insurance near me solutions for their unique operations. My experience working exclusively with agricultural insurance has shown me how critical proper livestock coverage is for protecting both individual animals and entire farming legacies.
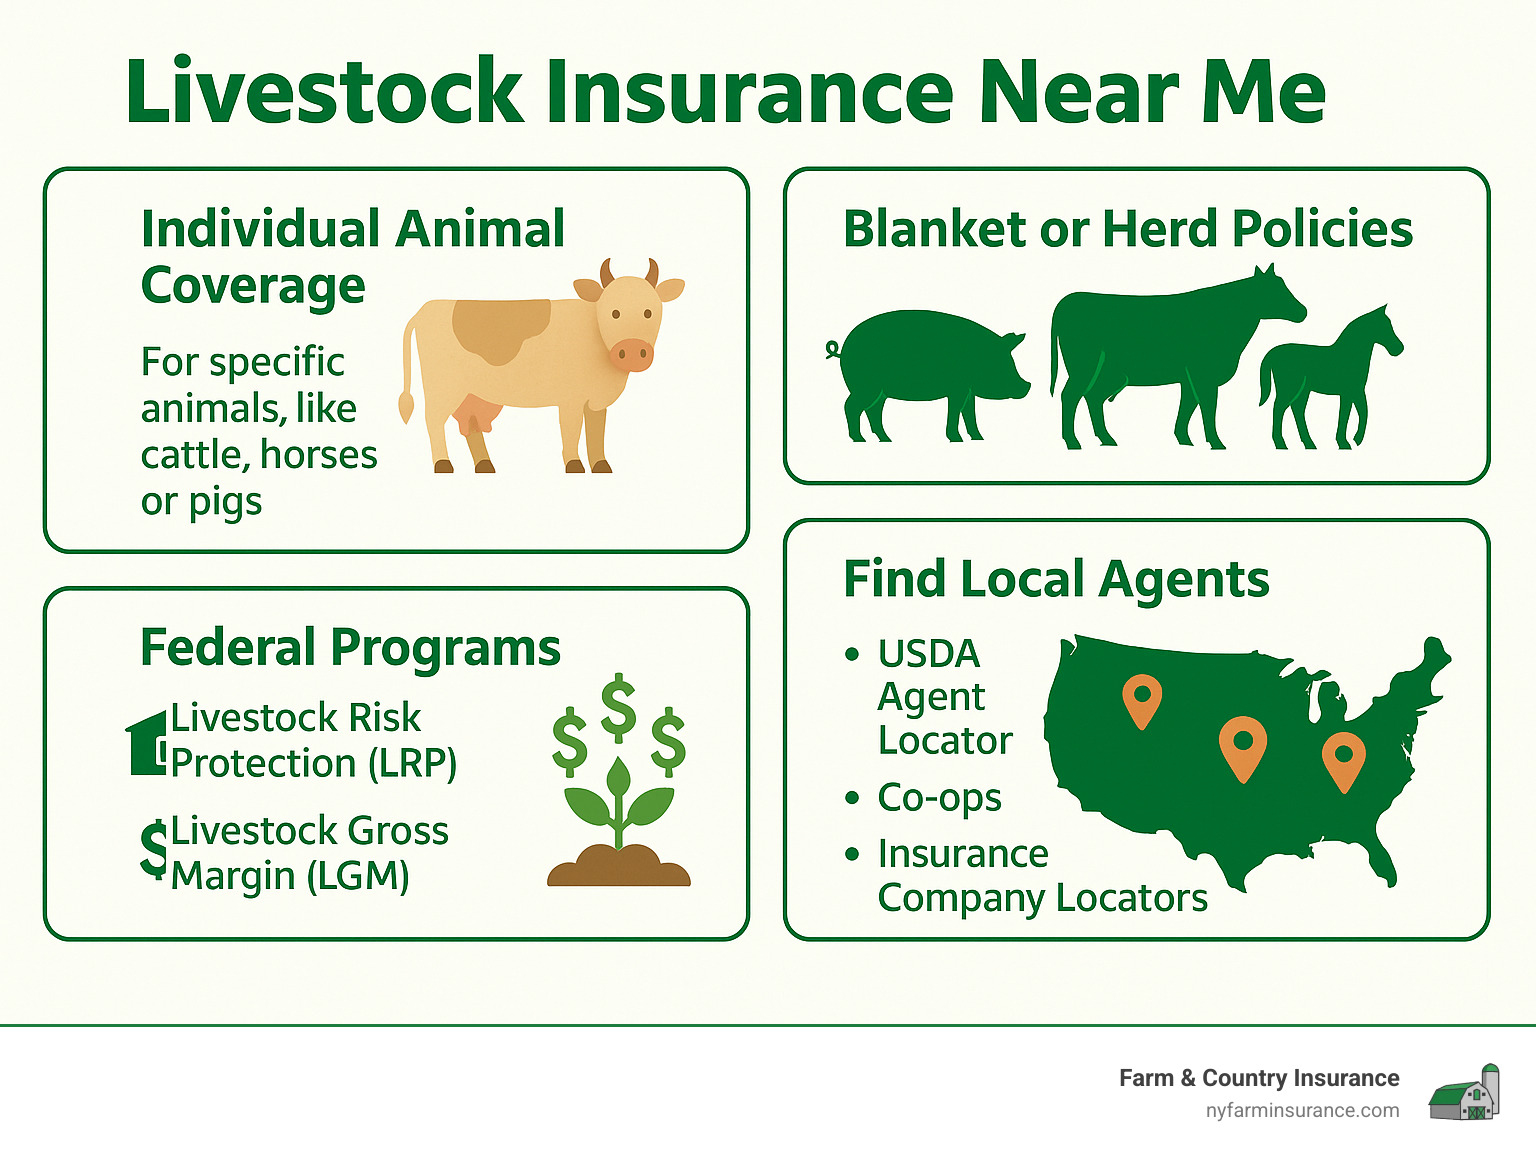
Livestock insurance near me terms made easy:
– Crop and livestock insurance
– Farm insurance near me
Why Every Producer Needs Livestock Coverage
Your animals represent far more than livestock – they’re living, breathing investments that can be worth tens or even hundreds of thousands of dollars. At Farm & Country Insurance, we’ve watched too many farmers learn this lesson the hard way when disaster strikes without proper coverage.

Fire and weather events cause the most heartbreaking claims we handle. A single barn fire can kill dozens of animals in minutes, while severe storms, floods, and lightning strikes devastate outdoor herds with little warning. Just last year, we processed a claim where one lightning strike killed an entire group of prize cattle sheltering under trees during a storm – a $150,000 loss that happened in seconds.
Theft and vandalism might sound unlikely, but they’re growing problems across rural America. High-value animals like show cattle and registered horses make tempting targets, especially on remote properties with limited security. We’ve also seen cases where vandals poisoned water supplies or damaged facilities, leading to animal deaths that could have been prevented with proper coverage.
When your animals cause problems, liability exposure can be devastating. If your cattle break through a fence and cause a highway accident, or if someone gets injured visiting your farm, you could face lawsuits that threaten your entire operation. Livestock insurance near me searches often spike after local incidents remind farmers how quickly liability claims can spiral out of control.
Revenue volatility keeps many producers awake at night, and for good reason. Market prices can swing wildly due to factors completely outside your control – drought, trade disputes, or disease outbreaks in other regions. Federal programs like Livestock Risk Protection and Livestock Gross Margin help cushion these blows by protecting against price declines and feed cost spikes.
For multi-generation farms, succession planning requires protecting valuable genetics and breeding stock. Losing key animals can set back carefully planned breeding programs by years and significantly reduce your farm’s value when it’s time to pass it to the next generation.
Regulatory compliance adds another layer of complexity. Proper insurance coverage often requires maintaining detailed veterinary records and following specific animal care protocols – documentation that helps you stay compliant with evolving animal welfare regulations.
The Hidden Costs of Uninsured Losses
The sticker price of a lost animal is just the beginning. Uninsured livestock losses create ripple effects that can sink operations already running on tight margins.
Market price timing can make a bad situation catastrophic. Losing animals during peak pricing seasons means missing your best selling opportunities of the year. We’ve seen cattle operations lose over $200,000 when fires killed animals just as beef prices hit seasonal highs.
Emergency veterinary bills pile up fast during disease outbreaks or mass injuries. Between emergency calls, medications, and intensive treatments, costs can easily hit $50,000 before you even calculate the value of animals you might still lose.
Cleanup and disposal costs catch many farmers off guard. Proper carcass disposal, environmental cleanup, and facility repairs typically run $10,000 to $30,000 per incident. Some areas require expensive rendering services or special burial permits that add thousands more to your bill.
Perhaps most painful are lost genetics in breeding operations. When you lose a proven bull or champion mare, you’re not just losing that animal’s value – you’re losing years of genetic progress and future income potential that can’t be easily replaced at any price.
Policy Options & Coverage Explained
Understanding your coverage options helps you choose the right protection level for your operation. We offer three main policy structures, each suited to different farming operations.
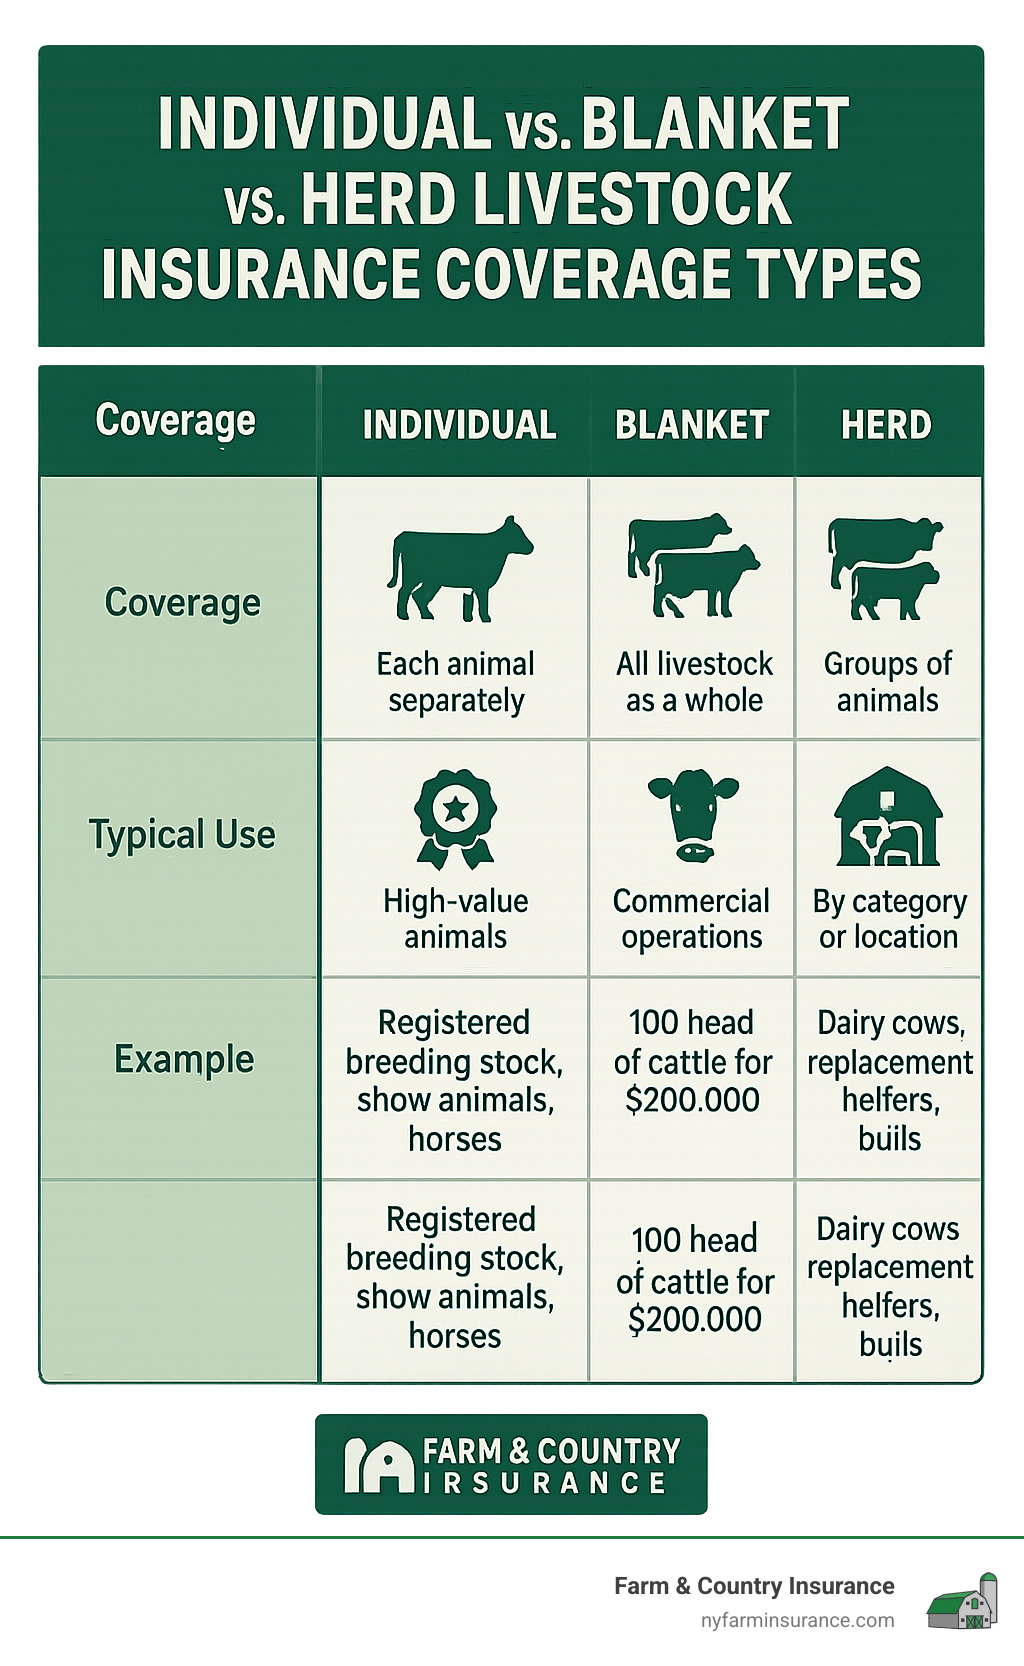
Individual coverage lists each animal separately with specific values. This works best for high-value animals like registered breeding stock, show animals, or horses where each animal has unique worth. You’ll provide detailed descriptions including tag numbers, names, and individual values.
Blanket coverage combines all livestock under one total sum insured. This approach works well for commercial operations with similar-value animals. For example, you might insure 100 head of Holstein cattle for $200,000 total coverage.
Herd coverage protects groups of animals by category or location. You might have separate herd policies for dairy cows, replacement heifers, and bulls, each with appropriate coverage limits.
Mortality insurance covers death from accident, illness, disease, or necessary destruction. This comprehensive coverage includes veterinary bills and provides the broadest protection but costs more than standard policies.
Federal programs like LRP and LGM protect against market risks rather than physical loss. These subsidized programs help manage price volatility and feed cost fluctuations.
Transit coverage protects animals during transportation. Whether you’re moving animals to market, shows, or new facilities, transit coverage handles accidents, collisions, and loading/unloading injuries.
Care, custody, and control coverage protects non-owned animals on your property. This matters for boarding operations, training facilities, or when you’re caring for neighbors’ animals.
Endorsements add specialized coverage for unique risks like suffocation, power outages, or contaminated feed. These optional coverages address specific perils common to certain livestock types.
What Standard Policies Cover
Standard livestock policies typically cover sudden, accidental losses from external causes. Understanding what’s included helps you evaluate whether basic coverage meets your needs.
Accidental shooting coverage applies when hunters or others accidentally shoot your livestock. This surprisingly common claim often involves deer hunters mistaking cattle for wildlife in wooded areas.
Electrocution from faulty wiring, lightning strikes, or contact with power lines triggers coverage. We’ve handled claims where entire herds died from electrical accidents during storms.
Dog and wild animal attacks cause significant losses, especially for sheep and poultry operations. Coverage typically excludes attacks on sheep by dogs but covers other livestock and wild animal attacks on all species.
Loading and unloading accidents occur frequently during transportation. Animals can be injured or killed when trailers overturn, ramps collapse, or handling equipment fails.
Flood and wind damage from severe weather events qualify for coverage. This includes animals drowned in floods or killed by flying debris during storms.
More info about coverage details specific perils and policy language that affects your claims.
What They Don’t Cover & How to Fill the Gaps
Standard policies exclude certain losses that require specialized coverage or management strategies.
Disease and illness exclusions eliminate coverage for deaths from sickness, infections, or health problems. Mortality insurance fills this gap but costs significantly more than standard coverage.
Old age and natural causes don’t qualify for standard coverage. Animals dying from age-related conditions or natural deaths aren’t covered unless you purchase mortality insurance.
Infertility and breeding problems require specialized coverage. Losing breeding capacity in valuable animals can devastate operations, but standard policies don’t cover reproductive failures.
Loss of use coverage protects against temporary disabilities that prevent animals from performing their intended functions. A injured racehorse or breeding bull might survive but lose their earning capacity.
More info about exclusions explains policy limitations and available solutions for excluded perils.
Finding Livestock Insurance Near Me
Finding the right livestock insurance near me can feel overwhelming, but knowing where to start makes all the difference. Not every insurance agent understands the unique challenges farmers face or offers proper livestock coverage.
Local agents with farm experience provide the best service because they truly understand your operation. They know local risks like flooding patterns, common diseases in your area, and seasonal challenges that affect livestock. At Farm & Country Insurance, we’ve been working exclusively with New York farmers since 1984, giving us deep insight into what works and what doesn’t when protecting farm animals.
The USDA RMA tools offer your best starting point for finding qualified agents. The Risk Management Agency maintains official listings of agents authorized to sell livestock policies nationwide. This isn’t just a marketing database – these agents have proper licensing and training to handle agricultural insurance.
Your county extension office can be a goldmine for recommendations. Extension agents work with farmers daily and know which insurance professionals understand livestock operations. They’ve seen which agents respond quickly during emergencies and which ones truly support the farming community.
Don’t overlook your agricultural lender when searching for insurance options. Farm lenders work closely with insurance agents to protect their investments, so they know which agents understand livestock financing and can structure coverage that meets lending requirements.
Cooperatives often maintain relationships with trusted insurance providers who work extensively with their members. Co-op managers understand local farming conditions and can suggest agents who offer appropriate coverage levels for your type of operation.
The official Find local insurance agents tool through USDA provides the most comprehensive search for authorized livestock insurance providers in your specific area.
Mapping tools from insurance companies help you visualize which agents serve your area and how far you might need to travel for face-to-face meetings. This matters when you need quick claim service or want to discuss coverage changes.
Using Online Tools to Locate Livestock insurance near me
Digital tools can save you hours when searching for qualified livestock insurance near me agents, but knowing how to use them effectively makes the difference.
Zip code searches give you the fastest results on most insurance company websites. Simply enter your zip code and you’ll see nearby agents with their contact information and office locations. This works great for getting a quick overview of your options.
Agent locator filters help you narrow down results to find specialists. Look for filters that identify livestock experts, farm insurance specialists, or agents with agricultural designations. This saves time by eliminating agents who might not understand your specific needs.
Specialty designations indicate agents with advanced agricultural training. Agents with credentials like Whole Farm Risk Plan (WFRP) certification or specialized livestock training have invested extra time learning about farm insurance complexities.
The USDA site lets you download comprehensive lists of authorized agents by state and county. These Excel or PDF files provide complete contact information for offline reference, which helps when you’re comparing multiple agents or want to keep records organized.
Talking to Local Co-ops About Livestock insurance near me
Agricultural cooperatives provide some of the most valuable resources for finding reliable livestock insurance near me options through their networks and member experiences.
Peer referrals from fellow farmers give you honest, real-world assessments of agent performance. Co-op members freely share their experiences about claims handling, coverage adequacy, and how responsive agents are during critical situations. These insights prove invaluable when choosing someone to protect your livelihood.
Co-ops frequently host producer meetings that include insurance education sessions. These workshops provide opportunities to hear agents explain coverage options and ask questions about livestock protection strategies. You’ll often learn about coverage gaps you didn’t know existed.
County fairs bring together agricultural service providers in a relaxed setting where you can compare options without pressure. Fair exhibitions let you meet multiple agents, ask questions, and gather information to review later. Many agents use fairs to showcase new coverage options or explain changes in federal programs.
The conversations you have at co-ops often reveal which agents truly understand farming versus those who just sell policies. Members will tell you which agents visit farms personally, respond quickly to claims, and fight for fair settlements when losses occur.
Customizing & Comparing Quotes
Getting accurate livestock insurance quotes requires detailed information about your animals, operation, and coverage needs. Proper preparation ensures you receive appropriate coverage recommendations.
Animal values form the foundation of your coverage. Document purchase prices, breeding records, performance data, and market values for accurate insurance amounts. High-value animals may require appraisals or veterinary statements.
Deductible levels significantly impact premiums. Higher deductibles reduce costs but increase out-of-pocket expenses during claims. Consider your cash flow and risk tolerance when selecting deductible amounts.
Coverage limits should reflect your total exposure. Underinsuring saves premium dollars but leaves you vulnerable to catastrophic losses. Overinsuring wastes money on unnecessary coverage.
Newly-acquired livestock need immediate protection. Most policies provide automatic coverage for new animals for 30-60 days, but you must report additions promptly to maintain coverage.
Non-owned animals on your property require special attention. Boarding, training, or caring for others’ animals creates liability exposures that standard coverage might exclude.
Loss-of-income riders protect against business interruption. If livestock losses prevent you from operating normally, these endorsements cover lost profits and ongoing expenses.
More info about cost factors explains how premiums are calculated and what influences your insurance costs.
Leveraging Federal Risk Programs
Federal livestock insurance programs provide subsidized protection against market risks that private insurance doesn’t cover.
Livestock Risk Protection (LRP) guards against declining market prices. You select coverage levels and insurance periods that match your feeding and marketing schedule. LRP uses futures prices to establish coverage levels and calculate payments.
Livestock Gross Margin (LGM) protects the difference between livestock values and feed costs. This program helps stabilize profit margins when feed prices spike or livestock prices drop simultaneously.
Dairy Revenue Protection (DRP) covers quarterly milk revenue against unexpected declines. You can choose coverage levels and pricing options that reflect your farm’s risk profile and production patterns.
Premium subsidies make federal programs affordable. The government pays 13-35% of premiums depending on coverage levels, making these programs cost-effective risk management tools.
CME pricing ensures transparent, market-based coverage. Federal programs use Chicago Mercantile Exchange futures prices to calculate expected values and determine payment amounts.
Scientific research on price risk provides data and analysis tools for understanding market volatility and program benefits.
Adding Specialized Endorsements
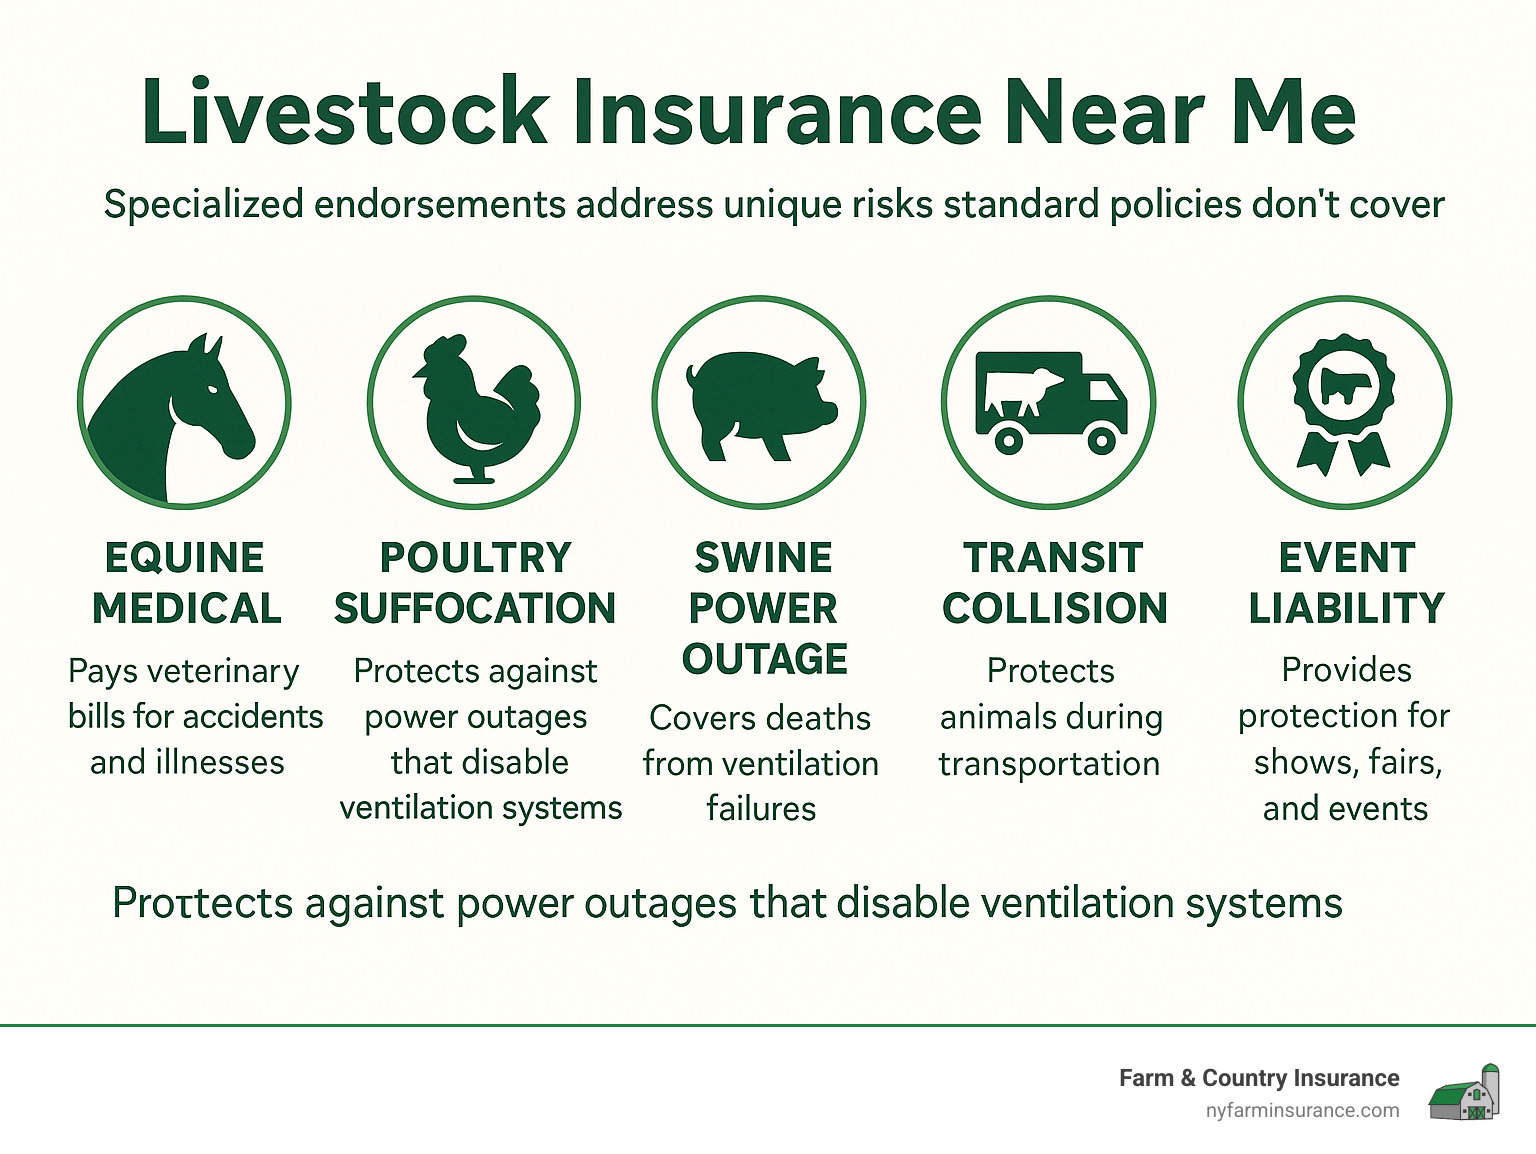
Specialized endorsements address unique risks that standard policies don’t cover, allowing you to customize protection for your specific operation.
Equine medical coverage pays veterinary bills for covered accidents and illnesses. This valuable endorsement can cover thousands of dollars in emergency veterinary care for injured horses.
Poultry suffocation coverage protects against power outages that disable ventilation systems. Confined poultry operations face catastrophic losses when environmental controls fail during extreme weather.
Swine power outage endorsements cover deaths from ventilation failures. Modern swine facilities depend on electrical systems for air circulation, heating, and cooling that become deadly when interrupted.
Transit collision coverage protects animals during transportation. This endorsement covers accidents, overturns, and other transportation-related losses that occur away from your property.
Event liability coverage protects when you take animals to shows, fairs, or other events. This specialized liability covers accidents and injuries that occur at off-premises events.
More info about risk protection details federal programs and private coverage options for managing livestock risks.
Frequently Asked Questions About Local Livestock Coverage
When farmers start researching livestock insurance near me, they often have similar questions about how coverage actually works in practice. At Farm & Country Insurance, we’ve answered these questions countless times over our decades of serving New York farmers.
The most common concerns revolve around automatic extensions for new animals, claim timelines when disaster strikes, and coverage for newly purchased animals. Understanding these basics helps you feel confident about your protection and know what to expect if you ever need to file a claim.
Most policies include thoughtful features like automatic coverage for animals you buy throughout the year. This means you’re not scrambling to call your agent every time you purchase replacement heifers or add breeding stock to your operation.
Claim timelines vary based on the type of loss and how well you’ve documented everything. A straightforward lightning strike that kills several cattle might settle quickly, while more complex situations requiring veterinary investigations naturally take longer to resolve.
The key is knowing what your policy covers and having realistic expectations about the claims process. Newly purchased animals typically receive immediate protection, but there are specific rules about reporting timeframes that you’ll want to understand upfront.
How do claims work after a sudden loss?
Nobody wants to think about losing valuable animals, but understanding the claims process ahead of time makes a traumatic situation much more manageable.
Documentation becomes your best friend during claims. Take photos immediately when you find losses – before moving anything or cleaning up. These pictures help adjusters understand what happened and speed up your claim settlement.
Keep detailed veterinary records throughout the year, not just during emergencies. When adjusters review claims, they look at vaccination records, health certificates, and treatment histories to verify proper animal care and rule out excluded conditions.
Adjuster visits typically happen within 24-48 hours for livestock losses. Our adjusters understand farming operations and work around your schedule when possible. They’ll examine the animals, review your records, and explain the next steps in plain language.
The most important thing? Don’t dispose of carcasses until your adjuster gives approval. We know it’s unpleasant to leave dead animals on your property, but preserving evidence protects your claim and ensures faster resolution.
Payout speed depends largely on how well-documented your loss is and whether coverage is clear-cut. Simple accident claims with good documentation often settle within days, while mortality claims requiring veterinary analysis may take several weeks to complete properly.
Can I insure animals I just bought yesterday?
This question comes up frequently, especially during busy buying seasons when farmers are adding animals regularly to their operations.
The good news is that most livestock policies include automatic extensions that provide immediate coverage for newly acquired animals. These extensions typically last 30-60 days, giving you time to contact your agent and adjust your coverage limits without creating dangerous gaps.
Reporting windows vary by policy, but you generally have 30-60 days to notify your insurance company about new animals. Don’t wait until the last minute – report new acquisitions promptly to ensure continuous coverage and avoid any potential disputes.
Keep your proof of purchase documentation organized and accessible. Sales receipts, health certificates, transportation records, and any veterinary paperwork help establish ownership dates and animal values if you need to file a claim.
Temporary coverage under automatic extensions protects new animals immediately, but this coverage often has limits. High-value breeding stock or show animals might need individual scheduling to ensure full protection beyond the automatic extension period.
What’s the difference between mortality and standard broad-form coverage?
Understanding these two main coverage types helps you choose the right protection level for your specific animals and budget.
Standard broad-form coverage protects against specific named perils like fire, lightning, vehicle accidents, and windstorms. Think of it as covering sudden, accidental losses from external causes. This coverage works well for commercial operations where animals have similar values and you’re primarily concerned about catastrophic events.
Mortality insurance takes a much broader approach, covering death from virtually any cause except specific exclusions. Disease, illness, injury, and even necessary destruction due to suffering all qualify for coverage under mortality policies.
The premium comparison tells the story clearly – mortality insurance typically costs 3-6% of your animal values annually, while standard coverage runs 1-2% of values. That significant cost difference reflects the much broader protection mortality insurance provides.
Suitability depends on your animals’ values and your risk tolerance. High-value breeding stock, registered animals, and show livestock often justify the extra cost of mortality coverage. Commercial cattle, hogs, or poultry operations might find standard broad-form coverage provides adequate protection at a more reasonable cost.
At Farm & Country Insurance, we help you evaluate which approach makes sense for your operation. Sometimes a combination works best – mortality coverage for your most valuable animals and standard coverage for the rest of your livestock.
Conclusion
Your livestock represent more than just farm animals – they’re valuable assets that power your operation’s success and your family’s future. Finding the right livestock insurance near me protection isn’t just smart business; it’s essential for weathering the storms that every farmer faces.
Long-term resilience starts with understanding that hope isn’t a strategy. Whether you’re managing a dairy operation in the Finger Lakes, raising beef cattle in the Southern Tier, or caring for horses across central New York, unexpected disasters can strike without warning. Fire, storms, accidents, and market volatility don’t respect farm boundaries or family traditions.
The smartest farmers combine private livestock insurance with federal risk management programs like LRP and LGM. This layered protection shields you from both physical losses and market swings that could otherwise devastate years of hard work. Think of it as building a financial fence around your most valuable assets.
Proactive risk management means taking action before you need it. We’ve seen too many farmers find their coverage gaps only after tragedy strikes. By then, it’s too late to protect the genetics, breeding programs, and income streams that took years to build.
At Farm & Country Insurance, we’ve been helping New York farmers steer these decisions since 1984. Our single-point contact approach means you work directly with agricultural specialists who understand your challenges. We know the difference between a Holstein and a Hereford, and we understand how losing either could impact your operation.
Our Farm & Country Insurance expertise covers the full spectrum of New York agriculture – from dairy farms in Wyoming County to vegetable operations in Orleans County. This deep agricultural knowledge helps us spot risks other agents might miss and recommend coverage solutions that actually fit your operation.
Don’t gamble with your livelihood. Contact us today to discuss your livestock insurance near me options and build protection that matches your operation’s unique needs. Your animals deserve comprehensive coverage, and your family deserves the peace of mind that comes with proper protection.
More info about insuring livestock provides additional details about coverage options and protection strategies for your farming operation.