
You're probably using a farm truck today for something that seems routine. Hauling feed from one barn to another, moving produce to a local buyer, pulling a trailer with equipment, or getting livestock from one point of the farm to the next stop on the road. Around Honeoye Falls and across New York, that truck usually isn't a side piece of equipment. It's one of the machines that keeps the whole operation moving.
That's why farm truck insurance gets misunderstood so often. A lot of owners assume the same policy that works for a personal pickup, or even a basic business vehicle, must be enough for a working farm truck. It usually isn't. Once that truck is tied to livestock, grain, produce, inputs, employees, trailers, or public-road exposure, the gaps start showing up fast.
A local farm truck insurance agent in Honeoye Falls, NY should understand that difference without needing a long explanation from you. The right conversation starts with how the truck is used, what it carries, who drives it, where it goes, and what kind of loss would hurt your cash flow the most if something went wrong.
Table of Contents
- Your Farm Truck The Unsung Hero of Your NY Operation
- Decoding Your Essential Farm Truck Coverages
- Key Risk Factors That Influence Your Premiums
- Navigating New York State Farm Vehicle Regulations
- Why a Local Honeoye Falls Agent Is Your Best Ally
- Securing Your Tailored Quote A Step-by-Step Guide
- Frequently Asked Questions for New York Farmers
Your Farm Truck The Unsung Hero of Your NY Operation
A farm truck earns its keep in ways that don't show up neatly on a spreadsheet. It handles the jobs between the big jobs. Seed, feed, fencing, parts, calves, produce, fuel cans, tools, and paperwork all seem to end up in that truck at some point during the week.
In this part of New York, that use is rarely simple. One day the truck stays close to the farm lanes. The next day it's on a public road with a loaded trailer, crossing an intersection, backing into a delivery point, or running a route in wet, icy, or muddy conditions. The insurance question isn't whether the truck is important. It's whether the policy matches the way the truck operates.
That's where many farm owners get exposed. A vehicle may look like a pickup on paper, but its use tells a different story. If the truck supports farm operations every day, carries farm goods, or is driven by more than one operator, the policy needs to reflect those facts clearly.
The mistake that causes trouble
The common error is assuming the vehicle itself is the whole risk.
It isn't. The risk also includes who drives it, what it hauls, whether it pulls a trailer, whether employees use it, and whether the load creates a separate financial exposure. A truck hauling empty racks is one thing. A truck hauling grain, feed, or livestock is another.

A farm truck should be insured based on real use, not on what the registration card or vehicle model seems to suggest.
What a good review should uncover
A practical farm truck review should answer a few direct questions:
- Who drives it: Owner only, family members, employees, or seasonal help.
- What it carries: Bulk commodities, supplies, tools, livestock, or mixed-use loads.
- Where it operates: Farm lanes only, local roads, county routes, or longer trips across New York.
- What loss would hurt most: Injury to others, damage to the truck, or loss of cargo in transit.
If you're searching for a local farm truck insurance agent in Honeoye Falls, NY, that's the level of detail you want. Generic auto talk won't protect a working farm vehicle.
Decoding Your Essential Farm Truck Coverages
The starting point is simple. A farm truck policy has to protect more than the sheet metal. It has to address liability to others, damage to your own vehicle, and the farm-specific exposures that show up once cargo, trailers, and road use enter the picture.

Where most farm truck policies fall short
The biggest misunderstanding involves Commercial Auto Liability versus Motor Truck Cargo. They sound related, so owners often assume one naturally covers the other. It doesn't work that way.
The clearest real-world explanation comes from farm hauling insurance guidance for Honeoye Falls operations. The trade-off is direct. Commercial Auto Liability covers bodily injury and property damage to third parties if your truck causes an accident, but it excludes loss of the cargo itself. Motor Truck Cargo is the endorsement that responds when livestock or grain is damaged, lost, or compromised during transit. That cargo exposure can exceed $50,000 per incident for high-value biological assets like livestock.
Think of liability as paying for the damage outside the truck. Cargo coverage addresses the value inside the truck.
If a loaded truck slides through an intersection and hits another vehicle, liability may respond to the other party's injuries or property damage. If the same event ruins the load you were transporting, that's a different question entirely. Without the right cargo endorsement, the farm may absorb that loss itself.
For a closer look at where policy assumptions often break down, this overview of commercial vehicle insurance vs personal coverage is a useful reference.
Practical rule: If the truck hauls farm products, feed, or livestock for your operation, ask specifically what covers the cargo and what does not.
The coverages that matter on a working farm
Beyond liability and cargo, several other coverages deserve a direct review.
| Coverage | What it does | Why it matters on a farm |
|---|---|---|
| Physical Damage | Covers damage to your truck from a covered loss | Repairs or replacement can disrupt planting, harvest, feeding, and deliveries |
| Uninsured or Underinsured Motorist | Helps if another driver causes the accident and lacks enough insurance | A farm shouldn't depend on the other driver's policy being adequate |
| Medical Payments or similar injury protection | Helps with injury-related costs after an accident | Useful when the people in the truck are part of the farm workforce |
| Pollution-related protection | Addresses certain environmental loss situations when endorsed properly | Important if spills, runoff, or fire-related contamination become part of the claim |
| Motor Truck Cargo | Covers damaged or lost cargo in transit | Essential when moving grain, feed, produce, or livestock |
Some operations also need a sharper look at trailer issues, hired vehicles, and whether loading or unloading creates separate liability exposure. That's especially true when multiple trucks, multiple drivers, and seasonal hauling all overlap.
Cornell Small Farms notes that the two primary insurance types specifically available to farmers are liability insurance and crop insurance, with liability covering bodily injury, property damage, and legal costs, and crop insurance addressing yield or revenue losses due to weather, disease, or other perils. For truck decisions, that liability framework is the important starting point. Then you build outward to the farm-specific endorsements the truck exposure requires.
Key Risk Factors That Influence Your Premiums
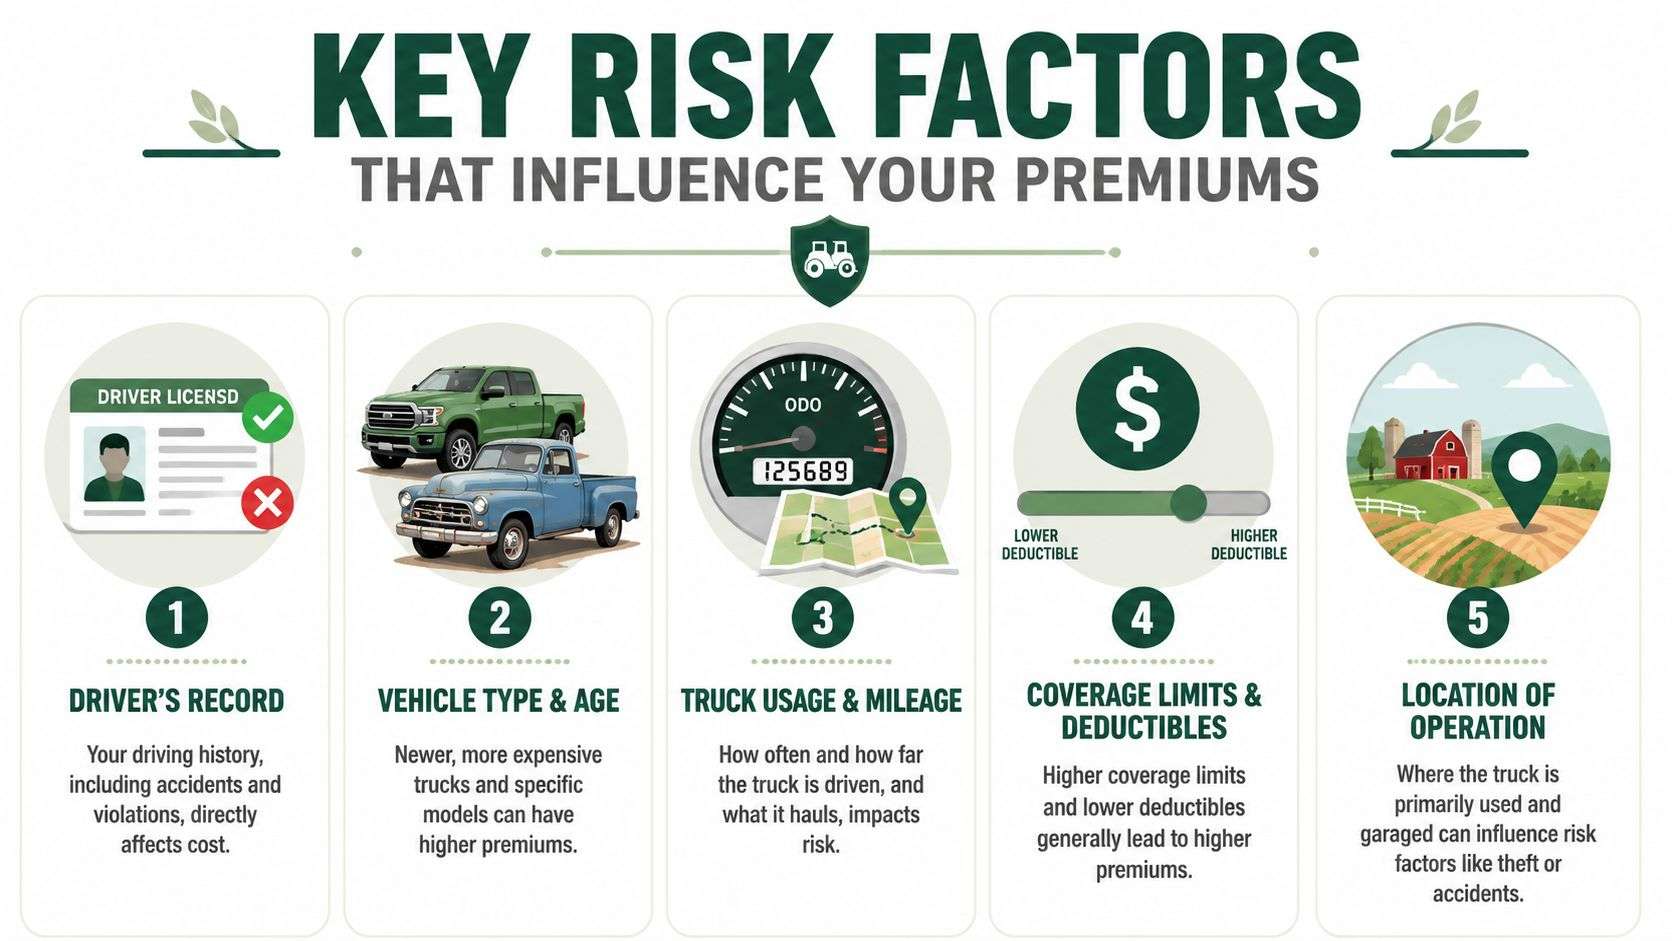
Price comes from exposure, not guesswork. Two farms can own similar trucks and still pay very different premiums because rating factors are tied to who drives, what the truck does, how far it goes, and how much loss the policy is being asked to absorb.
What insurers look at first
The driver list matters immediately. A truck driven only by one experienced operator presents a different risk than a truck used by several family members, employees, or temporary harvest help. Clean records usually support better pricing because they point to steadier operating habits.
Vehicle type also changes the picture. A heavier truck, a newer truck, or one with higher repair value creates a different exposure than an older utility pickup used for lighter work. The insurer isn't just looking at the badge on the hood. They're looking at how expensive the unit is to repair or replace and how it's being used in the field and on the road.
Mileage and radius are just as important. Local hauling close to the farm usually looks different from repeated road use over wider distances. More miles mean more time in traffic, more intersections, and more chances for a loss.
Operational choices that change cost
Some of the most important premium drivers come from daily decisions, not from the truck itself:
- Cargo type: Hauling empty supplies is different from hauling grain, feed, or live animals.
- Seasonal concentration: A truck that is lightly used most of the year but heavily used during harvest still faces periods of intense exposure.
- Coverage design: Higher limits and broader protection can increase premium, while different deductibles change how much risk the farm keeps.
- Garaging and operating territory: Where the truck is kept and where it runs affect claim patterns and loss potential.
The cheapest policy on paper often becomes the most expensive one after a claim, because the missing endorsement is what you needed most.
For farms that winterize equipment, tanks, and seasonal systems, the same mindset applies to trucks and supporting gear. Loss prevention matters. A practical off-season checklist can help reduce avoidable damage, and this 2026 freeze protection guide is worth reading as part of broader cold-weather preparation.
If you want to manage premium without creating dangerous gaps, start with three questions. Which trucks need full physical damage coverage year-round, which drivers should be formally scheduled, and which hauling exposures need special endorsements because the load itself carries the financial risk.
Navigating New York State Farm Vehicle Regulations
Insurance and legal compliance overlap, but they aren't the same thing. A truck can be insured poorly and still be registered. It can also be insured properly and still create trouble if the vehicle's use, plate type, or inspection status doesn't line up with New York requirements.

Keep insurance and compliance separate in your mind
A smart farm owner treats these as two separate checklists. One list asks, “Will the policy respond to the loss?” The other asks, “Are we operating this truck legally on public roads in New York?”
That second list matters more than many people realize. Plate class, truck weight, route use, trailer use, and inspection obligations all affect how the truck should be handled operationally. If the truck's use has drifted over time, the paperwork may no longer match reality.
Internal coordination helps. A practical review of insurance for farm vehicles can help you line up your policy details with the way the truck is used on the farm and on public roads.
A practical compliance checklist
Use this as a working review before heavy seasonal use begins:
- Confirm registration use: Make sure the truck's actual farm use matches the registration and plate status you rely on.
- Review driver expectations: If employees or seasonal workers operate the vehicle, verify that your procedures and policy details reflect that.
- Check inspection obligations: Trucks used in broader commercial ways may trigger inspection and recordkeeping issues that owners sometimes miss.
- Match trailers to use: If the truck regularly tows, review both the legal and insurance side of that setup.
- Recheck operating territory: Local use can become wider use without anyone formally updating the file.
If your operation involves commercial-weight vehicles, annual inspection requirements deserve special attention. This practical overview of understanding annual DOT requirements is a useful resource for spotting inspection issues before they create roadside or claim problems.
If the truck's use changed in the last year, assume the paperwork needs to be reviewed too.
In New York, compliance trouble often starts with routine growth. A farm adds another route, another driver, another trailer, or another kind of load. Nothing looks dramatic day to day, but the vehicle ends up operating outside the assumptions behind the policy or registration. That's when a simple roadside event turns into a larger problem.
Why a Local Honeoye Falls Agent Is Your Best Ally
Farm truck insurance is one of those areas where local detail matters. A generic vehicle questionnaire doesn't tell the full story of a working farm in this region. Road conditions, farm layout, weather patterns, harvest timing, and the way New York farms move products all affect what good coverage looks like.
Local knowledge changes the questions
A local specialist asks sharper questions because the context is familiar. They know a truck may spend one part of the day on private lanes and another on public roads. They know the same vehicle may haul inputs in the morning and product in the afternoon. They know some exposures don't show up unless someone asks about cargo, employee drivers, seasonal use, or environmental liability.
That kind of review is more useful than a broad commercial auto conversation. The purpose isn't to make the policy more complicated. It's to make sure the policy matches real farm operations in New York.
Farm-only specialization matters
A farm-only agency stands apart. According to Farm & Country Insurance's New York farm insurance profile, the agency was founded in 1984, is based in Honeoye Falls, is exclusively licensed in New York, and serves over 650 New York State farms with a team of six dedicated agents focused on risk mitigation for farms of every size.
Those details matter because they point to specialization, not side work. This isn't a general office that happens to write a few farm policies. It's a New York farm insurance practice built around the realities of dairy farms, grain operations, produce farms, orchards, and agribusinesses.
A local owner also benefits from easier communication when a truck's use changes mid-season. If a truck starts hauling a different commodity, adds another driver, or takes on a wider radius, you want someone who immediately understands why that change matters.
For farm owners comparing what good representation looks like, this page on a commercial vehicle insurance agent for farm operations helps frame what specialized guidance should include.
Securing Your Tailored Quote A Step-by-Step Guide
A good quote starts before the call. If the information is incomplete, the pricing may look fine at first and then change once the actual vehicle use comes out. That wastes time and creates confusion right when you're trying to get trucks on the road.

What to gather before you call
Start with the truck itself. Have the VIN, year, make, model, and any details on modifications or attached equipment. If the truck pulls a trailer regularly, gather the trailer information too.
Then build the driver list. Include every person who may realistically operate the vehicle, not just the main owner. If seasonal labor or family members ever drive it, say so up front. A policy can't be accurately structured around drivers the agent never knew existed.
You'll also want a short description of use:
- Primary hauling tasks: Feed, grain, produce, livestock, tools, or mixed farm use.
- Operating area: Mostly near the farm, broader county travel, or wider New York routes.
- Frequency: Daily use, seasonal concentration, or occasional backup use.
- Road exposure: Public roads only when necessary, or regular repeated trips.
How to make the quote accurate the first time
Bring your current policy if you have one. Not because the new quote should copy it, but because the declarations page often shows where the current setup may be too narrow or outdated.
Be direct about loss concerns. If the truck itself is replaceable but the load is the primary exposure, say that. If driver turnover is the challenge, say that. If you're worried about a gap between vehicle liability and cargo loss, raise it immediately.
A strong quote conversation usually follows this order:
- Identify the unit so there's no confusion about which vehicle is being discussed.
- Describe actual use in plain language, including what's in the bed, on the trailer, or inside the box.
- List all drivers who may use the truck.
- Flag seasonal shifts that change mileage, routes, or hauling type.
- Review existing insurance for missing endorsements or outdated assumptions.
The fastest quote is not the best quote. The accurate quote is the one that holds up after a claim.
If you're looking for a local farm truck insurance agent in Honeoye Falls, NY, that preparation makes the conversation much more productive. It lets the policy be built around the truck's job, not just its vehicle class.
Frequently Asked Questions for New York Farmers
Does my policy cover employees or seasonal drivers
Not automatically in every situation. Coverage often depends on who is listed, how the vehicle is rated, and whether the policy reflects the way your farm staffs truck use. If employees or seasonal help may drive the truck, disclose that early. Don't wait until a claim forces the issue.
A practical rule is simple. If someone has access to the keys during the season, review that person's role in the policy conversation.
What if I haul across state lines
That changes the discussion. Even if most of your work stays in New York, crossing a state line can introduce different regulatory and insurance issues tied to vehicle use, radius, filings, or inspection expectations. The right move is to mention interstate use before binding coverage, even if the trips are occasional.
This doesn't always mean the policy becomes dramatically different. It does mean the assumptions behind a local-use policy may no longer fit.
Are tools and personal items in the cab covered
Don't assume they are. Some owners expect anything inside the truck to be covered under the auto policy, but that's often not how claims are handled. Coverage for loose tools, equipment, supplies, paperwork, or personal items may depend on what the property is, why it was there, and whether another part of the farm policy is meant to address it.
Before a loss happens, ask three direct questions:
- Farm tools: Are hand tools and small equipment in the truck covered, and under which part of the policy?
- Personal belongings: Are jackets, phones, coolers, or other personal items excluded?
- Loaded supplies: If seed, chemicals, parts, or boxed produce are in transit, is that treated as cargo, equipment, or personal property?
The best FAQ answer is still a coverage review. Farm truck claims often go sideways because the owner assumed “in the truck” meant “covered by the truck policy.” That assumption creates trouble.
If you want a policy built around how your farm truck works in New York, talk with Farm & Country Insurance. They focus only on farm insurance, work exclusively with New York farms, and can help you review truck use, cargo exposure, drivers, and the coverage details that shouldn't be left to assumption.