
Why Risk Management for Farms is Critical to Your Success
Risk management for farms is the foundation that separates thriving agricultural operations from those that struggle against unexpected challenges. Farmers face daily uncertainties—from weather and equipment failure to market volatility—that can devastate their livelihood. The difference between proactive and reactive management often means the difference between financial stability and bankruptcy.
As one industry expert notes: “Good risk management involves anticipating potential problems and planning to reduce their detrimental effects. Simply reacting to unfavorable events after they occur is not good risk management.”
A comprehensive risk management plan helps you:
- Protect your assets from catastrophic losses
- Maintain cash flow during difficult periods
- Secure financing with reduced lender risk
- Plan for succession and long-term growth
With a career dedicated to helping New York farmers develop risk management for farms strategies, it’s clear how essential this is to protecting an operation’s assets and legacy. Experience shows that the most successful farms are those that plan ahead.

Learn more about risk management for farms:
Understanding the Five Pillars of Farm Risk
Risk management for farms starts with understanding the complex web of uncertainties you face. Experience helping New York farmers shows that farm risks fall into five distinct categories. Each presents unique challenges, but they are interconnected and can be managed with comprehensive planning.
- Production risk is what keeps many farmers awake at night. Mother Nature doesn’t follow business plans, pests and diseases can strike at any time, and equipment can break down during harvest.
- Market risk brings its own headaches. The prices you receive for products and pay for inputs like feed and fertilizer can swing dramatically due to global markets, government policies, and trade disputes.
- Financial risk stems from your farm’s borrowing and debt. Interest rate changes, credit availability, and cash flow challenges can threaten your operation’s financial health.
- Legal risk encompasses the ever-changing world of government regulations, contracts, business structures, and potential liability issues.
- Human risk involves the people who make your farm run. Health issues, accidents, death, or family disagreements can severely impact your farm’s continuity.
These five risks don’t operate in isolation. A drought (production risk) can lead to cash flow problems (financial risk). A trusted advisor can help you steer these interconnected challenges.

Production and Market Risks: The Unpredictables
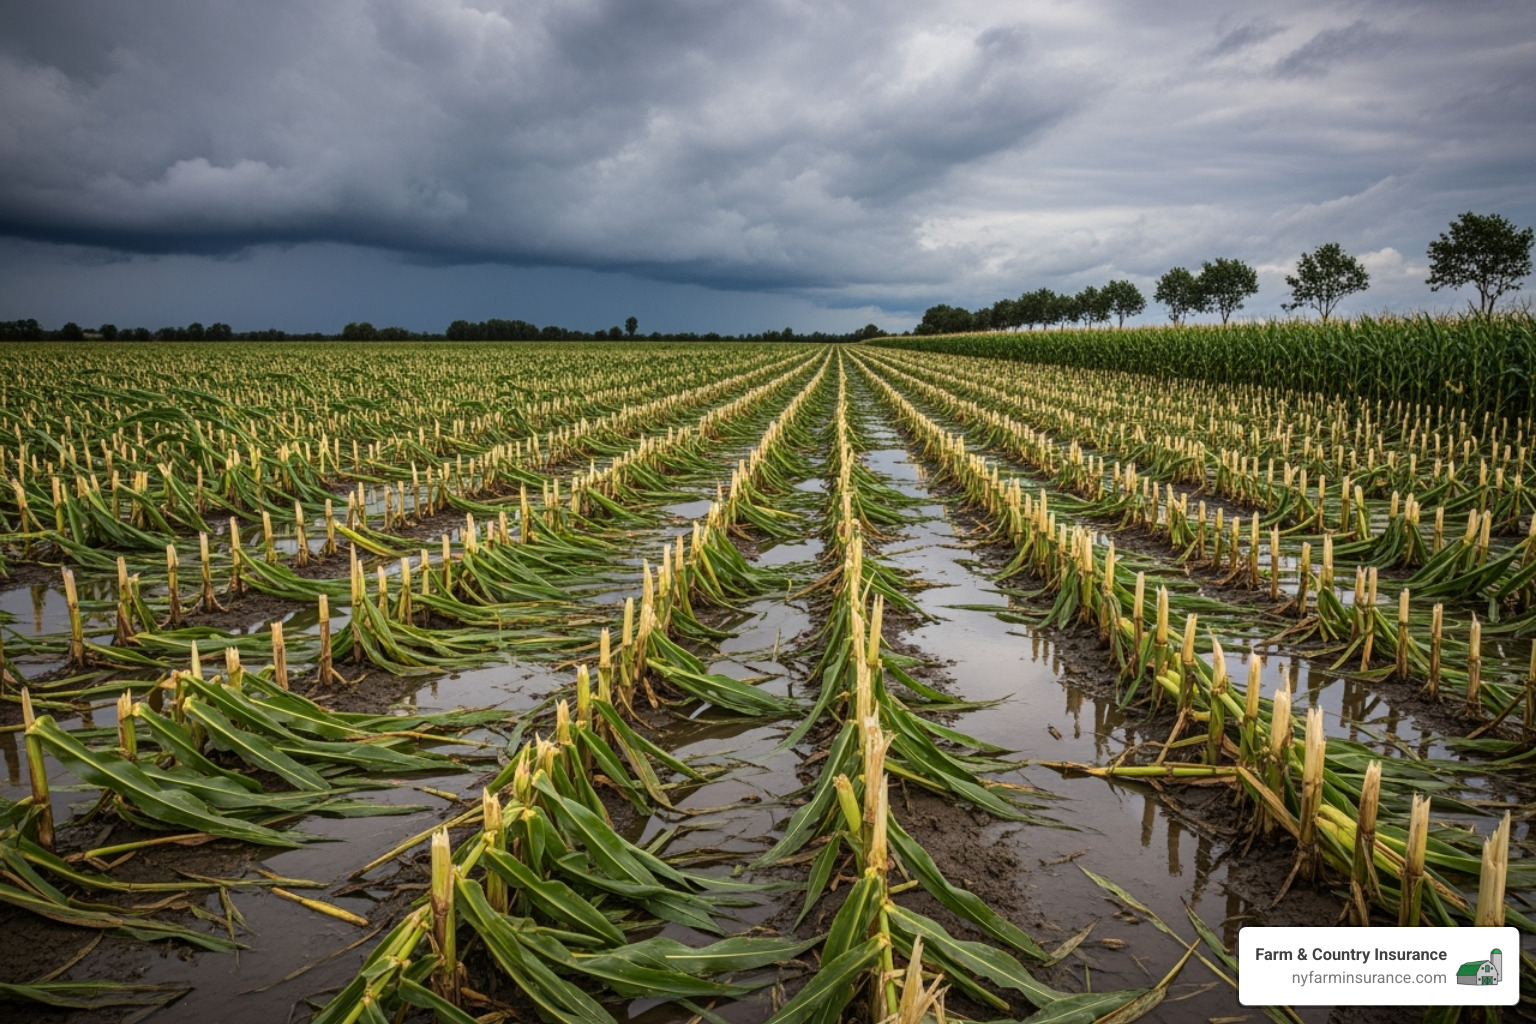
While you can’t control the weather or global markets, you can manage your exposure.
- Diversification is a classic strategy: a farm growing multiple crops has several income streams, so if one struggles, others might thrive.
- Hedging strategies like futures or options contracts let larger operations lock in prices for commodities, transferring price risk.
- Contract production can provide guaranteed prices and secure market outlets, which is common in the poultry and livestock industries.
- Crop insurance is an essential tool for managing production risk. Crop Insurance for Farmers is a must-have, while Livestock Insurance provides similar protection for animals.
Financial, Legal, and Human Risks: The Controllables
You have greater control over these risks through proactive planning.
- Maintaining liquidity (available cash) provides a cushion during tough times. This is critical for farms carrying higher debt levels.
- Business structure decisions (sole proprietorship, LLC, etc.) impact your liability, taxation, and succession planning, protecting both business and personal assets.
- Estate planning ensures your farm’s continuity by planning for its transfer to the next generation, minimizing disputes and financial burdens.
- Employee safety training reduces accident risks, protecting your workforce and avoiding costly legal claims.
- Personal crises like illness or disability require advance planning. Life and health insurance, combined with succession plans, help ensure your farm continues.
- Environmental liability is a growing legal risk. Pollution Insurance addresses the significant costs that can result from accidental spills.
A Practical Guide to Risk Management for Farms
Think of risk management for farms as building a sturdy foundation. It’s about making smart, daily decisions to protect your livelihood, guided by your personal comfort with risk and your farm’s financial situation. The foundation of good risk management is solid information—accurate data on costs, yields, and market trends allows you to make rational decisions instead of just hoping for the best.
| Strategy | Description | Example |
|---|---|---|
| Avoid | Structure the business so certain risks are nonexistent. | A farmer decides not to grow strawberries because they lack the labor to pick them. This avoids the risk of labor shortages and potential crop loss. |
| Reduce | Lower the risks associated with the business venture through proactive measures. | A farmer provides safety training to employees to lower the risk of injury. Using crop rotation to prevent disease build-up in the soil. |
| Transfer | Shift the cost of an undesirable outcome to someone else, often for a specified price. | A farmer buys crop insurance to cover potential losses from adverse weather. Using futures contracts to lock in a selling price for grain. |
| Accept (Retain) | Retain or accept risks, often to maintain control or improve overall profitability, and be ready to bear the consequences. | A farmer accepts the risk of a new employee leaving if it has little impact on the business, budgeting for potential turnover rather than investing heavily in retention programs for every new hire. |
Core Strategies: Avoid, Reduce, Transfer, Accept
Every risk management decision falls into one of the four categories detailed in the table above. Avoidance can be the smartest choice, like not planting a crop you can’t reliably harvest. Risk reduction includes daily actions like safety training and equipment maintenance. Transferring risk means paying someone else to shoulder the burden, such as buying Farm Equipment Insurance or crop insurance. Finally, accepting risk makes sense for small, manageable losses where the cost of protection isn’t worth it.
Practical Risk Reduction Tactics for Your Operation
The most successful farms layer multiple approaches to create a robust safety net.
- Enterprise diversification: Income from multiple sources (e.g., dairy, hay, cash crops) means a problem in one area won’t sink the entire operation.
- Vertical integration: Processing your own products gives you more control and helps you capture more value.
- Spreading your sales: Storing some grain and selling it gradually throughout the year can smooth out price volatility and improve your average price.
- Maintaining input reserves: Having extra feed, fuel, or spare parts on hand prevents disruptions when supplies are tight.
- Off-farm income: Money from non-farm sources creates a financial cushion during tough farming years.
- Safety measures: Regular equipment maintenance and safety training protect your most valuable asset—your people.
- Farm Income Protection Insurance: A tool like Farm Income Protection Insurance provides a crucial safety net against market fluctuations and unexpected losses.
Creating Your Farm’s Risk Management Action Plan
The best risk management for farms involves having a solid plan before you need it. A good plan follows a continuous cycle that evolves with your farm. We use the S.A.F.E. method: See it, Assess it, Fix it, Evaluate it. This approach ensures you’re always one step ahead of potential problems. It’s not about being paranoid—it’s about being prepared.
Step 1: Identifying Threats in Risk Management for Farms
This first step is about opening your eyes to what could go wrong so you can do something about it.
- Brainstorm “what if” scenarios across all areas of your operation. What if we get too much rain during harvest? What if our main buyer cancels their contract?
- Use checklists to be systematic. The USDA Risk Management Checklist benefits is an excellent starting point that covers a wide range of risks.
- Conduct workplace inspections. Walk around your farm with fresh eyes to spot small hazards like a loose handrail or a rusty fuel tank before they become big problems.
- Review past incidents. Look back at your records to see when equipment broke down or what caused your biggest losses to identify patterns and warning signs.
- Keep detailed farm records. Your records are your best teacher for understanding risk patterns. If you’re just starting, begin filing a Schedule F immediately for future insurance eligibility.
Step 2: Assessing and Prioritizing Risks
Once you’ve identified threats, you need to decide which ones deserve your attention first.
- Evaluate likelihood versus impact. Ask yourself: How likely is this to happen, and how much would it hurt if it did? A minor repair might be likely but have low impact, while a devastating hailstorm is unlikely but could wipe out your season.
- Prioritize high-impact risks. A catastrophic loss can end your farming operation, even if the odds are low. These are the risks you must transfer through insurance or other protective measures.
- Understand your personal risk tolerance. Some farmers are comfortable with bigger risks for bigger rewards, while others prefer security. Your approach should match your comfort level and financial capacity.
- Assess your physical assets. Your barns, storage facilities, and equipment are major investments. Farm Building Insurance should be part of your evaluation to protect these critical structures.
The goal isn’t to eliminate all risk, but to identify which risks you can live with and which ones could cripple your operation, then plan accordingly.
Essential Tools for Your Risk Management Toolkit
Think of risk management for farms like building a house—you need the right tools for the job. While good farming practices are your foundation, external resources and financial instruments provide the walls and roof that protect you. You’re not going it alone; a support network of government programs, university resources, and professional advisors is available.
The Role of Insurance in Risk Management for Farms
Insurance is the heart of effective risk management for farms. It’s your financial safety net, allowing you to transfer the cost of unexpected losses.
- General Liability Insurance protects you from claims if visitors are injured or your operations damage someone else’s property.
- Property Insurance safeguards your physical assets like barns, equipment, and stored crops from events like fire or storms.
- Crop Insurance, often federally subsidized, covers production losses from weather, pests, and other perils.
- Whole-Farm Revenue Protection (WFRP) is ideal for diversified farms, as it protects a percentage of your entire farm’s revenue rather than individual crops.
- Agribusiness Insurance like Agribusiness Insurance extends protection to commercial activities like processing or packaging.
- Workers’ Compensation Insurance is legally required if you have employees and covers medical costs and lost wages from workplace injuries.
- Umbrella Policies provide an extra layer of liability protection, kicking in when claims exceed your primary policy limits.
Leveraging Government Programs and External Resources
You have powerful allies in managing farm risks.
- The USDA Risk Management Agency (RMA) oversees the federal crop insurance program and offers extensive resources, like A Beginner’s Guide to Crop Insurance.
- The Farm Service Agency (FSA) provides disaster assistance and emergency loans, including the Noninsured Crop Disaster Assistance Program (NAP) for specialty crops.
- University Extension specialists are goldmines of practical, research-backed information on local conditions and challenges. Resources like those from the CT Department of Agriculture Resources can be invaluable.
- Professional advisors, including experienced farm insurance brokers, accountants, and attorneys, bring specialized expertise. They can help you build comprehensive protection strategies custom to your farm’s needs.
Frequently Asked Questions about Farm Risk Management
When it comes to farm risk management, many of the same questions come up. Here are answers to the most common concerns.
What are the most common risks New York farms face?
New York agriculture has unique challenges. The most common risks include:
- Weather extremes: From heavy winter snows that can collapse barn roofs to summer droughts that wither crops.
- Market price fluctuations: These hit dairy and grain producers especially hard, making income unpredictable.
- Labor shortages: Finding reliable, skilled workers is a growing challenge for all types of farm operations.
- Regulatory changes: Constantly evolving environmental, labor, and food safety laws create compliance burdens.
- Increased tort liability: For farms with agritourism or direct sales, the risk of visitor injuries and lawsuits is a major concern.
Our Farm Insurance FAQs page addresses how proper coverage can manage these specific New York risks.
How often should I review my farm’s risk management plan?
Your risk management for farms plan is a living document that should evolve with your operation. Review it:
- Annually: At a minimum, do a yearly check-up during your slower season to ensure the plan still matches your goals.
- After major operational changes: Adding new enterprises, buying significant equipment, or changing your business structure all create new risks.
- Following a significant loss event: A major crop failure or legal claim offers valuable lessons for adjusting your plan.
- When personal life changes: Marriage, health issues, or adding family to the operation all affect your risk profile.
Can a small hobby farm benefit from a risk management plan?
Yes, absolutely! Every farm faces risk, regardless of size. Your tractor can break down, or a visitor to your farm stand could slip and fall. The financial impact can still be significant to your personal finances.
The beauty of risk management for farms is that strategies are completely scalable. While you may not need crop insurance for a small garden, liability coverage is crucial if anyone visits your property or buys your products. A lawsuit could put your home and personal assets at risk. For hobby farmers, a good starting point is Homeowners Insurance for Hobby Farms that includes liability coverage for your farming activities.
Secure Your Farm’s Future Today
Your farm is more than a business—it’s your legacy. Effective risk management for farms is the foundation that protects it. By understanding the five pillars of risk and implementing core strategies, you can create a proactive plan that turns potential disasters into manageable setbacks.
Proactive management is key. The farms that succeed are the ones that anticipate challenges and have plans in place. This approach creates financial stability and opportunities for growth, allowing you to invest in improvements and sleep better at night knowing your family’s future is secure. Building this resilience is your competitive advantage.
Working with an advisor who has deep knowledge of New York’s dairy, grain, fruit, and vegetable operations means you can create solutions that fit your real-world needs. You’re not just buying a policy; you’re gaining a partner who understands farming from the ground up.
Don’t wait for a crisis. The best time to build your risk management for farms strategy is now. Partner with an expert farm insurance broker to build your custom risk management plan and take the first step toward securing your farm’s future for generations to come.