
Small Farm and Smallholding Insurance: Smart 2025
Why Small Farm and Smallholding Insurance is Essential for Your Agricultural Dreams
Small farm and smallholding insurance provides specialized coverage for properties that combine residential living with agricultural activities, typically on less than 100 acres. Unlike standard homeowners insurance, this policy is designed to protect your unique farming operations, livestock, equipment, and liability exposures.
Key Coverage Areas:
- Property: Barns, outbuildings, fences, and your home.
- Liability: For visitors, product sales, and farm activities.
- Livestock: Protection against theft, specified injuries, and disease.
- Equipment: Tractors, tools, and specialized machinery.
- Products: Coverage for harvested crops and other farm products.
If your property is more than a residence but not a large commercial farm, you need this specialized protection. Standard homeowners policies exclude most farming activities, leaving you with dangerous coverage gaps. Many New York smallholders in places like the Finger Lakes or Hudson Valley find too late that their regular insurance won’t cover livestock incidents, visitor injuries, or damage to barns.
We have spent years helping New York farmers protect their operations with custom small farm and smallholding insurance solutions. Our deep understanding of local agricultural risks ensures you get coverage that truly fits your needs.
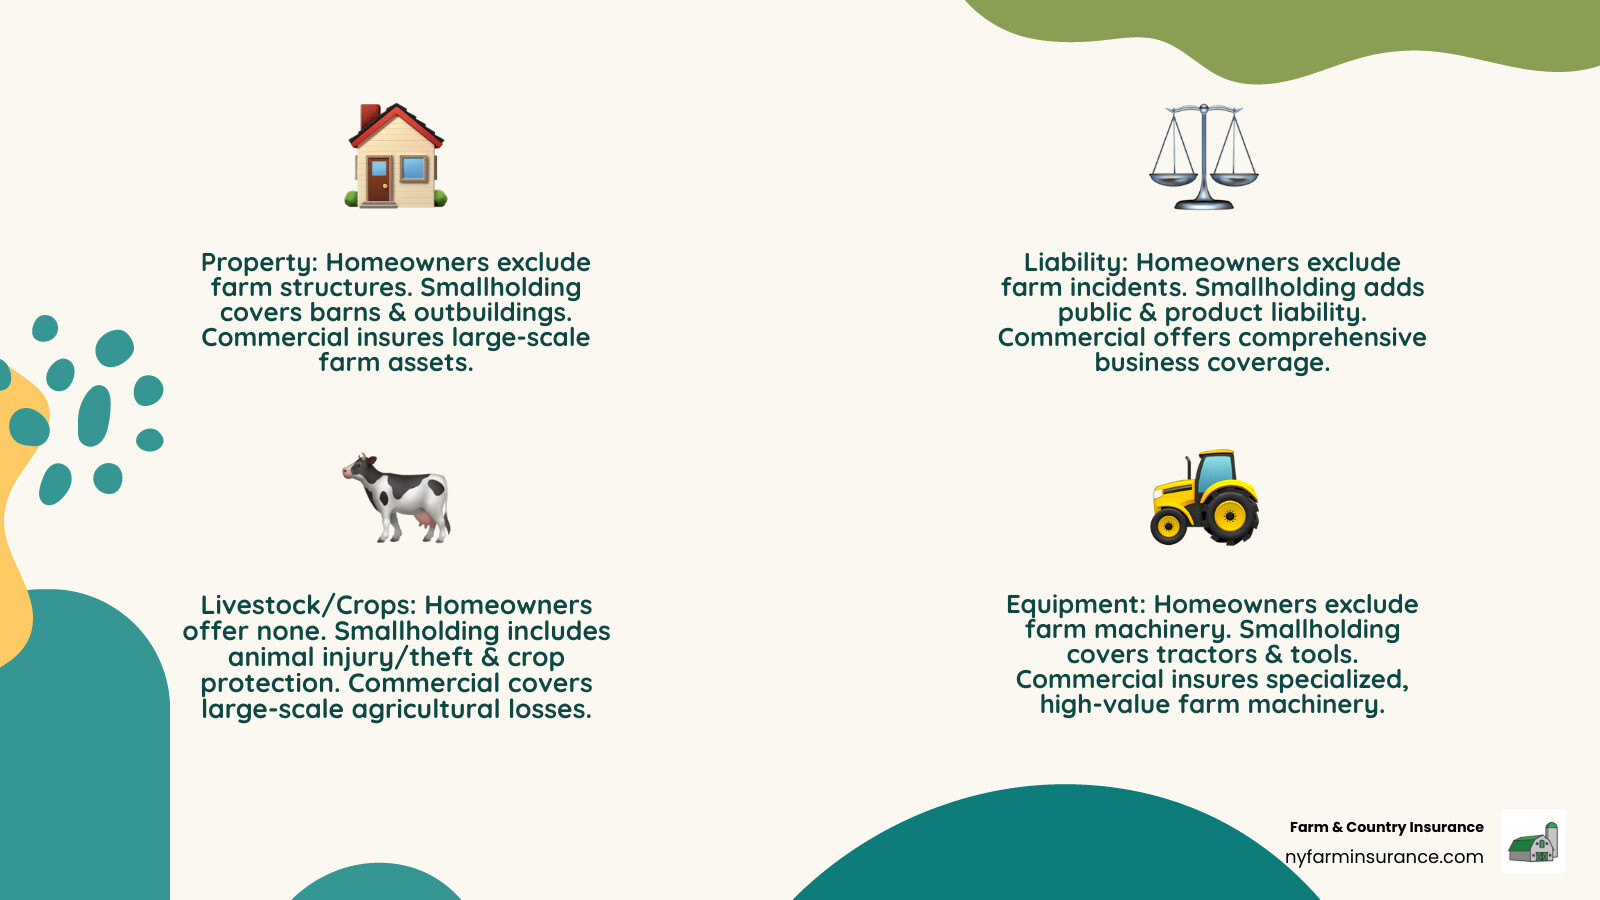
Small farm and smallholding insurance terms at a glance:
What is Smallholding Insurance and Why is it Different?
A smallholding or hobby farm is a small agricultural property, usually under 50 to 100 acres, where farming activities occur alongside residential living. These properties bridge the gap between suburban homes and full-scale commercial farms. Whether you’re a weekend farmer in the Finger Lakes or growing produce in the Catskills, your operation needs protection that standard insurance can’t provide.
Small farm and smallholding insurance is a hybrid policy designed for this unique lifestyle, recognizing that your home and agricultural pursuits are intertwined.

The problem with regular homeowners insurance is its assumption of a typical suburban life. The moment you add livestock, sell produce, or operate farm equipment, you step outside the boundaries of standard coverage. Your policy likely excludes most agricultural activities, leaving dangerous gaps. For example, if a visitor is injured by a farm animal or a fire destroys your barn, a typical homeowners policy would likely leave you facing the losses alone. Small farm and smallholding insurance fills these crucial gaps.
This specialized coverage is flexible, designed for part-time farmers and rural landowners, even if farming isn’t your primary income source. New York’s diverse agricultural landscape, from apple orchards in Wayne County to dairy operations in the Southern Tier, presents unique risks that require local expertise. For more information and resources, the Cornell Small Farms Program is an excellent guide for New York operators.
Who Needs This Specialized Coverage?
You might need this coverage if you are a:
- Hobby farmer: Keeping a few animals for pleasure or personal use, like chickens for eggs or sheep for wool.
- Small-scale producer: Selling your bounty, such as herbs at the Ithaca Farmers Market or fresh eggs to neighbors. Once money changes hands, you have commercial liability.
- Lifestyle block owner: Living rurally for the space and freedom, with amenities like horses for pleasure riding or extensive gardens that create potential liability.
- Landowner leasing to farmers: Owning rural land in a place like the Mohawk Valley and leasing it to others still exposes you to liability as the property owner.
Essentially, anyone with agricultural activities not covered by home insurance should consider this specialized protection.
Smallholding vs. Standard Farm Insurance
Think of the difference like a family restaurant versus a massive food production facility. Both serve food, but at different scales with different risks.
- Policy Complexity: Smallholding policies are more straightforward, focusing on the specific needs of smaller operations without overwhelming jargon. Standard farm insurance is complex, covering vast acreages and intricate supply chains.
- Premium Costs: Smallholding coverage is typically much more affordable than full commercial farm policies, as the risks are less extensive.
- Scaled Coverage: Smallholding policies are scaled for properties up to 50-100 acres and may include unique features like coverage for B&B guests or small agritourism. Standard farm insurance covers operations that can span thousands of acres.
The key distinction is the focus on lifestyle versus large-scale commercial operations. Smallholding insurance protects your home and your agricultural venture as a single, integrated unit. For more information about farm insurance across all scales, visit our Farm Insurance page.
Core Components of Small Farm and Smallholding Insurance
Think of small farm and smallholding insurance as a safety net crafted for the unique risks of rural life. It’s not a one-size-fits-all solution, but a combination of protections for your New York smallholding. Your assets aren’t just buildings and equipment—they’re the foundation of your rural dream.

Property and Dwelling Coverage
Your buildings are the backbone of your operation. This coverage protects the physical structures on your property.
- Farmhouse: Protects your primary residence like a homeowner’s policy, but with the understanding that it’s part of an agricultural operation.
- Barns and Outbuildings: Covers essential structures like barns, sheds, and coops that are vital to your daily operations.
- Fences and Corrals: Protects the significant investment you’ve made in fencing to contain livestock and mark boundaries.
- Personal Property: Extends beyond typical household items to include farm-specific belongings like tools, stored feed, and harvested crops awaiting market.
For integrated coverage that treats your home and farm as a unified operation, learn more about Farmstead Insurance.
Liability Protection for Your Operations
Rural life introduces liability risks that suburban homeowners don’t face. Robust liability protection is a crucial part of any small farm and smallholding insurance policy.
- Public Liability: This is your first line of defense. It covers you if a visitor is injured on your property or if your animals escape and cause damage.
- Product Liability: Essential if you sell anything from your farm, such as eggs, produce, or homemade goods. It protects you if a customer claims your product caused illness or harm.
- Employers’ Liability: Legally required in New York if you hire anyone, even part-time or seasonal help. It covers claims related to work-related injuries.
- Lawsuit Protection: A key benefit, this coverage helps pay for legal defense costs and judgments, which can be financially devastating even if you win the case.
Livestock and Produce Coverage
Your animals and crops are significant investments. This coverage protects the heart of your operation.
- Livestock Theft: Protects against the financial loss from stolen animals, and often includes mysterious disappearance.
- Animal Injury and Disease: Coverage varies, but typically includes losses from specific perils like fire, lightning, or attacks by predators.
- Weather Damage: Acknowledges New York’s unpredictable climate by providing protection against events like frost, hail, or severe storms that can damage crops or harm livestock.
- Harvested Goods: Protects stored grain, preserved vegetables, or other products against fire, theft, or other perils while they await sale.
For more guidance, explore our resource on Agricultural Insurance for Small Farms.
Equipment and Machinery Insurance
This coverage ensures that mechanical failures or damage won’t derail your farming plans.
- Tractor Coverage: Protects what is often your largest single equipment investment against theft, collision, fire, and other specified perils.
- Farm Tools: Covers the collective value of your hand tools, power equipment, and other implements.
- Specialized Machinery: Provides protection for items like hay balers, milking equipment, or processing tools.
- Equipment Breakdown: Can help with repair costs and potentially provide temporary replacements when essential machinery fails.
- Rented or Leased Equipment: Extends protection to borrowed machines while they are in your care.
How to Get the Right Coverage for Your New York Smallholding
Finding the perfect small farm and smallholding insurance for your New York property requires a custom approach. Your coverage should be as unique as your operation, whether you’re tending sheep in the Finger Lakes or growing vegetables in the Hudson Valley.
We believe the best policies come from understanding your operation, your goals, and your concerns. This allows us to build coverage that protects what matters most.
Assessing Your Unique Risks
Before seeking quotes, evaluate your property and operations to determine your needs. Your insurance should reflect your actual activities. Consider these factors:
- Type of Operation: A dairy farm in Cayuga County has different risks than an apple orchard in Wayne County. Your policy should address your specific vulnerabilities, from equipment breakdown to crop failure from hail.
- On-Site Sales: A farm stand for eggs or produce creates a need for product liability coverage in case a customer gets sick.
- Agritourism Activities: Hosting school groups, offering B&B stays, or allowing camping brings additional liability risks that require specific coverage for visitors.
- Employees or Volunteers: New York law may require you to carry Employers’ Liability coverage even for part-time help or volunteers, protecting them and you.
- Value of Buildings and Equipment: Accurately assess the replacement cost of your barns, sheds, tractor, and tools. Underinsuring these assets can be a costly mistake.
- Livestock Value: Keep an updated valuation of your animals, as market prices change. Proper valuation ensures you are correctly compensated for a loss.
Choosing the Best Provider for small farm and smallholding insurance
Not all insurance companies understand farming. You need a partner who sees your operation’s potential, not just its risks.
- Look for specialists: Choose agricultural insurers who understand the nuances of farming. They know a barn is more than a building and can advise on specific risks.
- Value local expertise: An insurer familiar with New York’s weather, regulations, and farming challenges offers better guidance.
- Check reviews and reputation: Talk to other local farmers. A company’s reputation in the agricultural community speaks volumes about its service.
- Ensure an efficient claims process: When disaster strikes, you need a provider who handles claims quickly and fairly to get you back on your feet.
For help finding a specialist, see our guide on Farm Insurance Near Me.
Tips for Saving on Premiums
While small farm and smallholding insurance is a vital investment, you don’t have to overpay.
- Bundle policies: Combine your farm coverage with home and auto policies for significant discounts.
- Increase your deductibles: A higher deductible lowers your premium, but ensure you can afford the out-of-pocket cost if you file a claim.
- Implement safety protocols: Installing smoke detectors in barns, securing equipment, and maintaining safe walkways can earn you discounts.
- Perform regular maintenance: Well-maintained equipment is safer and less likely to break down, which some insurers reward with better rates.
- Schedule an annual policy review: Your operation changes, and so should your insurance. A yearly review ensures you’re not over or under-insured.
For more on managing costs, visit our guide on Small Farm Insurance Cost.
The Real Value: Benefits and Common Misconceptions
When you’re busy with the daily work of your farm, insurance probably isn’t top of mind. But small farm and smallholding insurance provides invaluable peace of mind, protecting the dream you’re building. It allows you to focus on your passion, knowing you’re covered against the unexpected.
Key Benefits for Your Financial Health
Your smallholding is a major investment. This insurance helps protect it.
- Protecting Your Livelihood: A single storm or accident could be financially devastating. Insurance helps you cover unexpected losses without draining your savings.
- Ensuring Operational Continuity: If a fire or disease disrupts your operation, business interruption coverage can help pay for fixed costs like loan payments and utilities while you recover.
- Improving Marketability: Many farmers’ markets in places like Rochester and Syracuse require vendors to carry liability coverage. Proper insurance opens doors to new sales opportunities.
Legal and Regulatory Requirements
In some cases, coverage isn’t just a good idea—it’s required.
- Employers’ Liability: New York law requires this coverage if you have any employees, protecting you and them from work-related injury claims.
- Loan and Grant Requirements: Lenders and grant providers often require proof of adequate insurance to protect their investment in your operation.
- Farmers’ Market Regulations: Most markets require vendors to show proof of liability coverage to protect the market, its customers, and other vendors. For business-focused coverage, explore our Small Farm Business Insurance options.
Debunking Myths about small farm and smallholding insurance
We often hear misconceptions that can leave smallholders dangerously exposed.
- Myth: “My homeowner’s policy is enough.” Reality: Standard homeowners policies explicitly exclude commercial and farming activities. Once you sell produce or keep livestock, you need specialized coverage.
- Myth: “It’s too expensive for a hobby farm.” Reality: These policies are specifically priced for smaller operations. The premium is a small price to pay to protect assets worth thousands.
- Myth: “I don’t need liability if I don’t sell anything.” Reality: Accidents happen regardless of sales. An escaped animal can cause damage, or a visitor can get injured, leading to liability claims.
- Myth: “Insurance is only for big farms.” Reality: Smallholdings, with their mix of residential and farm activities, often have more complex insurance needs than large, purely commercial operations.
Frequently Asked Questions about Small Farm Insurance
As specialists in New York farm insurance, we hear many of the same questions from smallholders across the state. Here are answers to the most common inquiries.
Do I need a farm policy if I only have a few animals?
Yes, absolutely. Even a few animals introduce risks that a standard homeowners policy will not cover. We’ve seen significant liability claims arise from seemingly minor situations, like a “harmless” goat escaping and causing a traffic accident.
- Liability for Animal Escapes: If your animals wander off your property and cause damage or injury, you are responsible. A farm policy is designed to cover this risk.
- Coverage for Theft or Injury: Your animals are an investment. Specialized insurance can protect you from financial loss due to theft or covered perils like fire or predator attacks.
- Affordable Premiums: Small farm and smallholding insurance recognizes that low-risk activities need protection, and premiums are scaled to reflect that lower risk. You won’t pay commercial rates for a small hobby farm.
For more details, see our guide on Hobby Farm Insurance.
Does smallholding insurance cover diversified activities like a farm stand or B&B?
Yes, but these activities must be specifically added to your policy, often through endorsements. It is critical that your insurer knows about every income-generating activity on your property.
- Product and Public Liability: If you run a farm stand, you need product liability in case a customer gets sick. If you host a B&B or farm tours, you need public liability for your guests.
- Full Disclosure is Key: Your coverage must match all your activities. Whether you offer riding lessons, host small events, or sell produce at a farmers’ market, you must inform your insurer. Failing to disclose an activity can lead to a denied claim. We work with you to ensure nothing falls through the cracks.
Is my tractor covered under my home or auto policy?
Typically, no. This is a common and costly misunderstanding. Tractors and other farm equipment face unique risks and require specific coverage that is not included in standard home or auto policies.
- Specialized Coverage Needed: A farm equipment policy or endorsement is designed for the harsh conditions and heavy use that tractors endure.
- On- and Off-Property Use: Proper farm equipment coverage protects your investment whether it’s working in your fields, stored in your barn, or being driven on a public road to another part of your property.
- Comprehensive Protection: This coverage protects against theft, damage from fire or collision, and liability if your tractor causes injury or property damage. Don’t assume your most essential machine is covered—verify it has the specialized protection it needs.
Conclusion
Your smallholding is more than just land and buildings; it’s the embodiment of a dream and a significant investment. Whether you’re in Cayuga County or the Hudson Valley, your rural lifestyle deserves protection that understands your unique world. Small farm and smallholding insurance is not just another policy—it’s the financial safety net that provides peace of mind.
We have specialized in protecting New York smallholders since 1984. We don’t offer cookie-cutter policies. Instead, we craft custom solutions that fit your specific blend of residential living and agricultural pursuits. Our deep understanding of local farming risks means we can anticipate your challenges and safeguard your future.
Don’t leave your passion vulnerable. Protect your investment with coverage as dedicated as you are.