
Why Every Small Farm Needs a Financial Safety Net
Small farm insurance cost typically ranges from $500 to over $3,000 per year, depending on your farm’s size, type, and coverage. Here’s a quick breakdown:
Estimated Annual Costs:
- Hobby farms (under 10 acres): $500-$2,500
- Small farms (under 100 acres): $2,000-$3,000
- Mid-size farms (100-500 acres): $2,500+
- Equipment coverage: ~$15 per $1,000 of value
- Livestock coverage: 2.5%-5% of animal value
Running a small farm means facing unique risks, from unpredictable weather to equipment breakdowns and on-site injuries. As one farmer put it, “Farming isn’t like other business”—and neither are its insurance needs.
The good news is that farm insurance doesn’t have to break your budget. With the right coverage, you can protect your livelihood without sacrificing financial stability.
I’m Casey Love, owner of Farm & Country Insurance. I’ve spent years helping New York farmers steer small farm insurance cost challenges. My background in farming gives me insight into the protection you actually need, helping you find coverage that fits your budget.
What is a “Small Farm”? Hobby vs. Commercial Operations
To understand small farm insurance cost, you first need to know how insurers classify your operation. It isn’t just about acreage; it’s about your farming purpose, income, and activities. This distinction directly shapes your coverage needs and costs.
Insurers typically categorize farms as either hobby or commercial operations. Knowing where your farm fits is the first step to securing the right protection.

Defining a Hobby Farm for Insurance Purposes
A hobby farm is primarily for personal enjoyment or self-sufficiency, not as a main source of income. It’s a passion project, not a full-time living.
Insurers typically define a hobby farm by these criteria:
- Acreage: 10 acres or less.
- Income: Gross annual income from farming activities under $8,000. This excludes income from land rental.
- Livestock: Generally fewer than 6 animals, excluding horses.
Standard homeowner’s insurance rarely covers farm-related risks like equipment, outbuildings, or liability. Hobby Farm Insurance provides the necessary “limited farm coverage” to fill these gaps, offering protection custom to these unique exposures.
Understanding Small Commercial Farm Insurance Needs
A small commercial farm operates to generate profit, often as the owner’s primary income. These farms are typically larger and more complex, potentially involving employees, agritourism, and more extensive equipment and livestock.
Their insurance needs are distinct and require comprehensive coverage for:
- Higher asset values: More buildings, machinery, and livestock.
- Increased liability: Risks from employees, customers, and complex operations.
- Business interruption: Protection for lost income after a major event.
A specialized Agriculture Insurance for Small Farms policy is essential. It provides robust protection that far exceeds what a hobby farm or homeowner’s policy can offer.
Here’s a quick side-by-side look to help you see the differences:
| Feature | Hobby Farm | Small Commercial Farm |
|---|---|---|
| Primary Goal | Personal enjoyment, self-sufficiency | Profit, primary income source |
| Acreage (typical) | 10 acres or less | Variable, often larger than 10 acres |
| Annual Income | Up to $8,000 from farming (not main income) | No income limit, primary income for owner |
| Livestock (typical) | Less than 6 (excluding horses) | More animals, including multiple species |
| Insurance Type | Limited Farm Coverage (add-on or stand-alone) | Comprehensive Farm Insurance |
| Liability Exposure | Moderate (visitors, basic farm activities) | Higher (employees, public, product liability) |
Decoding Your Policy: What Small Farm Insurance Actually Covers
Understanding your small farm insurance policy is key to ensuring you have the right protection. Think of it as a customized safety net for your unique operation. At Farm & Country Insurance, we know that no two farms are alike, so their insurance shouldn’t be either. Whether you run a dairy, vegetable, or grain farm, your coverage must match your specific risks.
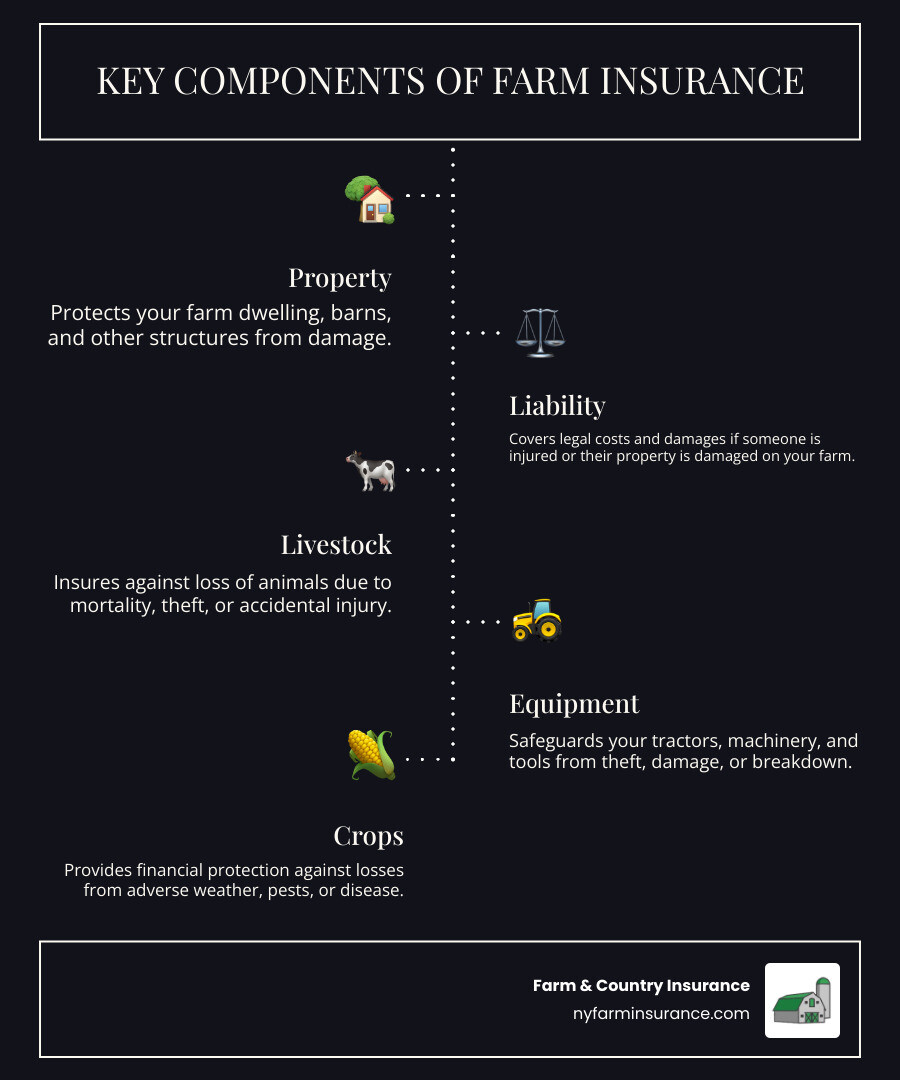
A comprehensive policy combines different coverages to protect what matters most. Let’s break down the essential components.
Essential Property Protection
Property coverage is the backbone of your policy, protecting your significant investments.
- Dwelling and personal belongings: This covers your farmhouse and its contents, similar to a homeowner’s policy but with farm-specific considerations.
- Outbuildings: Your barns, sheds, silos, and other structures are crucial to your operation. Their value, construction, and use all factor into your coverage.
- Farm machinery and equipment: Tractors, combines, and tools are vital assets. Protecting them from damage, theft, or breakdown is critical. Farm equipment typically costs around $15 to insure for every $1,000 in value. For example, a $380,000 combine could cost about $5,700 annually to insure.
It’s crucial to ensure your property values are current to avoid being underinsured. Learn more about protecting your investments by reading Is Your Farm Property Underinsured? The Answer Might Surprise You!.
Critical Liability Coverage
Liability coverage is crucial protection for when your farm operations cause injury to others or damage to their property. Consider these scenarios: a visitor gets injured, your livestock cause a road accident, or a customer gets sick from your produce.
Standard farm liability policies typically offer at least $1 million in coverage, but you may need more. Your exposure increases significantly if you host agritourism activities (corn mazes, U-pick), operate a farm stand, or have public access.
Specialized coverage may also be necessary for risks like pollution or product liability. It’s vital to match your liability coverage to your farm’s specific activities.
Protecting Your Livelihood: Livestock and Crops
Your animals and crops are your livelihood, and protecting these living investments requires specialized coverage.

Livestock coverage protects animals from perils like fire, lightning, disease, accidental injury, theft, and attacks by predators. The cost varies; for horses, expect to pay 2.5% to 5% of the animal’s value annually. For example, a $5,000 horse might cost $150 per year to insure.
Crop coverage cushions the blow from weather-related losses (hail, frost, wind), pests, and diseases. For diversified farms, the USDA’s Micro Farm Program is an excellent option. It provides whole-farm revenue protection, covering your entire farm’s income, including value-added products. This program is ideal for specialty crop, organic, and direct-to-consumer farms. With premium subsidies up to 80%, this federal program makes comprehensive coverage affordable nationwide.
The Big Question: What is the Average Small Farm Insurance Cost?
The most common question we hear is about the average small farm insurance cost. However, there’s no single answer, as costs vary widely based on each farm’s unique characteristics—much like pricing a car. Premiums are highly variable because no two farms are alike.
At Farm & Country Insurance, we specialize in building custom protection that fits your specific operation and budget, rather than offering one-size-fits-all solutions.
Key Factors That Determine Your Small Farm Insurance Cost
Your premium directly reflects your farm’s unique risks. Here are the key factors that determine your small farm insurance cost:
- Farm Type and Operations: A dairy farm has different risks than a fruit orchard or an operation with agritourism activities.
- Location: Your farm’s location in New York, including proximity to fire departments and local weather patterns, affects your rate.
- Acreage and Asset Value: More land, buildings, equipment, and livestock mean higher values to insure.
- Claims History: A clean record can lower your premiums, while a history of claims may increase them.
- Coverage Limits and Deductibles: Higher limits and lower deductibles typically result in higher premiums.
- Safety Measures and Workers: Proactive safety measures can lead to lower rates. If you have employees, workers’ compensation insurance is a necessary cost dictated by state law.
For a deeper dive into these factors, read our guide on Small Farm Business Insurance.
Is Insurance Legally Required for My Small Farm?
Generally, there is no statewide law mandating small farm insurance. However, it is often required in other circumstances:
- Lenders: Banks require insurance for farm mortgages or equipment loans to protect their investment.
- Contracts: Agreements with restaurants, farmers’ markets, or event hosts often stipulate liability coverage.
- Employees: New York State law may require you to carry workers’ compensation insurance if you hire any workers.
While not always legally mandated, comprehensive farm insurance is a prudent business decision that protects your investments and provides peace of mind, letting you focus on farming.
Estimated Costs: A General Guideline
While we need your farm’s specific details for an exact quote, these general guidelines can help with budgeting. Your actual small farm insurance cost will vary.
- Hobby Farms: Typically $500 to $2,500 annually, depending on assets and activities.
- Small Farms (under 100 acres): Approximately $2,000 to $3,000 per year.
- Mid-size Farms (100-500 acres): Often $2,500+ per year, increasing with acreage and complexity.
- Larger Small Farms (500-1500 acres): Annual premiums can exceed $3,500.
These are broad estimates. Your final cost depends on the specific value of your buildings, equipment, and livestock. As mentioned, equipment can be insured for around $15 per $1,000 of value, and livestock for 2.5% to 5% of its value annually. These figures help Farm & Country Insurance create a precise, personalized quote for you.
Smart Savings: How to Lower Your Insurance Premiums
We get it. Managing your small farm insurance cost is a big part of keeping your farm financially healthy. After all, every penny counts when you’re working the land! At Farm & Country Insurance, we’re all about helping you find smart ways to save. You don’t have to sacrifice essential protection to keep your budget happy. The secret to smart savings? It’s a blend of proactive choices on your farm and strategic decisions about your policy.
Proactive Risk Management
Think of it this way: a safer farm is often a cheaper farm to insure! When you actively work to reduce the chances of something going wrong, insurance companies notice. They often reward farms that show a real commitment to safety and preventing losses with lower premiums. Here are some simple, actionable steps you can take:
First, let’s talk about safety protocols. Regular check-ups for all your farm machinery and equipment are a must. Make sure anyone operating equipment knows what they’re doing – proper training can prevent accidents. For your livestock, keep those fences secure! Good animal husbandry practices keep your animals healthy and prevent them from wandering off or getting hurt.
Next, fire prevention is incredibly important. Keep your barns and outbuildings tidy and free of clutter. Check your electrical systems to make sure they’re up to code. Have easily accessible fire extinguishers and, most importantly, a clear plan for what to do if a fire breaks out.
Don’t forget general property maintenance. Addressing potential hazards around your farm – like uneven ground, broken steps, or loose materials – can significantly reduce the risk of someone getting injured, whether it’s a visitor or a worker.
For those with livestock, smart grazing practices can also make a difference. Things like dividing pastures, limiting grazing time, and giving your grass enough rest can lead to healthier animals and pastures. This, in turn, reduces risks. You can find more helpful recommendations for even grazing from experts to keep your animals and land in top shape.
Finally, always be open and honest with your insurance provider. Make sure they know about all your farm activities. Trying to hide information can lead to big problems later, like denied claims or even your policy being canceled. That would cost you far more in the long run than being upfront.
By taking these proactive steps, you’re not just making your farm a safer place; you’re also showing insurers that you’re a lower risk. This can open the door to valuable discounts on your premium.
Choosing the Right Policy and Deductibles
Beyond keeping your farm safe, there are smart choices you can make about your insurance policy itself that can lead to significant savings:
Consider bundling your policies. If you currently have your home, auto, and farm insurance with different companies, it might be time to bring them all under one roof with Farm & Country Insurance. We can often offer multi-policy discounts when you combine your coverages. It not only saves you money but also simplifies managing all your insurance needs.
Another strategy is choosing a higher deductible. This means that if you have a claim, you’ll pay a bit more out-of-pocket before your insurance kicks in. But in return, your annual premium will be lower. This can be a great option for farms that have a healthy emergency fund and don’t expect to have frequent small claims.
Your farm is always changing, and your insurance should too! That’s why an annual policy review is so important. We recommend sitting down with us every year, or whenever you make big changes to your operations – like buying new equipment, expanding your land, adding new products, or hiring employees. This ensures your coverage is always accurate. You don’t want to be paying for coverage you no longer need, or worse, find yourself without the coverage you desperately do need.
Finally, remember to leverage our expertise. As an independent agency, Farm & Country Insurance doesn’t work for just one insurance company. We work with many different carriers. This means we can shop around on your behalf to find the most competitive rates and the best coverage options specifically custom to your unique farm. Our goal is to help you get the Best Farm Insurance for your budget, ensuring you’re well-protected without breaking the bank.
Frequently Asked Questions about Small Farm Insurance
We get a lot of questions about farm insurance here at Farm & Country Insurance, and we’re always happy to provide clear, straightforward answers. Think of us as your helpful neighbors, ready to chat about what really matters for your farm. Here are some of the most common questions we hear, designed to address your concerns and help you better understand your policy. For even more information, visit our Farm Insurance FAQs.
How is hobby farm insurance different from a standard homeowner’s policy?
This is a big one, and it’s super important to understand! Imagine your standard homeowner’s policy as a cozy blanket for your house and personal stuff. It’s great for covering things like a leaky roof or a stolen bike. But when it comes to your farm activities – even small ones – that blanket often has big holes.
For example, your homeowner’s policy won’t protect your farm equipment, like that trusty old tractor. It also won’t cover your outbuildings, such as your barn or sheds, where you store tools or house your animals. And here’s the kicker: it won’t cover your livestock or any specific liabilities that come from your farming operations.
Let’s say a visitor trips over a hose while helping with chores, or your chicken coop catches fire. Your homeowner’s policy likely won’t step in to help. That’s why hobby farm insurance is specially designed to fill these crucial gaps. It gives you custom coverage for your unique farm assets and activities, making sure you’re truly protected.
Do I need special insurance if I sell products at a farmers market?
Yes, you absolutely do! If you’re selling your delicious produce at a farmers market, through a CSA, or even right from your own farm stand, you need special insurance. Your general farm liability coverage needs to be strong enough to include something called “products liability.”
This is super important. It protects you in case a customer ever claims they got sick or were injured from a product you sold. We all hope that never happens, but be prepared.
What if you’re also inviting people to your farm for fun activities? Say you have a U-pick operation, farm tours, or even a corn maze. This is called agritourism. When you welcome the public onto your property, your liability risk goes up a lot. You’ll need specific coverage for these activities to protect against any claims from visitors.
How often should I review my farm insurance policy?
Think of your farm as a living, breathing thing. It’s always growing, changing, and facing new challenges. Because of this, your insurance policy shouldn’t be a “set it and forget it” kind of deal. We strongly recommend reviewing your farm insurance policy at least once a year with your agent at Farm & Country Insurance.
An annual review helps us make sure your coverage limits are still enough for what you have. Did you buy new equipment? Build a new shed? We need to add those! Are you trying out new crops, adding different animals, or starting a new agritourism venture? These new activities need to be properly covered.
But don’t wait just for the annual check-up if big changes happen! If you make a major purchase, sell off a piece of land or equipment, hire new workers, or even notice significant changes in local weather patterns, pick up the phone. An immediate review helps us adjust your policy to your current needs. This proactive approach helps avoid any surprising gaps in your coverage or paying unnecessary small farm insurance cost. It keeps your protection just right, always.
Conclusion: Securing Your Farm’s Future
Whew! We’ve covered a lot of ground today, haven’t we? Understanding small farm insurance cost and what goes into protecting your slice of heaven might have seemed like a big puzzle at first. But we hope you now see that it’s not about daunting complexities; it’s about building a strong, reliable financial safety net for your farm.
Think of it this way: your farm is a living, breathing dream. It’s where you pour your heart, sweat, and passion. Just like you nurture your crops and care for your livestock, your farm needs essential protection from the unexpected. We’ve talked about everything from figuring out if you’re a hobby farm or a small commercial operation, to decoding what your policy actually covers, and even smart ways to save on premiums. The big takeaway is always the same: customizable coverage and proactive planning are truly your best friends.
Here at Farm & Country Insurance, we get it. We’ve been deeply rooted in New York’s farming communities since 1984, working alongside dairy, grain, fruit, and vegetable farms, plus all sorts of agribusinesses. This isn’t just business for us; it’s understanding the unique risks you face every single day. Our expert guidance means we’re uniquely positioned to offer comprehensive coverage and risk management services that truly fit.
Your livelihood is precious, and we believe protecting it shouldn’t break the bank. That’s why we’re dedicated to finding custom solutions as diverse as the beautiful farms we serve. We’re here to help you safeguard your investment, nurture your passion, and finally, give you that peace of mind you deserve.
So, why leave your farm’s future to chance? Let’s chat. We’re ready to answer your questions, assess your specific needs, and build a policy that fits your farm perfectly, just like your favorite pair of work boots.
Contact us today to discuss your Insurance for Small Farms needs. We genuinely look forward to partnering with you!