
Small Farm Product Liability Insurance 2025: Protect
Why Small Farm Product liability Insurance is Essential for Your Business
Small farm product liability insurance protects farmers from financial losses if customers become ill or injured from consuming their products. Understanding your liability exposure is critical to protecting your operation, especially when your business centers on food production.
Key reasons you need product liability coverage:
- Direct sales require protection – Many farmers’ markets now require product liability insurance in amounts over $500,000.
- Foodborne illness claims are expensive – Medical costs, legal defense, and settlements can quickly exceed your farm’s assets.
- Customer relationships don’t prevent lawsuits – As one expert noted: “No matter how good the friendship, that good will ends at the emergency room door.”
- Your farm owner’s policy has gaps – Standard policies provide limited coverage for product-related claims.
Whether you’re selling fresh produce at a roadside stand, supplying restaurants, or creating value-added products like jams, your farm faces unique liability risks that require specialized protection.
Nationally reported incidents like E. coli in spinach or listeria in melons are stark reminders that the unexpected can happen. Even the most careful farmers need comprehensive product liability coverage.
At Farm & Country Insurance, we’ve spent years helping New York farmers steer the complexities of small farm product liability insurance. Our deep understanding of agricultural risks and specialized focus on farm insurance allows us to provide custom solutions that protect your livelihood.
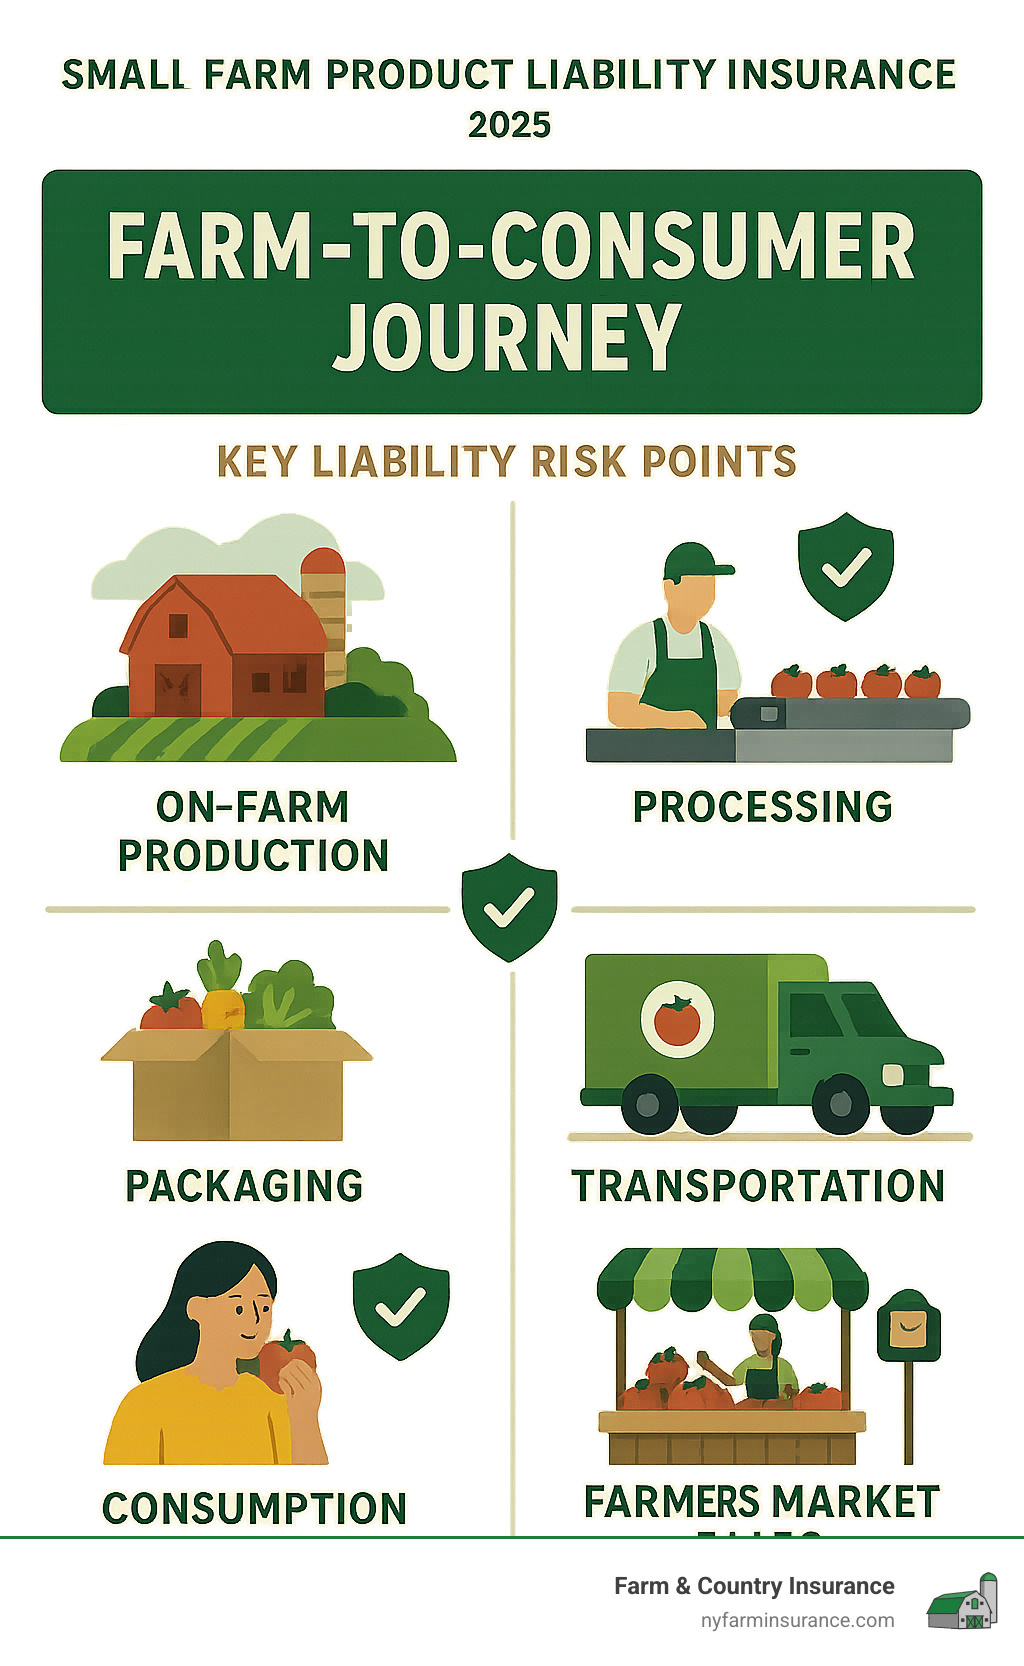
Simple small farm product liability insurance word guide:
What is Farm Product Liability Insurance and Why is it Crucial?
Small farm product liability insurance is your shield against financial disaster when someone claims your farm products caused them harm. This coverage protects you when things go wrong after your products—from fresh tomatoes to strawberry jam—leave the farm.
Even the most careful farmers face uncontrollable risks, like a customer’s allergic reaction or contamination during transport. The resulting bodily injury claims can quickly spiral into five or six-figure lawsuits.

Headlines about E. coli or listeria outbreaks show the devastating financial impact of foodborne illness risk. This includes not just medical costs and settlements, but also the legal defense costs that accumulate even if you’re not at fault.
This insurance provides crucial financial protection. Legal fees alone can bankrupt a small farm, but your policy handles these expenses, letting you focus on farming.
Coverage also opens doors to accessing new markets. Many New York farmers’ markets now have strict farmers’ market requirements, often mandating $500,000 or more in product liability insurance. Restaurants and grocery stores also demand proof of coverage for wholesale relationships. This demonstrates your professionalism and commitment to food safety.
For comprehensive details about coverage options and requirements, visit our dedicated resource: More info about Farm Product Liability Insurance.
Differentiating from General Farm Liability
Many farmers mistakenly believe their general farm liability policy covers everything. However, the two types of insurance address completely different scenarios.
General farm liability covers incidents on your property (premises liability) and during your work (operations liability). Examples include a customer slipping at your farm stand or your equipment damaging a neighbor’s fence. It protects against accidents at your farm or resulting from your activities.
Small farm product liability insurance focuses on product-specific claims after your products leave the farm. It covers claims from your products causing illness or injury, such as food poisoning from spinach or an allergic reaction to salsa.
Understanding this difference is critical. A customer who trips at your farm stand needs general liability coverage. That same customer who gets sick from your produce at home needs product liability protection.
For more information about general coverage options, explore our guide: More info about Farm Liability Insurance.
| Coverage Type | General Farm Liability | Product Liability Insurance |
|---|---|---|
| What’s Covered | On-farm accidents, property damage, operational injuries | Illness or injury from consuming farm products |
| Where Claims Occur | On your farm property or during farm operations | Anywhere products are consumed after leaving your farm |
| Example Scenario | Visitor falls in your barn | Customer gets food poisoning from your vegetables |
| Primary Focus | Property safety and operational risks | Product safety and food-related claims |
| Typical Requirements | Standard for most farm operations | Essential for direct sales and processed products |
Both coverages work together to create comprehensive protection, but neither can substitute for the other.
When Do You Need Small Farm Product Liability Insurance?
The moment you sell your first product—be it a basket of tomatoes or a jar of honey—you’re exposed to product liability. Small farm product liability insurance becomes essential the instant you start selling anything for consumption.
Direct-to-consumer sales are a primary source of liability. Whether you run a roadside stand in Montezuma, an on-farm market in Skaneateles, or a U-pick operation in Owasco, you are directly liable if a customer claims your product caused illness.
Many farmers’ markets across New York, from Auburn to Syracuse, now require vendors to carry product liability insurance, often with limits over $500,000. When selling to wholesalers, restaurants, and grocery stores, your risk increases. If your product makes someone sick, your farm could be named a co-defendant in a lawsuit, sharing costs even if contamination occurred after delivery.
Be aware that products you buy from other farms to resell are typically not covered under standard farm policies and require separate coverage.
How Value-Added Products Impact Your Insurance Needs
Changing raw farm products into jams and jellies, baked goods, or sliced produce introduces a new level of liability.
Each processing step introduces new risks. Slicing apples creates an increased processing risk from spoilage. Mixing, cooking, or canning creates opportunities for hazards not present in whole produce.
Crucially, your homeowner’s insurance almost certainly excludes commercial use of your home kitchen. You will need separate coverage for these business activities.
Co-packer arrangements add another layer of complexity. If a co-packer processes your product but your farm’s name is on the label, you could still be liable for any problems. Each step away from a whole product increases your need for comprehensive small farm product liability insurance. Don’t let this deter you from creating value-added products; just ensure you’re properly protected.
Understanding Your Policy: Costs, Coverage, and Exclusions
To get the right small farm product liability insurance, we’ll build a policy that fits your unique operation. At Farm & Country Insurance, we know every New York farm is different, from a berry farm in Cayuga County to a vegetable operation near Syracuse.
Getting an accurate quote requires detailed information. We’ll need detailed product descriptions, your years of production, documentation of your food safety protocols, and your sales records. Honesty about any past claims is also crucial, as hiding information could void your policy.
Ready to get started? You can begin the process with us here: Get Insurance Quotes.
Factors Influencing the Cost of Small Farm Product Liability Insurance
The cost of small farm product liability insurance varies widely and depends on several key factors:
- Sales volume: Both actual and projected sales impact your premium. It’s better to be fully covered than underinsured.
- Product type: Processed goods carry higher risks and premiums than raw produce because each step adds potential for contamination.
- Claims history: A clean track record helps keep costs down.
- Coverage limits: Higher limits mean more protection but higher premiums. Many farmers’ markets require at least $500,000.
- Deductible: A higher deductible reduces your premium but increases your out-of-pocket cost per claim.
Common Policy Exclusions and Limitations
Understanding what your policy doesn’t cover is as important as knowing what it does. Be aware of common exclusions:
- Foodborne pathogen exclusions: Some policies exclude certain pathogens or have sublimits for contamination. A broad “bacteria exclusion” could leave you unprotected.
- Products bought for resale: Items you buy from another farm to resell are typically not covered and require separate insurance.
- Unlisted products: Failing to declare all products, even seasonal or test items, can void your policy if a claim arises. Always inform your agent of everything you sell.
- Ambiguous wording: Work with an experienced agent who understands farming to spot problematic language and ensure you understand your policy.
At Farm & Country Insurance, we’ve helped New York farmers steer these complexities since 1984. For more insights into policy limitations, check out: More info about Farm Insurance Policies.
Proactive Protection: Mitigating Risks and Managing Liability
The best approach to small farm product liability insurance is proactive. Building a fortress of good practices protects your customers and your farm’s future, saving you money and stress.

Proactive New York farms reduce risk by adopting Good Agricultural Practices (GAPs) and Good Handling Practices (GHPs). These voluntary standards build trust and can lower insurance premiums. Key on-farm best practices include:
- Sanitation protocols: Regular equipment sanitizing, handwashing, and clean work surfaces should be daily habits.
- Employee training: A well-trained team understands proper food handling and can spot potential issues before they become claims.
- Record keeping: Meticulous records of planting, harvesting, and cleaning are invaluable during a claim, proving you followed procedures.
- Traceability: Being able to trace produce to a specific field and harvest time can mean the difference between a minor issue and a crisis.
- Recall plans: Having a clear strategy for notifying customers and removing products can dramatically reduce the impact of a safety issue.
What is Product Recall Insurance?
Product recall insurance is typically a separate coverage from standard product liability. While liability covers damages from injury, recall insurance covers the costs of removing products from the market.
This coverage is crucial for sales to wholesalers, restaurants, or grocery stores. The notification costs to alert distributors and the product removal costs can be substantial. If your products reach customers through multiple channels across New York, recall insurance is a smart investment.
For more information about building a complete insurance strategy for your operation, explore our guide: More info about Agriculture Insurance for Small Farms.
Frequently Asked Questions
At Farm & Country Insurance, we’ve heard these same concerns from countless New York farmers. Let’s tackle the most common questions about small farm product liability insurance.
How much coverage do I need for my small farm?
There’s no single answer; your coverage needs are unique to your farm. The amount depends on your type of operation (raw produce vs. processed foods), your sales volume, and your sales channels. Many farmers’ market rules require at least $500,000 in coverage, and some distributors want higher limits. We recommend a thorough risk assessment with an agent to determine the right amount to protect your assets.
For more detailed guidance custom to small farms, visit: More info about Insurance for Small Farms.
Does my homeowners insurance cover my farm products?
The answer is almost always no. This common misconception can be a costly mistake. Your homeowners policy is for personal, not commercial, use. Selling products is a commercial activity, which is typically excluded from homeowners policies via a commercial activity exclusion. Even if your farm feels small, regular sales to the public require dedicated coverage. This is why proper Small Farm Business Insurance is so important.
Can I get coverage if I’m a new farm with no sales history?
Yes. A lack of sales history isn’t a barrier for new farms. For new operations, we work based on projections. We’ll review your business plan, anticipated sales, products, and safety protocols to tailor your coverage. Working with an experienced agent is particularly valuable for new farms. At Farm & Country Insurance, we’ve helped New York farmers since 1984 and can guide you through the process as your farm grows.
Conclusion: Partnering for Peace of Mind
Running a small New York farm is rewarding but has real risks. This guide has shown how essential small farm product liability insurance is for protecting your livelihood. If you sell consumable products, you are exposed to liability. One incident could threaten your entire operation.
You don’t have to face these risks alone. Small farm product liability insurance provides financial protection, while proactive risk management helps prevent incidents. The key is having the right custom coverage for your unique farm.
At Farm & Country Insurance, we’ve partnered with New York farmers since 1984. We know a dairy farm in Cayuga County has different needs than a vegetable farm in Skaneateles. We reject cookie-cutter solutions, instead taking time to understand your specific operation to craft custom coverage.
Your farm represents years of hard work and dedication. Don’t let the unexpected derail it. When you partner with us, you gain peace of mind and a trusted advisor who understands the challenges facing New York’s agricultural community.
Ready to protect what matters most? Learn more about our insurance for small farms and find how Farm & Country Insurance can help safeguard your operation for years to come.