
Tractor insurance policy: Top 5 Ultimate Safeguards
Why Understanding Tractor Insurance Policy Basics Matters for NY Farmers
A tractor insurance policy is specialized coverage that protects your tractor against physical damage, theft, and liability claims—risks a standard homeowner’s policy won’t cover. For New York farmers, from the Finger Lakes to the Hudson Valley, a tractor is a critical asset representing a significant investment.
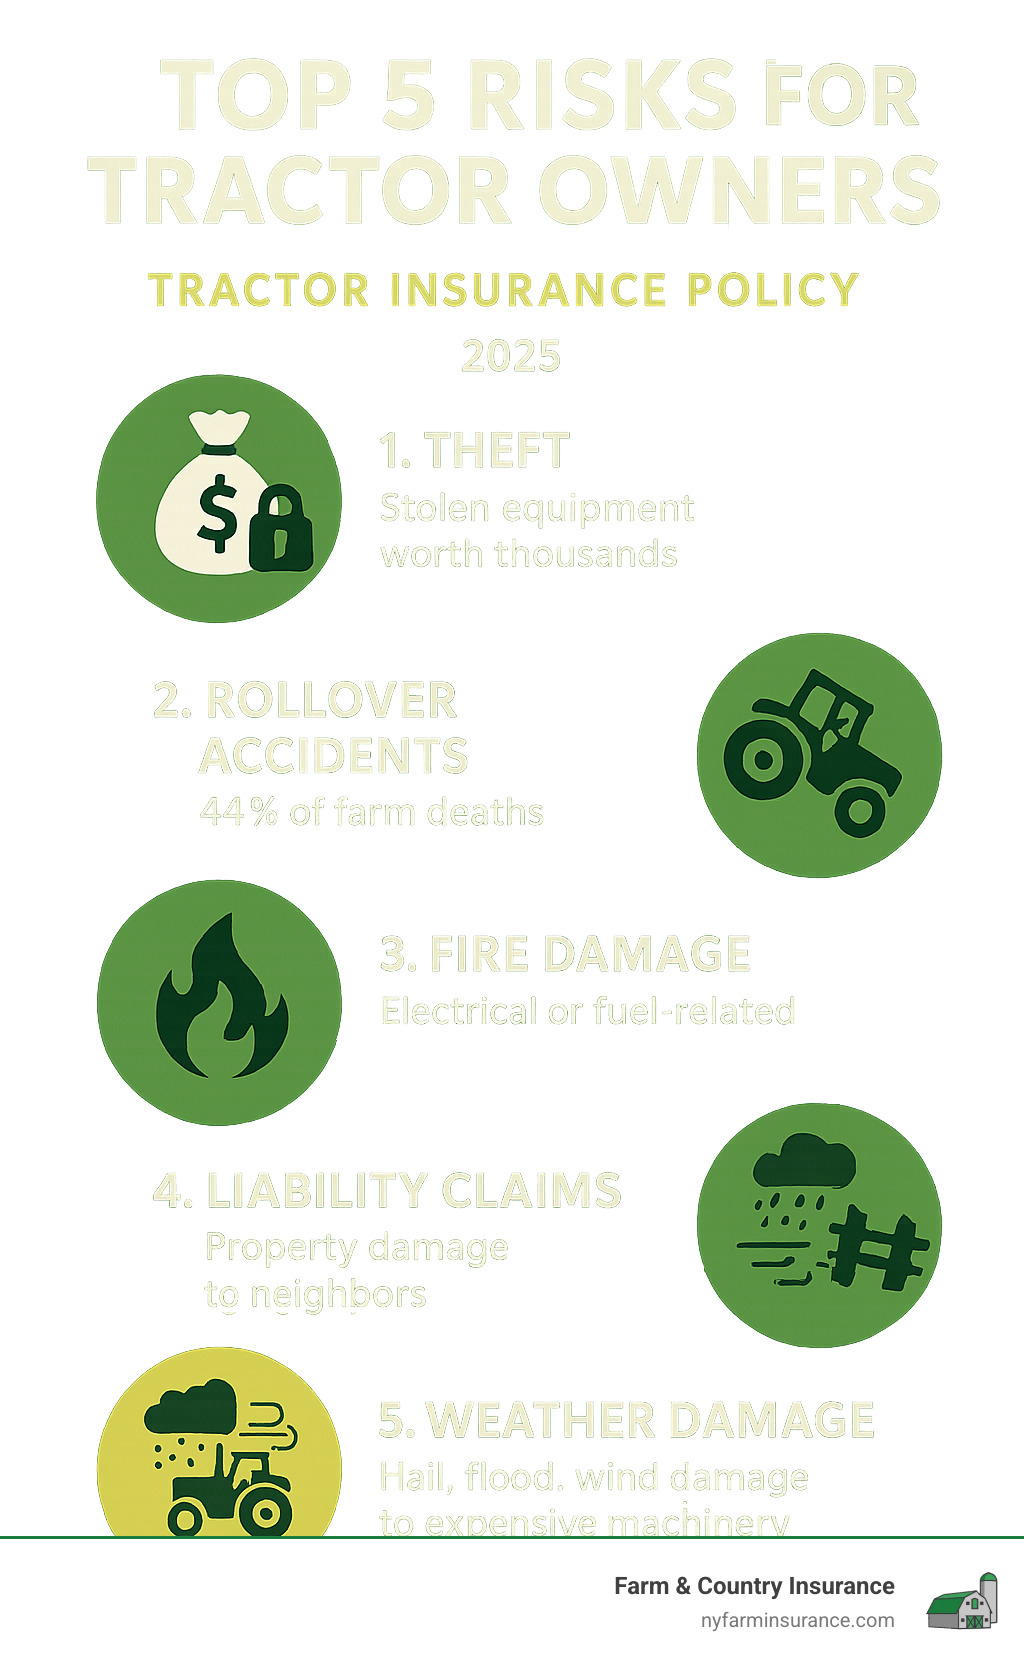
The financial risks are stark. A single accident, theft, or weather event can lead to massive repair bills or the total loss of your equipment. Tragically, tractor rollovers account for 44% of work-related deaths on farms, highlighting the need for comprehensive protection.
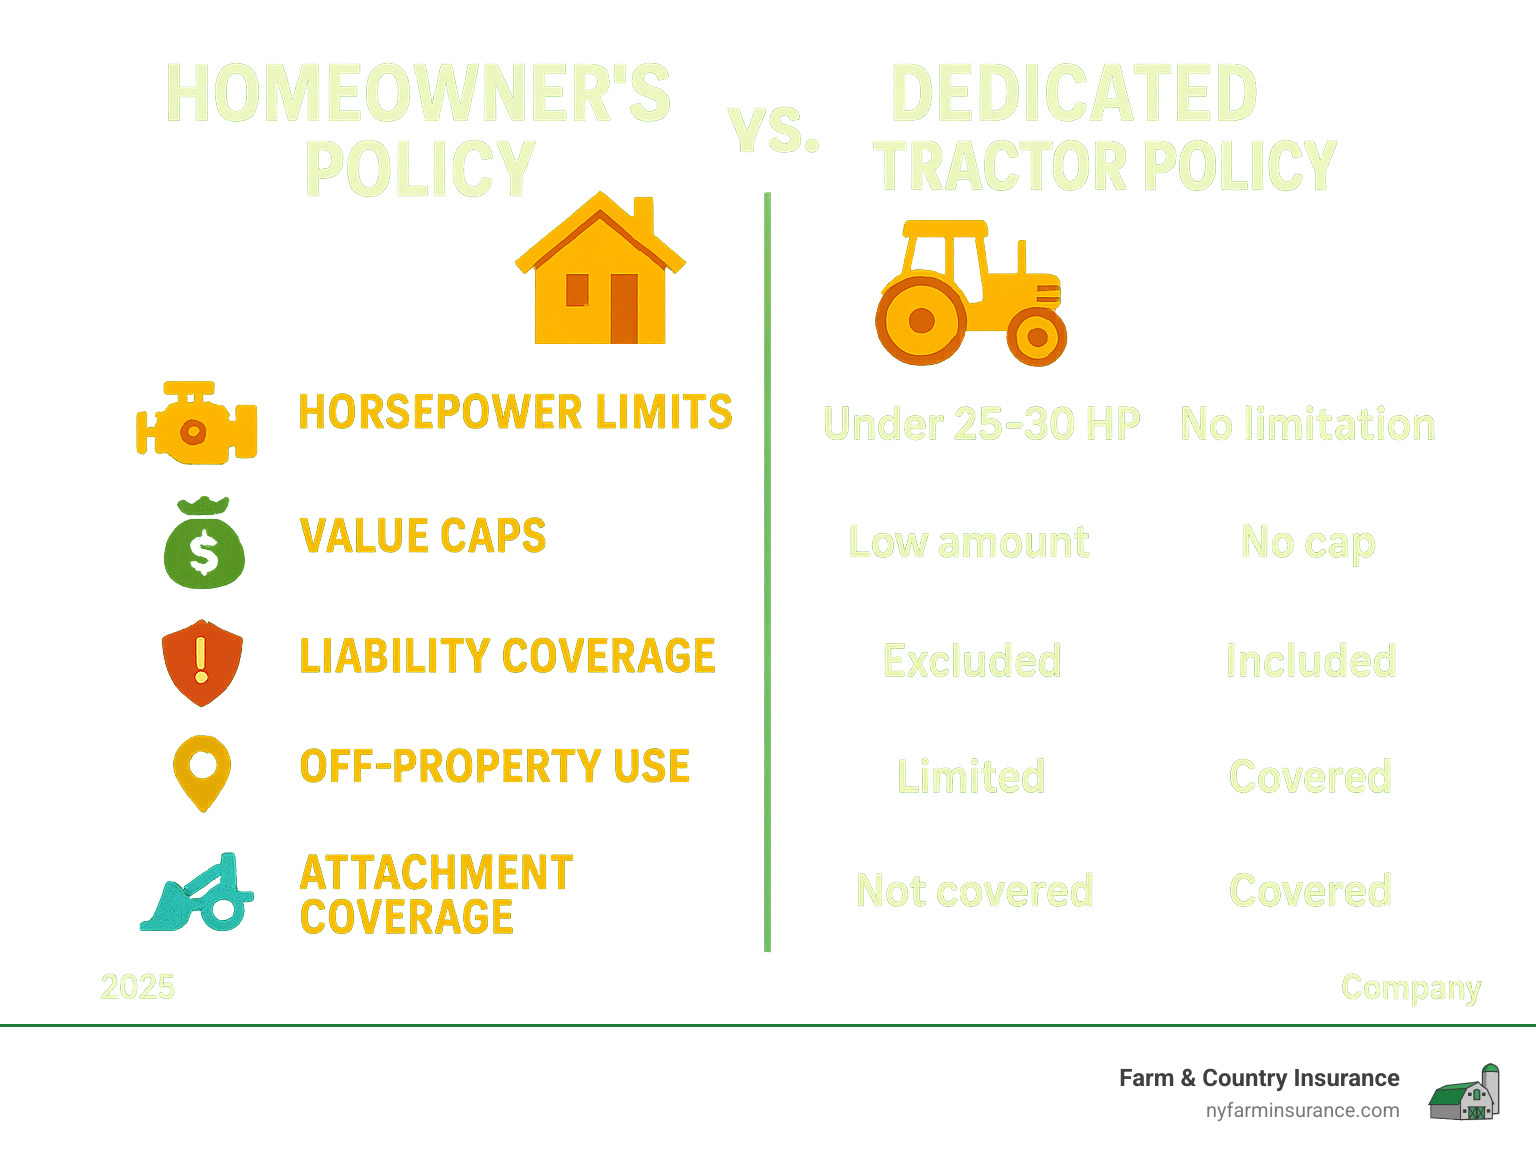
Many farmers find too late that their homeowner’s insurance is inadequate, often limiting coverage to tractors under 25-30 horsepower and capping payouts at just $5,000. This is a fraction of what modern farm equipment costs.
At Farm & Country Insurance, we’ve spent years helping New York farmers steer tractor insurance policy options. We understand that the right coverage can mean the difference between a minor setback and a financial disaster for your dairy, grain, fruit, or vegetable operation.
Tractor insurance policy glossary:
Why Your Tractor is an Asset Worth Protecting
Your tractor is the heart of your farming operation and a significant financial asset. Modern tractors can cost anywhere from $15,000 to over $350,000, and that’s before adding specialized attachments. The cost of repairs can be just as daunting—a major engine overhaul can run $15,000 or more. Without proper coverage, a theft or fire could mean facing the full replacement cost out of pocket.
Beyond the equipment itself, there’s a significant liability risk. If your tractor damages a neighbor’s property or causes an injury, you could face substantial legal fees and settlement payments without adequate liability coverage in your tractor insurance policy. Protecting this asset is about safeguarding the tools that keep your operation running. For more information, see our guide on Farm Equipment Insurance.


The Critical Difference: Homeowner’s vs. Dedicated Tractor Insurance
Many farmers assume their homeowner’s insurance covers their tractor, but this coverage is often dangerously insufficient.
- Horsepower & Value Limits: Most homeowner’s policies treat tractors like lawn mowers, capping coverage at 25-30 horsepower and around $5,000 in value. This is far below the cost of a modern compact tractor, let alone its attachments. A dedicated tractor insurance policy can provide coverage up to $80,000 or more, matching your equipment’s actual value.
- Liability Exclusions: Homeowner’s policies often exclude liability for tractors that exceed their horsepower limits. If you cause damage or injury with a tractor deemed “too powerful,” you could be personally responsible for all costs.
- Off-Property Use: Homeowner’s coverage is typically restricted to your property. The moment you drive across the road to help a neighbor, you may lose coverage. A dedicated policy follows your equipment wherever you use it.
- Attachment Gaps: Valuable attachments like an $8,000 backhoe might not be covered at all under a homeowner’s policy or are lumped into the same inadequate $5,000 limit.
At Farm & Country Insurance, we focus on these critical differences to ensure New York farmers get coverage that matches their reality. For broader insights, explore our Farm Insurance guide.
Is Tractor Insurance Mandatory in New York?
In New York, a tractor insurance policy is not legally required for equipment used exclusively on private land. However, this doesn’t mean operating without it is wise.
- Lender Requirements: If you financed your tractor, your lender will almost certainly require you to maintain comprehensive coverage to protect their investment until the loan is paid off.
- Public Road Use: The rules change the moment your tractor touches a public road. While NY has exemptions for farm equipment, operating on public roads without liability coverage is a massive financial risk.
- Off-Property Work: Helping a neighbor or doing custom work creates liability exposure that a homeowner’s policy won’t cover. A dedicated policy protects you wherever your work takes you.
The bottom line: while not always mandated by law, the financial risks of operating without a proper tractor insurance policy far outweigh the premium cost. It’s about protecting your investment and financial security. For vehicles that do travel on public roads, see our Farm Auto Insurance resources.
What a Comprehensive Tractor Insurance Policy Covers
A comprehensive tractor insurance policy from Farm & Country Insurance is a complete safety net designed for the real-world risks New York farmers face. It addresses everything from equipment theft to liability claims that could threaten your operation.

Key protections in a solid tractor insurance policy include:
- Physical Damage: This is the backbone of your policy, covering repair or replacement costs from collisions, rollovers, and fire.
- Theft Protection: As tractors become more high-tech, they are more attractive to thieves. This covers the theft of the tractor and its components, like GPS systems.
- Weather-Related Damage: Protects your equipment from hail, flooding, wind, and other natural disasters.
- Personal Liability Coverage: This is a critical component. If your tractor damages property or injures someone, this covers medical bills, repairs, and legal defense costs, with policies often offering up to $2 million in coverage.
- Attached Equipment Coverage: A dedicated policy protects your valuable front-end loaders, backhoes, and mowers, listing them for their full value.
For more details, visit our Farm Equipment Insurance Coverage page.
Core Coverage Types Explained
Understanding the components of your tractor insurance policy helps you make informed decisions.
- Comprehensive: Covers “all-risks” when your tractor isn’t running, such as theft, vandalism, fire, flood, and storm damage.
- Collision: Pays for physical damage to your equipment when it’s in use, such as hitting an object or tipping over.
- Liability: Your financial shield against claims from third parties for property damage or injury you cause while operating the tractor.
- Attached Equipment: Ensures your implements are protected alongside your tractor when they are listed on your policy.
- Replacement Cost vs. Actual Cash Value (ACV): Replacement cost pays for a new tractor of similar quality (usually for newer models), while ACV pays the depreciated value. Most farmers prefer replacement cost to get back to work faster.
Learn more about protecting your machinery on our Agricultural Equipment Insurance page.
Factors That Influence Your Premium
The cost of your tractor insurance policy is based on specific risk factors.
- Tractor Age, Make, and Model: Newer, more valuable tractors cost more to insure but may qualify for better coverage options like replacement cost.
- Usage: A tractor for light hobby farm maintenance will have a lower premium than one used for intensive commercial farming.
- Storage: Storing your tractor in a locked, secure building can lower your premium by reducing theft and weather risks.
- Driving Record: A clean record helps keep liability premiums down if you operate on public roads.
- Deductible: A higher deductible lowers your premium, but you’ll pay more out-of-pocket for a claim.
For information on protecting your broader operation, see our Farm Business Insurance page.
Special Considerations for Your Tractor Insurance Policy
Not all tractors are the same, and your insurance shouldn’t be either.
- Antique and Classic Tractors: For machines 25+ years old used for shows or parades, specialized coverage can be based on an “agreed value” rather than its depreciated worth.
- Hobby Farm Use: If your tractor is for personal property maintenance rather than for-profit farming, your policy can be custom to reflect lighter-duty use.
- Commercial Farming: These operations require robust coverage with higher liability limits and potential protection for equipment breakdown or lost income.
- Community/Neighbor Use: If you use your tractor to help neighbors or clear local roads, a dedicated policy extends your liability protection beyond your property lines.
For smaller farms, find valuable insights on our Small Farm Business Insurance page.
How to Secure and Use Your Tractor Insurance
Getting the right tractor insurance policy should be straightforward. At Farm & Country Insurance, we’ve streamlined the process to make it as painless as possible, from your first quote to filing a claim.
Working with a local expert who understands New York farming provides personalized service. We know the difference between a hobby farm in Cayuga County and a commercial grain operation, and we tailor our approach accordingly. Learn more about how we help at our Farm Insurance Brokers page.
The Application Process: What You’ll Need
To get an accurate quote for your tractor insurance policy, have the following information ready:
- Tractor Details: Make, model, year, and Vehicle Identification Number (VIN).
- Financial Information: Purchase price or current market value to set proper coverage limits.
- Attachments: A detailed list of all attachments (loaders, backhoes, mowers, etc.) and their value.
- Usage Details: How the tractor is used (personal maintenance, commercial farming, etc.).
- Storage and Operator Info: Where the tractor is stored and, if applicable, driver information for primary operators.
Steps to Take After an Accident or Theft
Being prepared can make a stressful situation more manageable. If an incident occurs:
- Ensure Safety & Contact Authorities: In case of theft, contact the police immediately and get a report number. For accidents involving injury or significant damage, call the authorities.
- Document Everything: If it’s safe, take photos and videos of the damage and the scene. Note the date, time, and location.
- Notify Farm & Country Insurance: Contact us as soon as possible to start the claims process. The sooner you call, the faster we can help.
- Prevent Further Damage: Secure your tractor to prevent additional damage, but do not begin major repairs before speaking with your adjuster.
- Keep All Records: Save every receipt and invoice related to the incident, including towing, temporary repairs, and final repair work.
We know your tractor is vital to your farm’s operation, and our goal is to get you back up and running as quickly as possible.
Frequently Asked Questions about Tractor Insurance
As specialists in New York farm insurance, we get many thoughtful questions about tractor insurance policy coverage. Here are answers to some of the most common ones.
Are my tractor’s attachments covered?
Yes, a dedicated tractor insurance policy from Farm & Country Insurance can cover your attachments, but they must be specifically listed on your policy. This is a critical detail. We will work with you to schedule your front-end loaders, backhoes, mowers, and other implements to ensure they are properly valued and protected. This is a major advantage over homeowner’s policies, which typically have very low limits for such equipment, if they cover them at all.
What’s the difference between a tractor policy and general farm equipment insurance?
A tractor insurance policy is a specific form of protection focused solely on your tractor and its attachments. General Farm Equipment Insurance, on the other hand, is broader, designed to cover your entire fleet—combines, balers, sprayers, and more—under a single policy. For farmers with just one tractor, a dedicated policy is often ideal. For larger operations, a comprehensive farm equipment policy can be more efficient. We help you match the coverage to your specific needs.
Can I get a tractor insurance policy for a non-commercial or hobby farm?
Absolutely. Farm & Country Insurance provides policies for all types of operations, from large commercial agribusinesses to small hobby farms. A tractor insurance policy should reflect your actual use. A tractor used for light property maintenance has a different risk profile than one used for daily commercial work, and we tailor the coverage and pricing accordingly. Being transparent about your tractor’s use ensures you get the right protection at a fair price.
Conclusion: Get the Right Protection for Your NY Farm
Your tractor is the heartbeat of your New York farm, a significant financial investment, and the key to your productivity. As we’ve seen, standard homeowner’s insurance often leaves dangerous gaps with its low horsepower limits, value caps, and liability exclusions. A single accident or theft could be devastating without the right protection.
At Farm & Country Insurance, we’ve specialized in protecting New York farmers since 1984. We understand that the needs of a dairy operation in Auburn differ from a vegetable farm in Throop or a hobby farm in Genoa. We don’t offer one-size-fits-all solutions; we create custom policies by taking the time to understand your specific operation, equipment, and risks.
The right tractor insurance policy can mean the difference between a minor setback and a catastrophic loss. Don’t wait for a disaster to find gaps in your coverage. Our experienced team is proud to serve farming families across New York State, helping them steer insurance complexities and create a plan that provides true peace of mind.
Your farm is your legacy. Your tractor helps build it. Ensure both are protected with coverage you can count on. Get a quote for your Farm Equipment Insurance today and experience the Farm & Country Insurance difference.